Best overall for a defined expense: an unsecured term loan. Best for recurring cash flow gaps: an unsecured business line of credit. Best alternative to compare for revenue-based funding: 2M7, a direct funder offering merchant cash advances, not loans. This 2026 guide compares unsecured business loans in Canada with other funding structures, including where each option falls short.
TL;DR
- Unsecured business loans suit defined expenses when scheduled payments fit your cash flow.
- An unsecured business line of credit suits recurring working capital gaps, not permanent operating losses.
- 2M7 offers merchant cash advances, not loans; confirm security requirements before treating an offer as unsecured.
- Compare total repayment, personal guarantees and payment frequency before choosing business funding in Canada.
Why this matters
Unsecured does not mean the owner has no personal exposure. An unsecured business loan generally does not require specific collateral, but a lender can still require a personal guarantee. Read the actual agreement rather than relying on the product label.
That distinction matters when comparing offers in 2026. A loan, a revolving credit facility and a merchant cash advance have different structures. Choosing between them starts with what you need the money to do and how your business will meet the payment schedule.
This shortlist ranks funding structures by use case, not individual lenders by advertised claims. There is no universal winner: a facility that handles recurring inventory purchases is not automatically the right choice for a single equipment purchase.
What makes the best unsecured business loans?
Use these criteria before choosing a funding provider:
- Purpose fit: Match a defined purchase to structured funding and recurring gaps to reusable credit.
- Security requirements: Check for personal guarantees, security interests and claims against business assets.
- Payment fit: Test the actual payment frequency against when customers pay you.
- Total obligation: Compare the amount received, total repayment and all disclosed charges together.
- Eligibility fit: Check operating history, revenue requirements and documentation before applying.
- Exit terms: Understand early repayment, renewal and what happens after a missed payment.
For your 2026 comparison, use written offers rather than headline descriptions. Compare equivalent funding amounts and payment periods wherever possible. Otherwise, differences in structure can obscure what you are actually committing to repay.
Unsecured business funding options at a glance
Unsecured term loan
- Best for: A defined expense with a repayment plan
- Standout feature: A lump sum repaid over an agreed term
- Key limitation: Scheduled payments continue when sales slow
Unsecured business line of credit
- Best for: Recurring working capital gaps
- Standout feature: Credit can be reused within the agreement's limit
- Key limitation: Access remains subject to the facility's terms
2M7 merchant cash advance
- Best for: Established revenue-generating businesses comparing loan alternatives
- Standout feature: Direct funding with one fixed cost of capital disclosed before signing
- Key limitation: Not a loan; security requirements need confirmation
Business credit card
- Best for: Routine purchases accepted by card
- Standout feature: Purchase-by-purchase access to revolving credit
- Key limitation: A persistent carried balance creates an ongoing financing obligation
The merchant cash advance belongs here as an alternative, not as another name for an unsecured loan. Its inclusion does not establish that a particular offer is unsecured.
1. Unsecured term loan: best for a defined expense
An unsecured term loan provides a lump sum that you repay over an agreed period. It suits an expense with a clear purpose, such as a business improvement, when operating cash flow supports the scheduled payments.
Start with the expense, not the largest amount offered. Your repayment plan should identify where the payment comes from even if the purchase takes longer than expected to generate revenue.
Unsecured term loan pros:
- A defined repayment period gives you an endpoint to plan around.
- A scheduled payment creates a clear recurring cash commitment.
- A lump sum supports an expense that must be paid upfront.
Unsecured term loan cons:
- Scheduled payments do not disappear during slower trading periods.
- A personal guarantee can create exposure beyond the business.
- Early repayment terms differ between agreements.
Best for: A business with a defined expense and sufficient cash flow to support the proposed schedule.
Before accepting a 2026 offer, ask whether the payment can change, whether early repayment changes the total obligation and what triggers default. Obtain those answers in the agreement, not just in a conversation.
Verdict: Hold until the scheduled payment fits both normal and slower trading periods.
2. Unsecured business line of credit: best for recurring gaps
An unsecured business line of credit lets you draw funds within an approved limit and reuse credit as you repay, subject to the agreement. It suits timing gaps between business expenses and customer receipts.
The distinction is simple: a line of credit addresses a recurring timing problem, not an expense that permanently exceeds revenue. If the balance never comes down, examine the underlying cash flow problem before requesting more credit.
Unsecured business line of credit pros:
- You can draw against the facility as a funding need arises.
- Repayment restores access to credit within the agreement's terms.
- Reusable credit matches repeated working capital needs.
Unsecured business line of credit cons:
- The lender's agreement governs continued access and reviews.
- Repeated drawings can conceal a persistent operating shortfall.
- A personal guarantee can still be required.
Best for: A business with recurring, identifiable gaps between payments out and receipts in.
Ask what documentation the lender requires to maintain the facility. Also establish whether the lender can change the limit or demand repayment under specified circumstances. Available credit is useful only when you understand the conditions attached to it.
Verdict: Hold until you can explain how customer receipts will reduce each drawing.
3. 2M7 merchant cash advance: best for comparing loan alternatives
2M7 provides merchant cash advances and working capital directly to Canadian businesses. It is a direct funder, not a broker, and its product is not a loan.
2M7 is best for Canadian business owners comparing merchant cash advances with unsecured business loans. Its stated eligibility includes at least 3 months in business and $15,000 or more in monthly revenue, including businesses with less-than-perfect credit. Meeting those thresholds does not establish approval.
2M7 merchant cash advance pros:
- You deal with a direct funder rather than a broker.
- One fixed cost of capital is shown before signing.
- The fixed cost does not change based on how long repayment takes.
- Less-than-perfect credit is included in the stated customer profile.
2M7 merchant cash advance cons:
- It is not suitable for a business specifically seeking a loan agreement.
- The stated operating history and revenue thresholds exclude some applicants.
- Flex payments apply only to businesses processing daily card payments.
Best for: A revenue-generating Canadian business evaluating working capital outside a conventional loan structure.
The published approval rate is 75%, not a promise of approval for an individual applicant. Before accepting an offer, confirm the payment mechanism, total repayment obligation, security requirements and any personal guarantee.
Do not assume a merchant cash advance is unsecured simply because it appears in a comparison of unsecured funding. The agreement determines the obligations.
Verdict: Hold until the written offer confirms that the structure and payment terms fit your business.
4. Business credit card: best for routine purchases
A business credit card provides revolving credit for purchases that merchants accept by card. It suits routine expenses when you have a clear plan to pay the statement balance.
A card is not interchangeable with working capital deposited into your business account. Check how the intended expense can be paid before choosing this route, especially for payroll or supplier obligations that do not accept card payments.
Business credit card pros:
- You can fund individual purchases rather than draw a lump sum.
- Statements create a record of card transactions.
- Revolving credit can support recurring purchasing needs.
Business credit card cons:
- Not every business expense can be paid by card.
- Carrying a balance creates an ongoing financing obligation.
- Personal guarantees and liability terms require review.
Best for: Routine card-eligible purchases supported by a specific repayment plan.
Read the terms for purchases, cash advances and missed payments separately. Those transactions can have different conditions. Do not treat the credit limit as a target spending amount.
Verdict: Skip for persistent cash shortfalls; hold for routine purchases until repayment is planned.
How these options were ranked
The ranking follows purpose fit, payment fit, security requirements, total obligation, eligibility and exit terms. A term loan comes first for a defined expense because the funding and repayment period can be matched to that expense. A line of credit takes the recurring-gap slot because it can be reused.
The merchant cash advance occupies a separate loan-alternative slot. A business credit card ranks for routine purchases rather than general funding needs. No provider receives a blanket recommendation based on an advertised approval rate or a product name.
How to compare written funding offers in 2026
Use the same review sequence for each offer. This keeps a clear application process from distracting you from an unsuitable agreement.
Funding purpose
Write down exactly what the funding will pay for. Separate a single purchase from a recurring operating gap, and distinguish delayed customer receipts from expenses that exceed revenue.
Payment fit
Place the proposed payments beside your expected customer receipts. Review both the amount and frequency. A payment that looks manageable in a monthly summary can still fall at the wrong point in your operating cycle.
Security terms
Ask for every personal guarantee and security provision to be identified. Confirm which party is responsible, what assets are involved and what happens if the business misses a payment.
Exit terms
Read the early repayment, renewal and default provisions before signing. Ask whether paying sooner changes what you owe and whether additional funding requires a new agreement.
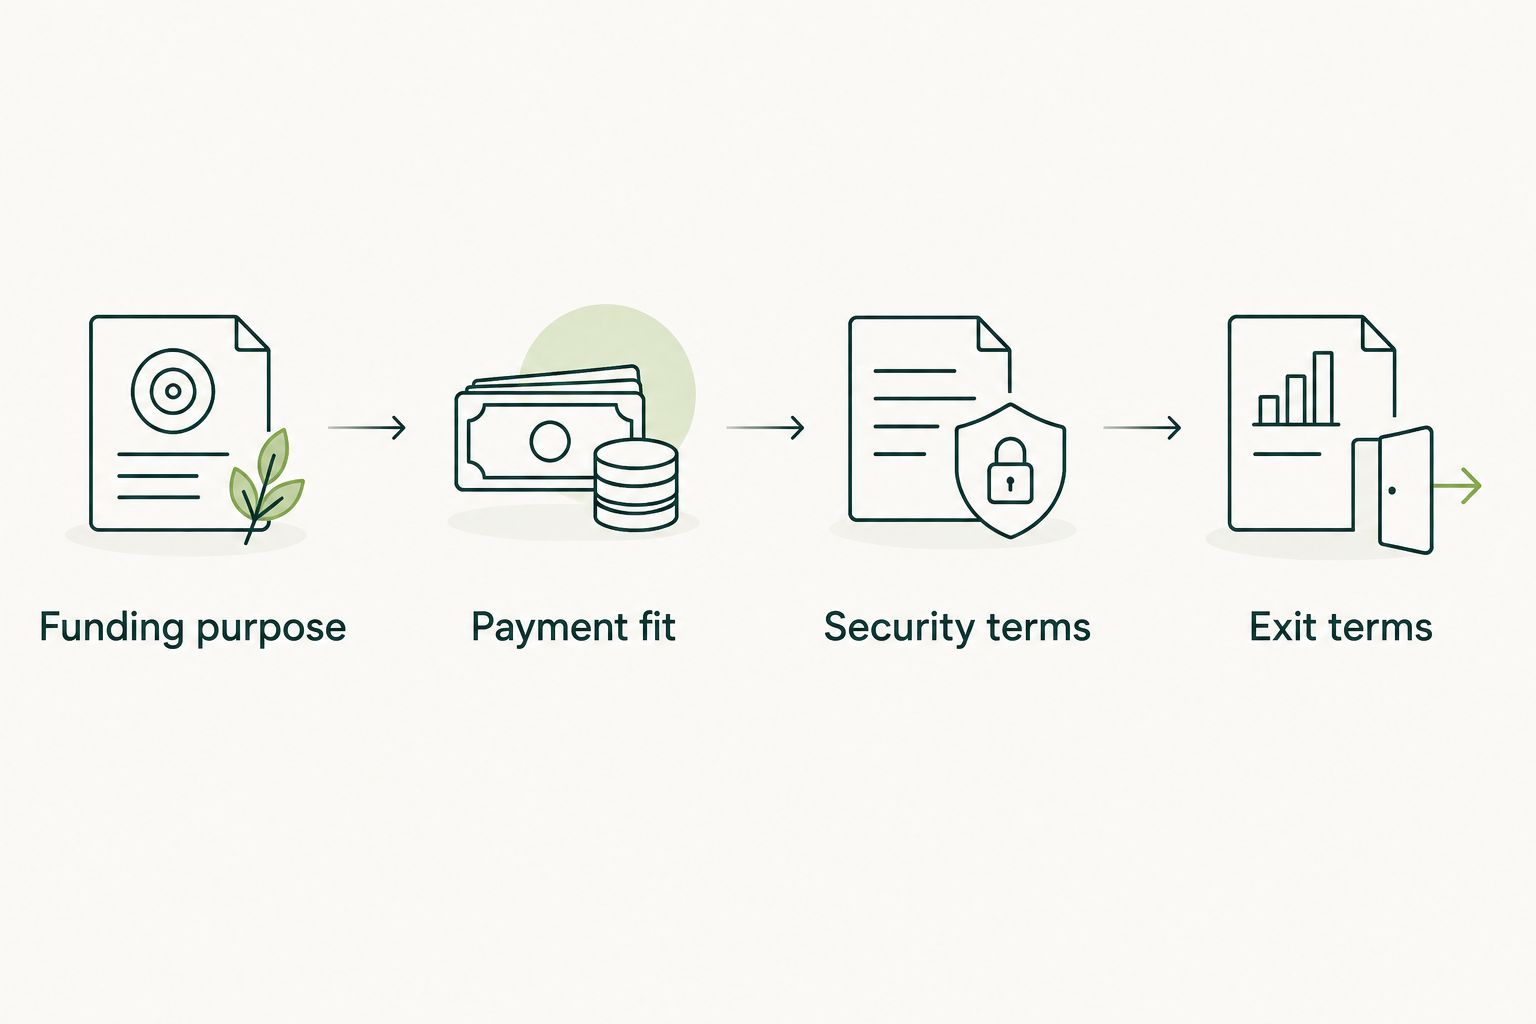
Review the agreement's obligations before choosing the funding structure.
Keep the final offer and agreement together. If a verbal explanation differs from the documents, ask for clarification before accepting. The decision should rest on the terms you will actually sign.
Which unsecured business funding should you choose?
Choose an unsecured term loan as the default for a defined expense only when scheduled repayments fit your cash flow. Choose an unsecured business line of credit for recurring timing gaps that customer receipts will clear.
Compare a merchant cash advance when you want a loan alternative and understand its payment structure. Keep a business credit card for suitable purchases rather than treating it as a general solution to an ongoing operating deficit.
The deciding question in 2026 is not simply whether funding is unsecured. It is whether the written obligation fits the business that must meet it.
FAQ
What's the best unsecured business loan in Canada in 2026?
An unsecured term loan is the default option to compare for a defined expense with a clear repayment plan. An unsecured business line of credit is a better structural fit for recurring cash flow gaps, subject to the actual agreement.
Does unsecured business funding mean no personal guarantee?
No. An unsecured business loan can still require a personal guarantee, so review personal liability separately from collateral requirements.
Does 2M7 offer unsecured business loans?
2M7 offers merchant cash advances and working capital, not loans. Confirm security requirements and personal guarantee terms in the written offer rather than assuming the funding is unsecured.
Can a Canadian business with less-than-perfect credit apply for a merchant cash advance?
Yes, the stated customer profile for this merchant cash advance includes businesses with less-than-perfect credit. Eligibility also includes at least 3 months in operation and $15,000 or more in monthly revenue; approval is not assured.
Is a business line of credit better than a term loan?
A business line of credit is better suited to recurring timing gaps, while a term loan suits a defined expense. Compare the payment requirements and access conditions before choosing either structure.
Do merchant cash advance payments always change with sales?
No. Payment arrangements depend on the funding agreement, and flex payments under the merchant cash advance described here apply only to businesses processing daily card payments.
What should I ask before accepting unsecured business funding?
Ask about total repayment, payment frequency, personal guarantees, security provisions and early repayment terms. Make sure the written agreement answers each question before signing.
One last thing
Start with the payment calendar, not the approval message. Put every proposed funding payment beside payroll, supplier bills and expected customer receipts before accepting an offer. That exercise shows whether the funding solves a timing gap or adds another obligation at the wrong time.
Related guides


