ClickCease

When Is the Right Time to Scale Your Business?

When Is the Right Time to Scale Your Business?

The right time to scale your small business
16
Jun 2026
26
Jul 2026

Scaling feels like the reward you've been working toward. More customers, more revenue, more proof that what you built actually works. But if you've ever stood at the edge of a real growth opportunity and felt a knot in your stomach instead of pure excitement, you're in good company. That tension is not a character flaw. It's the reasonable response of someone who understands that growth costs money before it makes money.

In the current Canadian economic climate, that tension is sharper than ever. The Bank of Canada's key interest rate has shifted multiple times in recent years, and with it, the cost of capital for Canadian businesses. . Supply chains have reminded everyone how quickly operational stability can erode. And yet, demand for goods and services keeps pressing forward. If customers are lining up and you're struggling to keep pace, the question isn't whether to scale. It's whether you're positioned to do it without destabilizing what you've already built.

Clear Signs Your Business Is Ready to Scale

Growth readiness is a specific condition, not just a feeling of momentum. There's a meaningful difference between a business that's having a good month and one that has structurally outgrown its current capacity.

The clearest signal is sustained, predictable demand. Not a spike. Not a strong quarter that could be an outlier. Consistent, repeating customer behavior that your current operations genuinely cannot absorb. If you're turning away work, running out of inventory before the sales cycle closes, or watching your team stretch thin week after week, that's not a temporary crunch. That's the shape of a business that needs more infrastructure.

Other indicators worth taking seriously: your revenue has been stable for at least two to three consecutive quarters, your margins have held up under current volume, and you have a clear picture of where the additional demand would come from after you expand. A retailer who knows their peak seasons and can project inventory needs six months out is in a fundamentally different position than one hoping for a strong run.

For businesses in trucking, the signal is often visible in load acceptance rates and dispatch capacity. If you're consistently declining loads because the fleet can't absorb them, the case for expansion is already written in the data. For retail operators dealing with stockouts during key periods, the problem and the solution are both sitting in your inventory reports.

The Cash Flow Catalyst: Why Business Health Trumps Credit History

Here's where a lot of Canadian business owners hit a wall, or think they will. Scaling requires significant upfront capital. You need to hire before the revenue from those new hires arrives. You need inventory before the sales come in. You need equipment, space, or fleet capacity before the additional contracts are signed. Growth is front-loaded by nature.

Traditional credit evaluation was never designed for this reality. The Government of Canada defines a credit score as a measure of your borrowing history, not the current health of your business. It tells a lender what you did with credit in the past, not whether your business is generating consistent, growing revenue right now.

Alternative lenders approach this differently. They look at your actual bank statements, your revenue trends, and the overall health of your cash flow as the primary signals of creditworthiness. A business generating $30,000 a month in steady, recurring revenue tells a much more relevant story than a credit score that dipped during a difficult period two years ago. When your business is the evidence, the evaluation process looks at what actually matters.

Navigating Growth Funding: The Big 5 Banks vs. Alternative Lenders

Canada's major chartered banks are conservative by design. Their underwriting frameworks require years of audited financials, strong personal credit, collateral, and approval timelines that routinely run several weeks. For a business navigating a time-sensitive growth window, those timelines are the problem. An opportunity to lock in a major contract, secure a lease on the right commercial space, or purchase equipment at a favorable price doesn't wait for a bank's committee review.

This is where a Merchant Cash Advance changes the conversation. Rather than borrowing against assets or credit history, you're accessing capital against your future revenue, with repayment structured as a percentage of daily sales. When business is strong, the advance pays down faster. When things slow, repayment adjusts accordingly. There's no fixed monthly obligation sitting on your books demanding the same number regardless of conditions.

For businesses that need fast business funding to act on a real opportunity, the difference in approval timelines alone can be decisive. Alternative lenders with a clear view of your cash flow can make decisions in hours, not weeks.

Overcoming Credit Anxiety While Growing

A lot of business owners carry a quiet fear into funding conversations: the worry that a past credit blemish will shut the door before it opens. A period of difficulty, a personal financial event, or even just a lean year in the business can leave marks on a credit report that feel permanent.

Alternative underwriting doesn't ignore your credit history entirely, but it also doesn't let it override a compelling current picture. If your business has been generating consistent monthly revenue, if your bank statements show regular deposits and managed obligations, and if you've been operating for at least a few months with real transaction history, there is a path forward. The weight shifts from what happened to you in the past to what your business is doing right now.

If credit anxiety has been keeping you from exploring your options, you can learn more about how Canadian small business owners navigate funding with imperfect credit histories without starting from zero.

Preparing Your Scale-Up Toolkit: Essential Documentation

When you're ready to have a funding conversation, being organized signals that you run your business with intention, and it keeps the process moving. For a Merchant Cash Advance, the documentation requirements are deliberately straightforward:

  • Three to six months of business bank statements
  • A government-issued photo ID
  • A void cheque for direct deposit

That's the core of it. Your bank statements do the heavy lifting, showing lenders your revenue volume, deposit consistency, average balances, and how existing obligations are being managed. Unlike small business loans through traditional institutions, there's no requirement for a formal business plan, years of audited financials, or personal collateral.

Industry risk and the nature of your business model will factor into the conversation, which is worth knowing in advance. Seasonal businesses or those in higher-volatility sectors may face additional questions around cash flow stability. Having a clear, honest picture of your revenue patterns and a straightforward explanation of how you plan to deploy the capital will address most of those concerns before they become objections.

Ready to Map Out Your Next Move?

Scaling is not a decision you should make in a moment of anxiety, but it's also not one you should keep deferring because the financing picture feels unclear. If your business has consistent demand, steady revenue, and a specific plan for what growth would actually look like, the conversation is worth having.

The 2M7 team works with Canadian small business owners at exactly this stage: past survival mode, looking at real opportunity, and trying to find a funding structure that fits how their business actually operates. Reach out directly and let's talk through what your scaling plan could look like.

Related articles

August 19, 2026
September 30, 2026

Preparing Your Business for the Holiday Rush

The fourth quarter makes or breaks a lot of small businesses in Canada. Retailers and restaurants that get their staffing and inventory right in October and November tend to walk into January with healthy cash reserves. Those that wait until the first week of December to figure out their game plan usually spend the season scrambling, and scrambling costs money.

If you own a retail shop, a restaurant, or any business that lives and dies by foot traffic during the holidays, now is the time to lock in your plan. Here's how to think about staffing, stock, and cash flow so the next ten weeks work in your favour instead of against you.

‍

Start With Your Sales History, Not Your Gut

Too many owners plan the holiday season based on how busy last December felt rather than what the numbers actually showed. Pull your point-of-sale reports from the last two or three holiday seasons and look for patterns. Which products sold out early? Which days of the week saw the heaviest traffic? What time of day did your restaurant get slammed?

Analyzing past sales data to spot seasonal patterns is one of the most effective ways to avoid overstocking or running out of popular items. This isn't complicated analysis. Even a basic spreadsheet showing week-over-week sales from last November and December will tell you more than a gut feeling ever will.

For retailers specifically, this is also the moment to think seriously about how much inventory you actually need on hand versus how much cash you're willing to tie up in stock that might not move. If you've been turning down orders because you can't front the cost of holiday inventory, you might want to consider your options before you're forced to choose between restocking and making payroll.

‍

Staffing: The Problem Nobody Talks About Early Enough

Here's a fact that should change how you're thinking about hiring right now. The National Retail Federation recently predicted that holiday seasonal hiring would hit its lowest level in over 15 years, making early recruitment more critical than ever. That forecast is for the American market, but Canadian retailers and restaurants are competing for the same shrinking pool of available seasonal workers, and the labour crunch tends to move north with a short delay.

Practically, this means posting your seasonal job openings now, not in mid-November. It means offering shift flexibility and being upfront about pay. It also means having a real contingency plan if you can't fill every shift you need.

For restaurants, the stakes are a bit different but no less serious. Using past data to anticipate peak times helps restaurants build optimized schedules without over- or under-staffing. A kitchen that's short-staffed on a Friday night in December doesn't just lose sales, it loses customers who won't come back after a bad experience. If your restaurant's equipment is also aging and slowing down your kitchen's throughput during peak hours, that's a separate problem worth solving before the rush hits.

What Canadian Shoppers Are Actually Doing Differently

It's not enough to staff up and stock up the way you did last year. Consumer behaviour is shifting, and ignoring that shift means missing opportunities your competitors will catch. According to Retail Council of Canada's holiday shopping research, Canadian consumers are shopping earlier and comparing prices more carefully than in past years.

That earlier-shopping trend matters because it means your marketing and inventory need to be ready well before Black Friday, not scrambling to catch up to it. If your customers are comparison shopping more aggressively, your pricing, promotions, and in-store or online experience need to justify why they should buy from you instead of clicking over to a competitor's site.

Refreshing your online listings and promoting gift cards are easy, high-impact ways to prepare for the holiday shopping rush. Simple, low-cost moves like updating your Google Business listing, refreshing your website's holiday hours, and pushing gift card sales through email and social media can generate real revenue with almost no upfront cost.

‍

Give Shoppers a Reason to Walk Through Your Door

If customers are comparing prices and shopping online, your store has to earn the trip. Start with the basics: a slow checkout is one of the fastest ways to lose a holiday sale, so add a second register during peak hours and make sure your POS is ready for the volume. Then give people a reason to come in. A coupon, a limited-time discount, or a buy-one-get-one deal can do it. Costco has held its hot dog and soda combo at $1.50 since the mid-1980s because it draws people in, and they usually leave having bought a lot more than lunch.

Finally, walk your shop the way a customer would. A clean storefront, fresh signage, and a seasonal display cost far less than the sales they protect.

‍

Where Fast Funding Fits Into the Picture

Every piece of holiday prep costs money before it generates a dollar back. Inventory has to be purchased before it's sold. Staff have to be hired and trained before they're productive. Equipment repairs have to happen before the kitchen can handle a full house on a Saturday night.

This is where a lot of small business owners hit a wall, particularly if a bank has already turned them down or they don't have the time to wait six weeks for a traditional loan decision. A Merchant Cash Advance is built for exactly this kind of short-term, high-stakes timing problem. Rather than waiting on a lengthy approval process, you're leveraging future sales to access capital now, when you actually need it, not after the holiday window has already closed.

If your credit history isn't perfect, that shouldn't be the reason you miss the busiest quarter of your year. Many alternative lenders look past your credit score and focus on your recent revenue instead of your past setbacks. Fast business funding and small business loans through alternative lenders exist precisely because traditional banks move too slowly and too conservatively for the realities of running a seasonal business. 

Contractors and trades businesses often assume holiday funding conversations don't apply to them, but late Q4 and early Q1 are when many trades see a surge in emergency repair calls and pre-holiday renovation rushes. Having working capital on hand means you can staff up and stock materials without cash flow becoming the bottleneck.

‍

Get Ahead of It Now

Waiting until December to figure out staffing, inventory, and cash flow puts you behind before the season even starts. The businesses that come out of Q4 stronger are the ones making these decisions in October and November, while there's still time to act on them.

If you need capital to hire, stock up, or fix equipment before the rush hits, reach out to 2M7. We move fast, we understand Canadian small business realities, and we can get you funded well before you would have finished filling out bank paperwork.

Read more
March 30, 2021
August 10, 2026

How to Get Business Financing With Poor Credit

If you are looking to grow your business, then you may find it challenging if you have poor credit. However, there are a number of options that can help your business get the financing with poor credit. Here’s a look at the steps you can take to secure fencing for your business with poor credit.

1) Check your credit score

The first thing that you should do is know your credit score. If your credit score is below 700, then your credit will be considered subprime. Also, this can prevent you from the top business financing options. You can credit your credit score for free on Credit Karma. You can also request one credit report, per year, from the two major credit reporting agencies.

2) Know your options

Once you know your credit score, then you can explore your options. In fact, if you have a low credit score, then you will want to consider the following types of financing options:

  • Business credit cards - There are a number of business credit cards that allow customers with subprime credit scores. While these credit cards may have higher interest rates, they will allow your business to get the quick funding that you need.
  • Merchant cash advance - A merchant cash advance is an advance based on the credit card sales deposited into your business’s bank accounts. In short, a merchant cash advance can help you get access to your money faster for a small fee. Many businesses used merchant cash advance to gain faster cash flow.
  • Short-term line of credit - A short-term line of credit allows you to draw from a pool of funds. When you pay back the loan with interest, then you can draw from the line of credit again.

3) Create a business plan

If you are looking to secure a short-term business loan, it is a good idea to have a business plan. After all, the bank will want to know what type of business that you are in and how you intend to generate revenue. A well-organized business plan will increase your chances of being approved for a short-term business loan.

4) Have collateral

If you have any form of collateral, then you can secure a loan much more easily. Here are some types of collateral that can allow you to get the funds that your business needs:

  • Vehicle
  • Property
  • Inventory
  • Unpaid invoices
  • Cash

5) Find a co-singer

Finally, you can find a co-signer that can help you secure a loan or financing with poor credit. A co-signer can be anyone from a member of the family to a business partner. The co-signer should be aware that they are liable for the loan if you don’t pay back the principal or the interest.

Getting your business up and running

Bad credit doesn’t have to stop you from funding your business. At 2M7 Financial Solutions, we do not require a credit score to issue a merchant cash advance. Apply now to get a merchant cash advance today.

Read more
October 19, 2026
October 19, 2026

Best equipment financing for trucking companies in Canada 2026

Best overall for truck ownership: an equipment loan. Best for planned replacement: an equipment lease. Best for recurring repair bills: a business line of credit. Best for equipment-related working capital: a merchant cash advance when its repayment terms fit your revenue. This 2026 guide compares equipment financing for trucking companies by purpose, ownership and cash flow, rather than treating every funding option as interchangeable.

TL;DR

  • Equipment financing for trucking companies starts with a choice: finance the vehicle or fund the business around it.
  • Equipment loans suit ownership; equipment leases suit businesses that prefer use over immediate ownership.
  • Business lines of credit suit recurring operating expenses, subject to approved terms and limits.
  • 2M7 provides merchant cash advances for Canadian businesses seeking equipment-related working capital, not conventional equipment loans.

Why this matters

A truck purchase and a repair-related cash flow gap are different funding problems. A vehicle can support your business for years, while a repair bill needs to be matched against the cash available after the truck returns to work.

Match the funding structure to the expense before comparing providers. Otherwise, you can end up using operating cash for a long-term asset or taking on a repayment schedule that leaves too little room for fuel, insurance and payroll.

2M7 is a Canadian direct funder, not a broker, offering merchant cash advances and working capital. That makes it relevant to equipment-related cash needs, but not interchangeable with a lender financing a specific truck.

What makes the best trucking equipment financing?

Use these criteria to compare your 2026 options before requesting an offer:

  • Funding purpose: Separate buying a truck from paying for repairs, equipment, payroll or a cash flow gap.
  • Ownership: Establish who owns the equipment during the agreement and what happens at the end.
  • Cash flow: Compare payment timing with actual collections, not just the dates you issue invoices.
  • Security: Identify the truck, other assets or guarantees covered by the agreement.
  • Total obligation: Review the complete repayment obligation, charges and end-of-term requirements in writing.
  • Eligibility: Check business history, revenue, credit and equipment requirements before preparing an application.

No option wins every category. A suitable purchase agreement can still be unsuitable for recurring expenses, and an accessible working capital offer can still put pressure on operating cash.

Trucking equipment financing at a glance

Equipment loan

  • Best for: Buying a truck you intend to keep
  • Standout feature: Financing tied to an equipment purchase
  • Key limitation: Security and repayment obligations require close review

Equipment lease

  • Best for: Using equipment with a planned replacement strategy
  • Standout feature: Contract defines equipment use and end-of-term choices
  • Key limitation: Ownership is not automatic

Business line of credit

  • Best for: Recurring repairs and operating expenses
  • Standout feature: Reusable borrowing capacity under the agreement
  • Key limitation: Approval, limits and renewal terms constrain access

Merchant cash advance

  • Best for: Equipment-related working capital supported by business revenue
  • Standout feature: Funding assessed against the operating business
  • Key limitation: It is not a substitute for reviewing truck-specific financing

These are financing structures, not a ranking of named lenders. Actual suitability depends on the written offer, your business finances and the equipment involved.

1. Equipment loan: best for long-term truck ownership

An equipment loan finances an equipment purchase through a lending agreement. For a trucking company buying a vehicle it intends to keep, it is the clearest starting point because the funding decision centres on the asset and the business's ability to repay.

Ask whether the lender accepts the truck's age, condition, seller and intended use. Do not assume an offer for one vehicle applies to another, even when both serve the same route.

Equipment loan pros:

  • Connects the financing request to a defined equipment purchase.
  • Supports an ownership-focused fleet plan.
  • Provides a repayment schedule you can assess against operating cash flow.

Equipment loan cons:

  • Security arrangements can restrict your ability to sell or refinance the truck.
  • Payments continue when the truck is idle or undergoing repairs, unless the agreement provides otherwise.

Best for: An established owner-operator or fleet buying equipment for continued use.

Before accepting an equipment loan in 2026, ask what happens if you sell the truck, repay early or need to replace it after a breakdown. Also confirm whether the agreement covers only the equipment or requires additional security.

Verdict: Buy through an equipment loan when ownership is the goal and the payment leaves room for maintenance and downtime.

2. Equipment lease: best for a planned replacement strategy

An equipment lease gives your business the right to use equipment under a contract. The agreement determines payments, responsibilities and what happens when the lease ends.

A lease belongs on your shortlist when access to the truck matters more than immediate ownership. It requires careful end-of-term planning, not just a comparison of periodic payments.

Equipment lease pros:

  • Separates the decision to use equipment from outright ownership.
  • Can support a defined equipment replacement plan.
  • Establishes contractual choices for the end of the lease.

Equipment lease cons:

  • Returning or purchasing the equipment depends on the specific agreement.
  • Usage, condition and early termination provisions can limit flexibility.

Best for: A trucking company with a clear replacement plan and predictable equipment requirements.

Request the full end-of-term wording before signing. Check for purchase obligations, return conditions and any restrictions that conflict with your intended operation. Do not assume maintenance, insurance or repairs are included simply because the vehicle is leased.

For a 2026 comparison, put the lease's total obligations beside the equipment loan's total obligations. A smaller periodic payment does not establish which agreement is better for your business.

Verdict: Buy into a lease only when its use restrictions and end-of-term terms fit your fleet plan.

3. Business line of credit: best for recurring repair expenses

A business line of credit lets you borrow within an approved limit under the lender's terms. Its main role in trucking is managing recurring operating expenses, rather than replacing a dedicated truck-purchase agreement.

Repairs, parts and maintenance do not always line up with customer collections. A credit line gives you a structure to assess those repeated cash needs without treating each expense as a separate equipment acquisition.

Business line of credit pros:

  • Provides reusable borrowing capacity under the agreement.
  • Supports different operating expenses rather than one named asset.
  • Lets you distinguish short-term cash needs from long-term equipment ownership.

Business line of credit cons:

  • Approved limits and renewal conditions can constrain your plans.
  • A continuously drawn balance can conceal an unresolved operating shortfall.

Best for: A trucking business with recurring expenses and a credible plan to restore available credit from collections.

Check whether the facility is secured, what reporting is required and how repayment works. Ask about the lender's rights to change or demand repayment of the facility; do not assume access remains unchanged indefinitely.

If your plan depends on keeping the line fully drawn, reassess the underlying cash flow. Reusable credit works best when your business can repay drawings, not simply move expenses into a growing balance.

Verdict: Hold off on using a line of credit for a truck purchase unless the written terms and repayment plan support that use.

4. Merchant cash advance: best for equipment-related working capital

A merchant cash advance provides business funding through an agreement distinct from a conventional equipment loan. Consider it when the need extends beyond acquiring a vehicle, such as equipment expenses alongside payroll, inventory or a cash flow gap.

2M7 is best suited to Canadian businesses seeking merchant cash advance working capital, rather than a conventional truck-purchase loan. It serves businesses operating for at least 3 months with $15,000 or more in monthly revenue, including businesses with less-than-perfect credit.

Merchant cash advance pros:

  • Addresses operating-business needs, including equipment-related expenses.
  • Offers an alternative structure to conventional equipment borrowing.
  • Provides a direct-funder option through 2M7, without a broker between the business and funder.

Merchant cash advance cons:

  • It is not an equipment loan and should not be compared as though the contracts are identical.
  • Repayment obligations still need to fit cash flow after essential operating expenses.

Best for: A revenue-generating Canadian business that meets the funder's requirements and needs working capital rather than asset-specific financing.

For 2M7 working capital, the cost structure is one fixed cost of capital shown before signing; it does not change based on how long repayment takes. Review the total obligation and repayment mechanism alongside your other written offers. Flex payments are only for businesses that process daily card payments, so do not assume that feature applies to a trucking operation paid through invoices.

Verdict: Buy into a merchant cash advance only when its business purpose and repayment terms fit your collections.

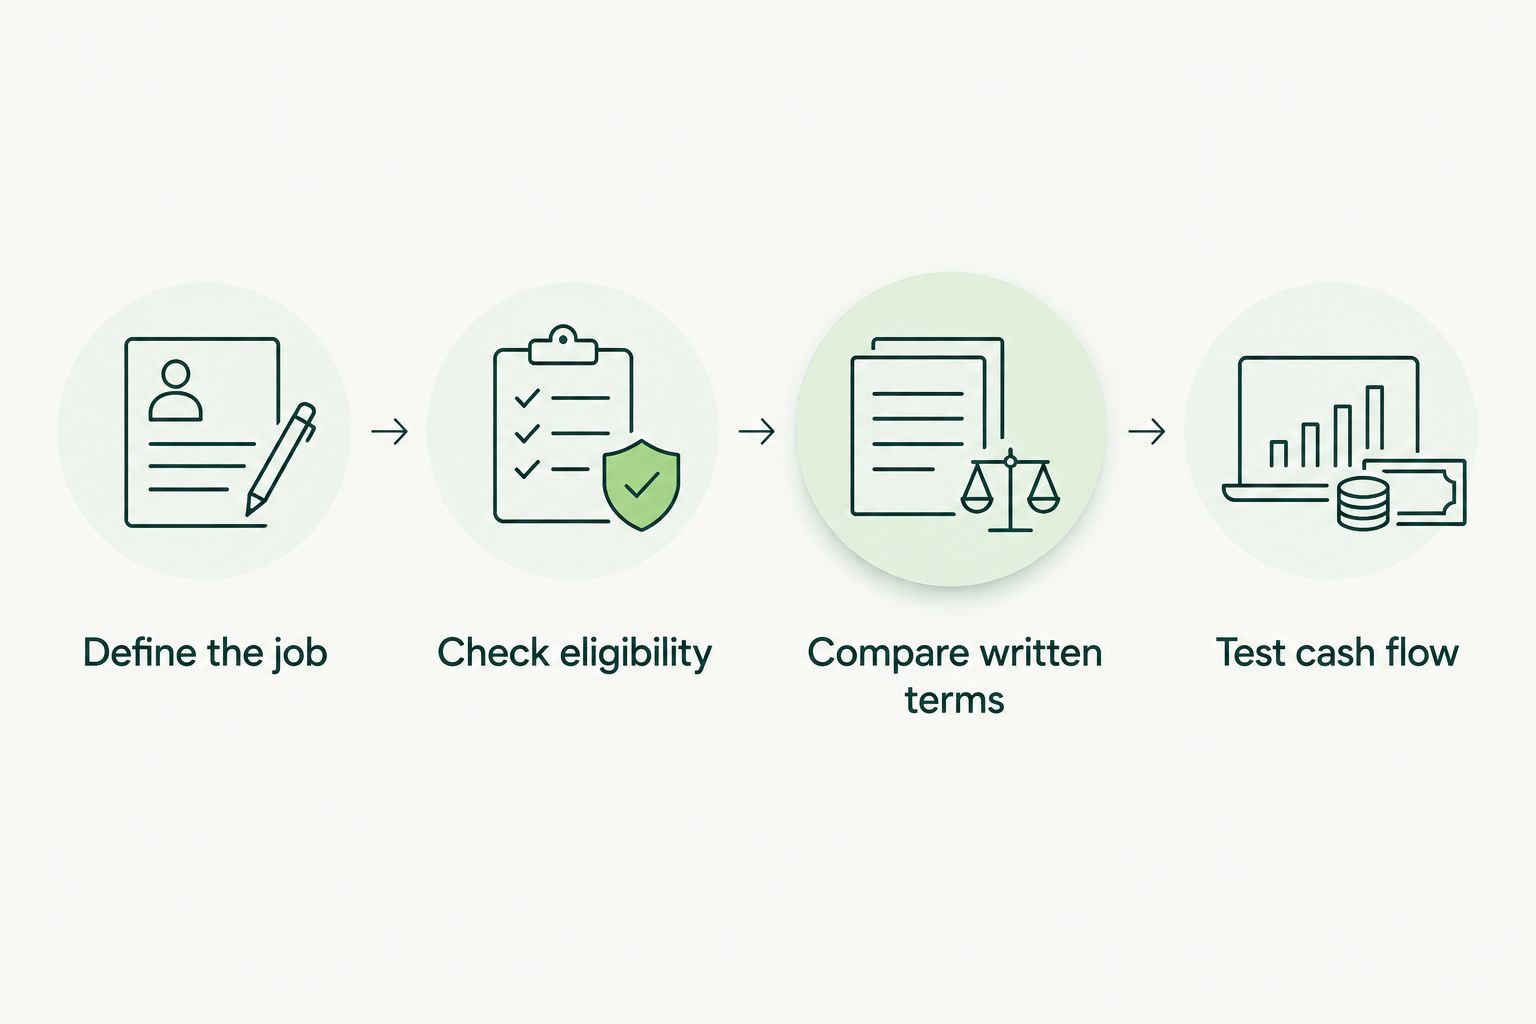
How to compare your written offers

Use the same sequence for every 2026 offer. Comparing unlike figures, such as a lease payment against an advance amount, does not tell you which agreement fits.

  1. Define the job: Write down whether you need a truck, a repair, replacement equipment or operating cash. Separate expenses that serve different purposes.
  2. Check eligibility: Confirm business, revenue, credit and equipment requirements before committing to an application process.
  3. Compare written terms: Record the amount provided, total obligation, payment timing, security, guarantees and exit conditions.
  4. Test cash flow: Place repayments beside expected collections and essential expenses. Check what happens during downtime or delayed customer payments.

A workable offer leaves your business able to operate the truck after obtaining the funding. Approval alone does not answer that question.

Four steps for comparing trucking equipment funding offers

Start with the expense and finish by testing the repayment against operating cash flow.

How the options are ranked

The ranking follows funding purpose, ownership, cash flow, security, total obligation and eligibility. Equipment loans lead for ownership; leases serve planned use and replacement; credit lines address recurring expenses; merchant cash advances address operating-business funding needs.

This is a purpose-based buying guide, not a claim that one provider offers the lowest cost or approves every trucking business. Compare the actual contracts before choosing.

Which equipment financing should you choose?

Start with an equipment loan if you are buying a truck you intend to keep. Compare a lease when your priority is equipment use with a defined replacement plan.

Choose a business line of credit for recurring expenses only when you can explain how collections will repay drawings. Consider a merchant cash advance when the need is working capital and the agreement fits your revenue.

For your 2026 decision, keep the truck purchase and the operating reserve separate on paper. You need to know both how you will acquire the equipment and how you will keep it earning.

Discuss your funding options

Speak with a funding specialist about working capital for your Canadian business.

Discuss funding options

FAQ

What's the best equipment financing for trucking companies in Canada?

An equipment loan is the strongest starting point when your goal is to buy and keep a truck. Compare a lease for planned equipment use, a credit line for recurring expenses and a merchant cash advance for working capital needs.

Is leasing a truck better than financing a purchase?

Leasing is better suited to a use-and-replacement plan, while an equipment loan suits an ownership plan. Compare total obligations, return conditions, security and early exit terms before choosing.

Can I use working capital for truck equipment?

Working capital can support equipment-related business expenses when the funding agreement permits the use. Separate the equipment expense from ongoing payroll, fuel and maintenance so you can assess the full cash requirement.

Does 2M7 offer conventional equipment loans?

2M7 provides merchant cash advances and working capital, not conventional equipment loans. It is a Canadian direct funder, not a broker.

Can a newer trucking business qualify for a merchant cash advance?

The stated eligibility baseline is at least 3 months in business and $15,000 or more in monthly revenue. Meeting that baseline does not establish approval or the terms of an offer.

What should I check before signing a trucking finance agreement?

Check the total obligation, payment timing, security, guarantees and early exit terms. For leases, also check equipment return conditions and any purchase requirements.

Do flexible payments apply if customers pay trucking invoices?

Do not assume flexible payments apply to invoice-based collections. The flex-payment feature described here is only for businesses that process daily card payments.

One last thing

The truck payment is not the truck's full cash requirement. Before signing, put fuel, insurance, maintenance, payroll and a downtime allowance beside the proposed repayment. An agreement that fits only while every invoice arrives on time does not leave your business room to handle disruption.

Related guides

Read more