


Best overall for a defined investment: a bank term loan. Best for recurring cash-flow gaps: a business line of credit. Best for government-backed borrowing: the Canada Small Business Financing Program. This 2M7 guide to small business loans Canada compares six financing routes for 2026 and explains which repayment structure fits your business.
TL;DR
- The 2M7 small business loans Canada guide recommends matching business financing to the expense and repayment source.
- Bank term loans suit defined investments; business lines of credit suit recurring cash-flow gaps.
- The Canada Small Business Financing Program shares lender risk; it does not guarantee approval.
- Invoice financing suits unpaid business invoices; equipment financing ties borrowing to a specific asset.
Why this matters
The best business financing matches the expense to the repayment source. A loan for equipment and a facility for payroll between customer payments solve different problems. Choosing by the amount offered ignores that distinction.
For your 2026 shortlist, compare what happens after the money arrives: when payments begin, what secures the borrowing, and which cash receipts will repay it. A facility that funds the purchase but strains ordinary operations is the wrong fit.
Use 2M7 as your starting point for this comparison, then assess each financing proposal against the same criteria. The ranking below separates financing structures rather than pretending one lender is best for every Canadian business.
What makes the best small business loans in Canada
- Purpose fit: Match the financing to equipment, expansion, working capital, or an unpaid invoice. Confirm that the proposed use is eligible.
- Repayment fit: Compare payment dates with customer receipts. Scheduled instalments and revolving borrowing serve different needs.
- Total repayment: Request the complete repayment obligation, including interest and applicable fees. A headline rate does not describe the whole agreement.
- Security exposure: Identify collateral, guarantees, and obligations that survive a business closure. Read the agreement rather than relying on a summary.
- Eligibility fit: Check revenue, operating history, documentation, and program restrictions before preparing an application.
- Flexibility: Examine redraw access, early repayment terms, renewal conditions, and any restrictions on how funds are used.
Canadian business financing at a glance
Bank term loan
- Best for: A defined investment with predictable repayments
- Standout feature: Scheduled repayment of a lump-sum advance
- Key limitation: Payments remain due when sales weaken
Business line of credit
- Best for: Recurring working-capital gaps
- Standout feature: Borrowing and repayment within an approved limit
- Key limitation: Access depends on the facility's continuing terms
Canada Small Business Financing Program
- Best for: Eligible spending under a government-backed program
- Standout feature: Government shares lender risk
- Key limitation: The participating lender still decides approval
BDC business financing
- Best for: Development projects requiring a dedicated financing discussion
- Standout feature: Canada's business development bank
- Key limitation: Product eligibility and underwriting still apply
Invoice financing
- Best for: Cash tied up in unpaid business invoices
- Standout feature: Financing linked to receivables
- Key limitation: Customer disputes and invoice eligibility matter
Equipment financing
- Best for: A specific equipment purchase
- Standout feature: Financing tied to the financed asset
- Key limitation: It does not solve unrelated operating gaps
1. Bank term loan: best for a defined business investment
A bank term loan advances a lump sum that you repay under an agreed schedule. It fits a project with a clear scope and a repayment source you can explain, such as an expansion supported by existing operating cash flow.
Bank term loan pros:
- Scheduled payments support cash-flow planning.
- A defined advance fits a clearly budgeted project.
- Repayment reduces the outstanding principal over the term.
Bank term loan cons:
- Payments remain due even when revenue falls.
- Collateral or personal guarantees can expose assets beyond the project.
Best for: An established business funding a defined investment rather than repeatedly covering operating shortfalls.
For a 2026 application, connect the project budget to a cash-flow forecast. Separate expected project income from cash your business already generates; the lender needs a repayment case, not just an attractive expansion idea.
Ask whether early repayment changes your obligations and whether the agreement restricts additional borrowing. Those details matter if you expect to refinance, sell an asset, or repay ahead of schedule.
Verdict — Buy: Choose a bank term loan when the investment is defined and scheduled repayments fit your operating cash flow.
2. Business line of credit: best for recurring cash-flow gaps
A business line of credit lets you borrow, repay, and borrow again within an approved limit, subject to its terms. It suits timing differences between expenses and customer receipts rather than a permanent operating loss.
Business line of credit pros:
- Revolving access fits recurring working-capital needs.
- You can draw funds as expenses arise.
- Customer receipts can reduce the outstanding balance.
Business line of credit cons:
- Renewal and access depend on the agreement and lender review.
- A balance that never declines can conceal a structural cash-flow problem.
Best for: A business with recurring payment gaps and identifiable incoming receipts.
Map the gap before applying: when do wages, suppliers, and taxes fall due, and when do customers pay? The borrowing need is the difference between those dates, not simply the largest limit available.
Check whether the facility is repayable on demand and what reporting the lender requires. Do not assume a revolving facility provides permanent access under unchanged conditions.
Verdict — Buy: Choose a business line of credit for temporary, recurring gaps that customer receipts will clear.
3. Canada Small Business Financing Program: best for eligible borrowing
The Canada Small Business Financing Program, administered by Innovation, Science and Economic Development Canada, shares lending risk with participating financial institutions. You apply through a participating lender, which assesses the application and makes the lending decision.
For your 2026 comparison, the program's published limits include $1 million in term loans and $150,000 in lines of credit per eligible borrower. Its eligibility framework covers qualifying Canadian small businesses with gross annual revenue of $10 million or less; farming businesses are excluded and have a separate federal financing program.
Canada Small Business Financing Program pros:
- Government risk-sharing supports participating lenders' eligible lending.
- The program covers specified business financing purposes.
- Published rules give you an eligibility framework to check before applying.
Canada Small Business Financing Program cons:
- Government backing does not guarantee approval.
- Eligible-use rules and category sublimits restrict how borrowing can be allocated.
Best for: A qualifying business whose planned spending fits the program's rules.
The overall term-loan limit is not a spending allowance for every expense category. Ask the lender to identify the applicable sublimits, eligible costs, documentation, and security requirements for your project.
Treat the program as a route to discuss with a lender, not as a government grant. Your business remains responsible for repayment under the financing agreement.
Verdict — Buy: Consider the Canada Small Business Financing Program when both your business and intended spending meet its eligibility rules.
4. BDC business financing: best for a development-focused discussion
BDC is Canada's business development bank and offers business financing. It belongs on your shortlist when you need to discuss a development project and compare the available financing structure with conventional bank borrowing.
BDC business financing pros:
- Its mandate focuses on Canadian businesses.
- You can discuss financing against a specific development objective.
- A proposal provides another structure to compare with other lenders.
BDC business financing cons:
- Eligibility and approval depend on the financing product and application.
- A development mandate does not remove repayment obligations or underwriting.
Best for: A business preparing a defined development project and seeking another financing proposal to evaluate.
Describe the project before asking which product fits. Your plan should distinguish the purchase or expansion itself from the working capital needed to operate during implementation.
For a 2026 comparison, assess the actual BDC proposal rather than assuming public ownership makes it the default choice. Compare repayment timing, security, permitted uses, and early repayment terms with your other offers.
Verdict — Hold: Keep BDC on the shortlist until a specific proposal demonstrates a better fit for your project.
5. Invoice financing: best for unpaid business invoices
Invoice financing converts eligible receivables into access to funds before customers pay. Structures differ: a lender can advance funds against invoices, while factoring involves selling receivables under an agreement.
Invoice financing pros:
- Funding is linked to invoices already issued.
- It addresses the gap between invoicing and collection.
- Receivables provide a defined transaction to assess.
Invoice financing cons:
- Disputed or ineligible invoices can limit access.
- Collection arrangements and responsibility for non-payment vary by contract.
Best for: A business with eligible unpaid commercial invoices and a collection-timing problem.
Read who contacts the customer, where payments go, and who bears the loss if the customer does not pay. Recourse and non-recourse arrangements are not interchangeable, and exclusions still matter.
Invoice financing does not fix a weak margin or create a sale that has not happened. If your cash shortage exists before you deliver and invoice, compare another structure instead.
Verdict — Buy: Choose invoice financing when unpaid eligible invoices, rather than missing sales, explain the cash gap.
6. Equipment financing: best for a specific asset purchase
Equipment financing ties borrowing to a particular asset, which commonly serves as security. Compare an equipment loan with a lease separately because ownership, end-of-term options, and contract obligations differ.
Equipment financing pros:
- The financing purpose is clearly defined.
- Repayment can be assessed against the asset's business use.
- Asset-linked financing keeps the equipment decision separate from general working capital.
Equipment financing cons:
- The financed asset can be at risk if you default.
- Contract restrictions can complicate selling or replacing the equipment.
Best for: A business buying equipment with a clear operating purpose and a repayment plan.
Account for installation, training, maintenance, and the period before the equipment contributes to operations. Financing the purchase does not automatically fund those related expenses.
Ask what happens if the asset becomes unsuitable before the agreement ends. Replacement flexibility matters when your capacity needs or production methods change.
Verdict — Buy: Choose equipment financing for the asset itself, not as a substitute for an operating cash buffer.
How this ranking works
The 2M7 small business loans Canada ranking prioritizes purpose, repayment fit, security, eligibility, and flexibility. Each option owns a different use case; the order is not a lender service rating or an approval forecast.
A bank term loan is the default for a defined investment. The other routes become stronger choices when your financing need is revolving, program-eligible, development-focused, invoice-linked, or asset-specific.
Which small business financing should you choose?
Choose the structure before choosing the provider. For your 2026 decision, write down these four items and use them to compare proposals:
- Funding purpose: State exactly what the money will pay for.
- Repayment source: Identify the receipts that will repay the borrowing.
- Security exposure: List the assets and guarantees required.
- Contract terms: Check payment dates, restrictions, renewal, and early repayment.
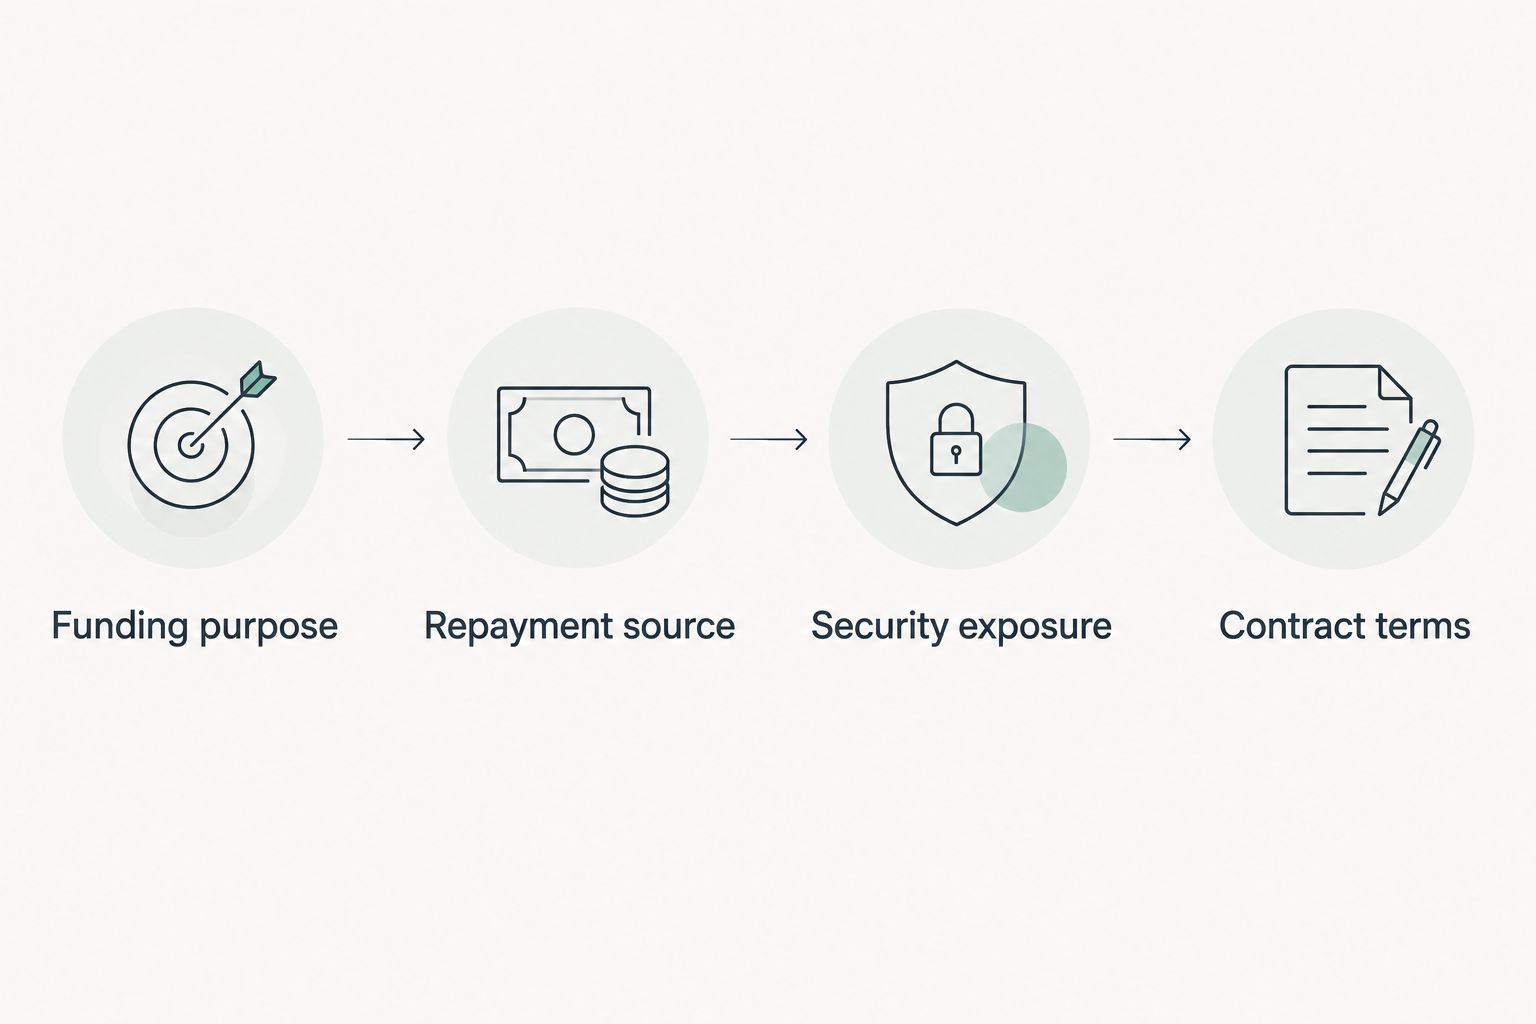
Choose the financing structure before comparing providers.
If you remain undecided, start with a bank term loan for a defined investment or a line of credit for a recurring timing gap. Then compare the alternatives only where their distinct use case matches your business.
Do not accept more borrowing simply because it is offered. Select the amount supported by your documented need and a repayment plan that leaves ordinary operations funded.
FAQ
What's the best small business loan in Canada in 2026?
A bank term loan is the default choice for a defined investment with predictable repayments. A business line of credit fits recurring cash-flow gaps better, while invoice financing and equipment financing address narrower needs.
Is the Canada Small Business Financing Program a government loan?
The Canada Small Business Financing Program provides government risk-sharing for eligible loans made by participating financial institutions. You apply through a participating lender, and that lender decides whether to approve the application.
How much can I borrow through the Canada Small Business Financing Program?
The program's published limits include $1 million in term loans and $150,000 in lines of credit per eligible borrower. Category sublimits and eligible-use rules apply, so the overall limit is not available for every type of expense.
Is a business line of credit better than a term loan?
A business line of credit is better suited to recurring timing gaps, while a term loan fits a defined investment. Compare renewal conditions and repayment obligations before deciding which structure matches your receipts.
Is BDC financing automatically easier to get than a bank loan?
BDC financing still requires product eligibility and application assessment. Compare a specific proposal rather than assuming that BDC's public mandate guarantees approval.
Can invoice financing help before I make a sale?
Invoice financing relies on eligible receivables, so it does not fund a sale that has not produced an eligible invoice. It addresses the timing gap between invoicing and collection.
What should I compare when using the 2M7 business financing guide?
Compare funding purpose, repayment source, security exposure, and contract terms. Those checks distinguish an appropriate financing structure from an offer that merely provides the requested amount.
One last thing
Ask what happens when your repayment source arrives late. A delayed customer payment tests a financing agreement more clearly than an optimistic forecast.
Before signing, trace that delay through payment obligations, available cash, collateral, and guarantees. If the agreement forces another borrowing decision just to meet the first obligation, revisit the structure—not just the lender.


