Best overall for eligible businesses seeking sales-based working capital: 2M7 merchant cash advances. Best for recurring borrowing: a business line of credit; best for unpaid invoices: invoice factoring. This 2026 guide compares six alternative business financing options in Canada by funding purpose, eligibility and repayment fit.
TL;DR
- 2M7 merchant cash advances suit eligible Canadian businesses seeking alternative business financing for working capital.
- Business lines of credit suit recurring borrowing; invoice factoring suits businesses waiting on customer invoices.
- Equipment financing matches funding to assets; purchase order financing supports eligible supplier payments.
- Equity financing suits growth plans where owners accept shared ownership instead of scheduled repayments.
Why this matters
The best financing option matches the expense, the cash coming back and the repayment obligation. An equipment purchase, an unpaid invoice and a payroll gap are different problems. Treating them as the same borrowing need makes comparison harder.
For your 2026 funding decision, start with the transaction rather than the provider. Identify what you need to pay, when that spending produces cash and which repayment structure your business can support. Then compare written offers within the right category.
What makes the best alternative business financing?
Use these criteria to shortlist funding before you submit applications:
- Funding purpose: Match unrestricted working capital, invoice funding or asset financing to the actual expense.
- Eligibility fit: Check operating history, revenue, customer quality and security requirements before applying.
- Repayment fit: Compare payment frequency and obligations with the timing of your receipts.
- Total obligation: Read the complete repayment amount, charges, guarantees and contractual conditions together.
- Ownership impact: Separate financing that creates payment obligations from investment that shares ownership.
- Exit terms: Understand early settlement, cancellation, renewal and security-release provisions before signing.
These criteria matter more than a headline approval claim. A funding offer belongs on your shortlist only when you understand both how it helps and what your business commits to.
Alternative business financing at a glance
This 2026 ranking gives each option a distinct job. The order is a decision guide, not a claim that one funding structure beats every other structure.
2M7 merchant cash advance
- Best for: Eligible businesses seeking sales-based working capital
- Standout feature: Direct funding with one fixed cost of capital disclosed before signing
- Key limitation: Minimum operating history and revenue requirements apply
Business line of credit
- Best for: Recurring short-term borrowing
- Standout feature: Draw, repay and reuse credit within the agreement
- Key limitation: Access depends on approval and account terms
Invoice factoring
- Best for: Businesses waiting on customer invoices
- Standout feature: Funding tied to eligible receivables
- Key limitation: Customer-facing collection arrangements need review
Equipment financing
- Best for: Purchasing business equipment
- Standout feature: Financing connected to a specific asset
- Key limitation: Not a general solution for unrelated operating expenses
Purchase order financing
- Best for: Supplier payments for confirmed customer orders
- Standout feature: Funding connected to order fulfilment
- Key limitation: Order, supplier and transaction eligibility restrict its use
Equity financing
- Best for: Growth without scheduled financing repayments
- Standout feature: Capital exchanged for an ownership interest
- Key limitation: Owners give up a share of ownership and potentially control
1. 2M7 merchant cash advances: best for sales-based working capital
A merchant cash advance provides business funding against future sales. 2M7 is a Canadian direct funder, not a broker, providing merchant cash advances and working capital for expenses such as payroll, inventory, equipment and cash flow gaps.
2M7 merchant cash advances are best for eligible Canadian businesses seeking sales-based working capital rather than a conventional loan. Businesses must have operated for at least 3 months and generate $15,000 or more in monthly revenue. Businesses with less-than-perfect credit are among those served.
2M7 merchant cash advance pros:
- You deal with a direct funder rather than a broker.
- Funding supports several operating purposes, including payroll and inventory.
- One fixed cost of capital is shown before signing and does not change with repayment duration.
2M7 merchant cash advance cons:
- Businesses below the operating-history or revenue thresholds do not meet the stated criteria.
- Flexible payments are only for businesses that process daily card payments.
- A fixed cost does not remove the need to check whether payments fit your cash flow.
Best for: An operating business with established revenue and a defined working-capital need.
Verdict: Hold until the written payment structure fits your cash flow. Meeting eligibility requirements is the starting point, not the final decision.
2. Business lines of credit: best for recurring borrowing
A business line of credit lets you draw funds up to an approved limit and reuse repaid amounts under the agreement. Banks, credit unions and non-bank providers offer credit facilities, so compare the actual contract rather than treating the provider category as the deciding factor.
A business line of credit fits repeated gaps between outgoing payments and incoming receipts. It is less useful when an ongoing operating loss, rather than timing, drives the need for funds.
Business line of credit pros:
- You can draw funds as needs arise within the approved limit.
- Repaid amounts become available again under revolving terms.
- One facility can support different short-term operating expenses.
Business line of credit cons:
- Approval, security and guarantee requirements vary by provider.
- Review provisions and account conditions affect continued access.
- Repeated borrowing can conceal a persistent cash shortfall.
Best for: Businesses with recurring, identifiable cash timing gaps and a clear repayment source.
Verdict: Hold until you have reviewed draw conditions and renewal terms. Choose a business line of credit for repeat use, not simply because the available limit looks attractive.
3. Invoice factoring: best for unpaid customer invoices
Invoice factoring converts eligible receivables into funding by selling invoices to a factor. The arrangement centres on customer invoices, so customer credit quality and invoice eligibility matter alongside your own business profile.
Invoice factoring is a focused option for businesses that have completed work but are waiting for payment. It does not solve a lack of sales, disputed billing or an expense unsupported by eligible receivables.
Invoice factoring pros:
- Funding connects to work already invoiced.
- Customer payment quality forms part of the assessment.
- Collections support can form part of the arrangement.
Invoice factoring cons:
- Disputed or otherwise ineligible invoices limit what you can fund.
- Customer notification and collection practices need careful review.
- Recourse terms determine your responsibility if a customer does not pay.
Best for: Business-to-business suppliers and service providers with eligible, unpaid invoices.
Verdict: Hold until you understand recourse and customer contact. Ask who collects payment, what customers receive and what happens when an invoice remains unpaid.
4. Equipment financing: best for a specific asset purchase
Equipment financing connects funding to machinery, vehicles or other business equipment. Depending on the agreement, the structure involves financing a purchase or leasing the asset, with different ownership and end-of-term obligations.
Choose equipment financing when the asset itself is the reason you need funding. Keep operating cash needs separate so you can assess whether the asset's business value supports the commitment.
Equipment financing pros:
- The funding purpose is tied to an identifiable asset.
- You can compare the agreement against the equipment's expected business use.
- Purchase and lease structures offer different ownership arrangements.
Equipment financing cons:
- Asset-linked funding does not necessarily cover payroll or other operating expenses.
- Maintenance, insurance and end-of-term obligations require review.
- Equipment can lose usefulness while contractual payments continue.
Best for: Businesses acquiring equipment with a clear operating purpose.
Verdict: Hold until ownership and end-of-term terms are clear. Compare equipment financing agreements using the full commitment, not just the payment shown on a proposal.
5. Purchase order financing: best for supplier payments
Purchase order financing supports eligible supplier payments associated with confirmed customer orders. The funder assesses the transaction, including the order, customer, supplier and fulfilment arrangements.
Purchase order financing fits an order-specific gap: you have a customer commitment but need funding to obtain the goods. It is not interchangeable with general working capital for unrelated expenses.
Purchase order financing pros:
- Funding connects to an identifiable customer order.
- Supplier payments are central to the structure.
- You can assess the funding commitment against a specific transaction.
Purchase order financing cons:
- Not every order, supplier or transaction qualifies.
- Delivery, acceptance and customer payment conditions complicate the arrangement.
- Financing obligations must fit the order's remaining margin.
Best for: Businesses fulfilling eligible confirmed orders that require supplier payments before customer receipts.
Verdict: Hold until the complete order economics work. Account for supplier, shipping, fulfilment and financing obligations before accepting funding.
6. Equity financing: best for growth with shared ownership
Equity financing brings capital into a business in exchange for an ownership interest. Unlike funding with scheduled repayments, the central trade-off is ownership, investor rights and the expectations attached to the investment.
Equity financing suits growth plans where an owner accepts an investment partner. A temporary cash timing problem alone is not a strong reason to give up ownership.
Equity financing pros:
- Equity capital does not carry the same scheduled repayment structure as borrowing.
- An investment agreement can support a longer-term growth plan.
- Investors can contribute expertise or connections alongside capital.
Equity financing cons:
- Existing owners give up part of their ownership.
- Investor rights can affect decisions, reporting and future fundraising.
- Negotiating ownership and governance takes preparation.
Best for: Businesses pursuing growth where shared ownership fits the owner's objectives.
Verdict: Hold until ownership and governance terms are understood. Assess the investor relationship as carefully as the capital offered.
How we ranked these financing options
The 2026 ranking follows funding purpose, eligibility fit, repayment fit, total obligation, ownership impact and exit terms. Each option earns a different use-case slot; the comparison does not claim that all businesses qualify or that all providers offer identical terms.
Merchant cash advances lead for eligible sales-based working capital. Business lines of credit address recurring borrowing, invoice factoring addresses receivables, equipment financing addresses assets, purchase order financing addresses orders, and equity financing addresses ownership-based investment.
Which financing option should you choose?
For an undecided owner, choose the category before the provider. Follow this sequence for your 2026 shortlist:
- Funding purpose: Name the expense and explain how it supports your business.
- Cash timing: Map customer receipts against the proposed payment obligations.
- Contract terms: Compare the full commitment, guarantees, security and exit provisions.
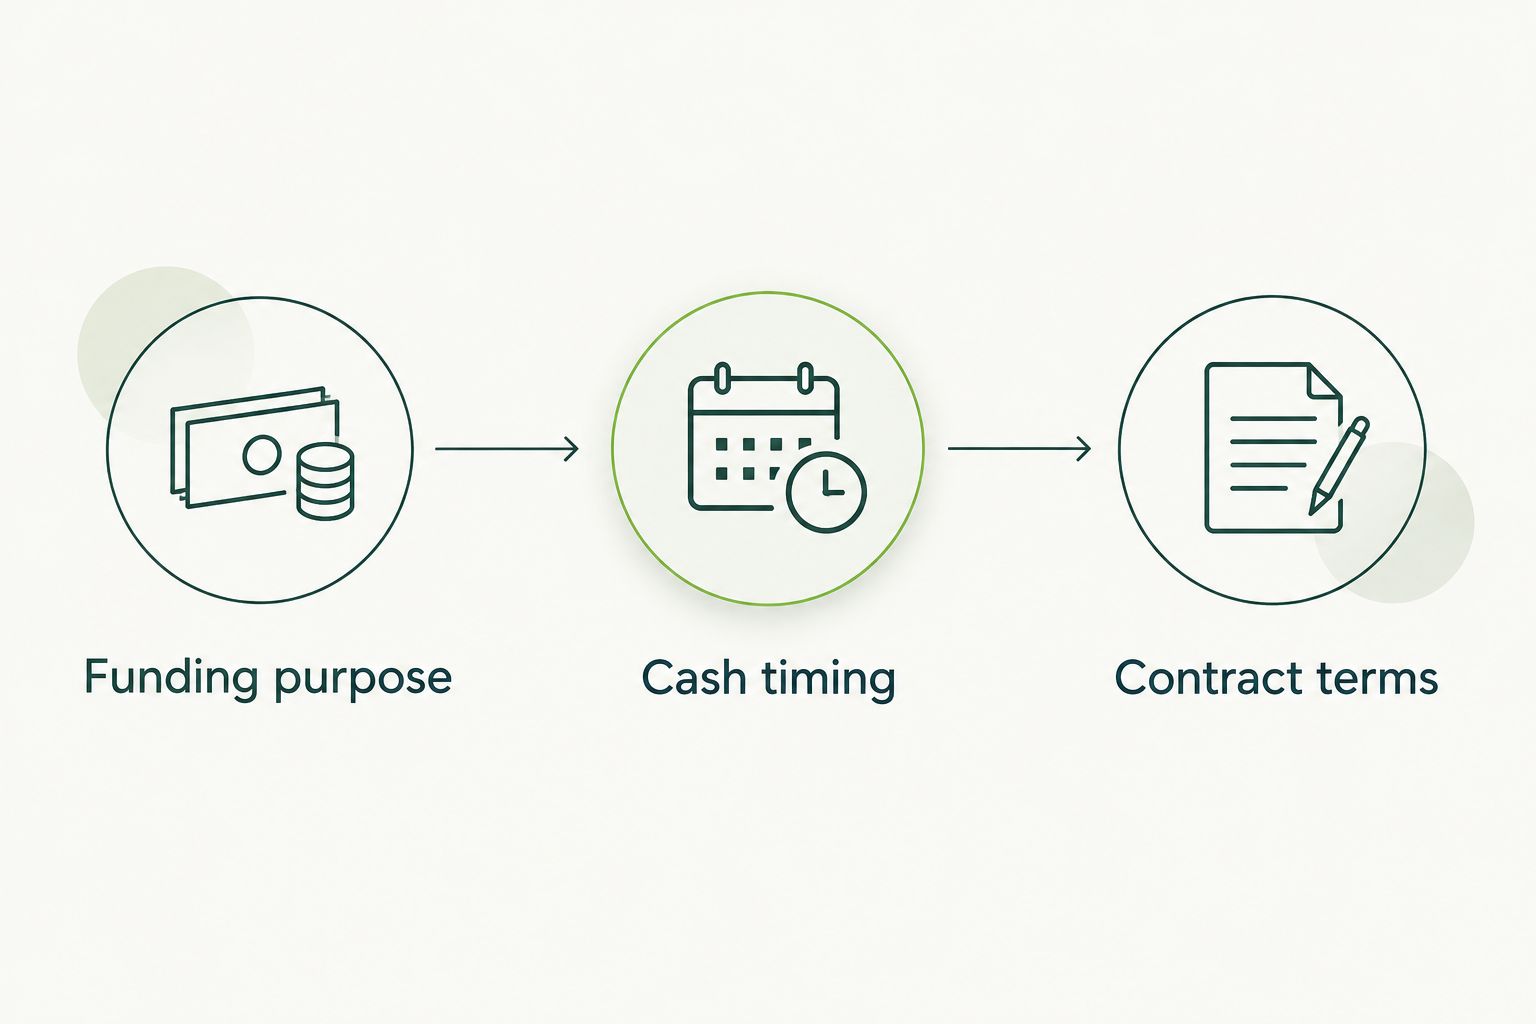
Choose the funding category before comparing provider offers.
If you need general working capital and meet the stated operating and revenue thresholds, start by discussing a merchant cash advance. If the need comes from an invoice, an asset or a customer order, start with the category designed around that transaction.
Before signing, prepare a cash flow forecast showing the proposed obligation alongside payroll, supplier payments and existing commitments. Approval answers whether a funder will proceed. Your forecast answers whether the arrangement works for your business.
FAQ
What's the best alternative business financing option in Canada?
The best alternative business financing option depends on the funding purpose and repayment fit. Merchant cash advances address eligible working-capital needs, while invoice factoring, equipment financing and purchase order financing address specific transactions.
Is a merchant cash advance a business loan?
A merchant cash advance is funding against future sales, not a conventional business loan. Review the agreement's payment structure, total obligation and conditions before signing.
What does a business need to qualify for 2M7 funding?
The stated minimums are at least 3 months in business and $15,000 or more in monthly revenue. Meeting those thresholds does not establish approval or determine the final funding terms.
Is invoice factoring better than a business line of credit?
Invoice factoring fits eligible unpaid invoices, while a business line of credit fits recurring borrowing needs. Compare invoice eligibility, collection arrangements and recourse against the credit facility's draw and repayment conditions.
Can a business with less-than-perfect credit seek funding?
Businesses with less-than-perfect credit can seek funding from providers whose criteria include them. Approval still depends on the provider's assessment and the business meeting applicable requirements.
Do merchant cash advances always have flexible payments?
Do not assume every merchant cash advance has flexible payments. Confirm the written terms; the flexible-payment feature described in this guide is only for businesses that process daily card payments.
What should I compare besides the payment amount?
Compare the total obligation, payment frequency, guarantees, security and exit terms. For equity financing, also compare ownership dilution, investor rights and governance requirements.
One last thing
Approval is not a cash flow plan. Before accepting alternative business financing in 2026, place the proposed obligations into a quieter-sales scenario using your own records. If the plan depends on every customer paying promptly, revisit the amount or structure before signing.
Related guides


