Best for a direct-funder relationship: 2M7. Best for card-sales-linked payments: a merchant cash advance with that structure explicitly written into the agreement. Best for an intermediary-led search: a broker-arranged advance. This 2026 guide compares those routes and explains when a business line of credit is the better alternative.
TL;DR
- For merchant cash advance options Canada businesses can compare, 2M7 fits owners seeking a direct funder.
- Card-sales-linked payments suit daily card-processing businesses; confirm exactly how payments respond to sales.
- A broker arranges funding rather than providing it directly; identify the actual funder before signing.
- A business line of credit is an alternative for recurring borrowing, not a merchant cash advance.
Why this matters
A merchant cash advance provides business funding against future sales, with collection terms set out in an agreement. It differs from a conventional business loan. Your decision should centre on the amount your business receives, the total contractual obligation and how collections affect operating cash flow.
The options below are not interchangeable products. Direct funding describes who provides the capital. Card-linked payments describe how collections work. A broker describes an intermediary. One agreement can combine these features.
Choose the payment structure your business can sustain, then choose the funding relationship. A familiar label does not tell you whether the agreement fits your payroll, supplier bills or sales cycle.
What makes the best merchant cash advance option?
Use these criteria to compare merchant cash advance options in Canada in 2026:
- Funding relationship: Establish whether you are dealing with the funder or an intermediary. Know who approves the application and manages the account.
- Eligibility fit: Check operating history, monthly revenue and any payment-processing requirements before applying.
- Collection structure: Identify whether payments follow card sales or use another collection arrangement. Read the actual formula.
- Total obligation: Compare the amount received with the complete amount payable. Ask for every contractual charge in writing.
- Cash-flow fit: Test the collections against a slower sales period, not just your strongest month.
- Contract clarity: Review early-payment conditions, security requirements and what happens when payments are missed.
Do not rank an offer by approval speed alone. Funding that arrives quickly still needs to leave enough operating cash for the work it is meant to support.
Merchant cash advance options at a glance
This 2026 comparison ranks decision routes, not competing branded products. The line of credit appears as a clearly marked alternative because recurring access to funds is a different need from a single advance.
2M7 direct-funded merchant cash advance
- Best for: Owners seeking a direct funding relationship
- Standout feature: Direct funder rather than a broker
- Key limitation: Minimum operating-history and revenue requirements apply
Card-sales-linked merchant cash advance
- Best for: Businesses processing daily card payments
- Standout feature: Collections tied to card sales where the agreement specifies it
- Key limitation: Not a fit for businesses without qualifying card processing
Broker-arranged merchant cash advance
- Best for: Owners wanting an intermediary to approach funders
- Standout feature: A separate party manages the funding search
- Key limitation: The broker is not the source of capital
Business line of credit
- Best for: Businesses needing recurring draws and repayments
- Standout feature: Reusable borrowing access, subject to the agreement
- Key limitation: A loan alternative to an advance, with its own underwriting requirements
1. 2M7: best merchant cash advance for direct-funder access
This Canadian direct funder provides merchant cash advances and working capital to small and mid-sized businesses. You deal with the funding provider rather than a broker. Funding uses include payroll, inventory, equipment and cash-flow gaps.
The stated eligibility baseline is at least 3 months in business and $15,000 in monthly revenue. Businesses with less-than-perfect credit are within its stated audience, but eligibility is not an approval decision.
Best for: An operating Canadian business that meets those thresholds and wants a direct relationship with its funder.
2M7 pros
- Direct funding means there is no broker between your business and the capital provider.
- The stated audience includes businesses with less-than-perfect credit.
- One fixed cost of capital is shown before signing and does not change based on how long repayment takes.
- Existing clients can text or call their funding representative directly.
2M7 cons
- Businesses below the operating-history or monthly-revenue thresholds do not meet the stated baseline.
- Flex payments are only for businesses that process daily card payments.
- Meeting the baseline does not establish that the proposed collections fit your cash flow.
The published approval rate is 75%, not an individual promise. Assess the written offer on its own terms, including the collection arrangement and the cash your business retains after payments.
Verdict: Buy only after confirming that the written obligation and collection schedule fit your operating budget.
2. Card-sales-linked advances: best for daily card-processing businesses
A card-sales-linked merchant cash advance uses card receipts as the basis for collections where the agreement specifies that arrangement. This structure is relevant when your business processes daily card payments and wants collections connected to those receipts.
Do not assume every merchant cash advance works this way. The label alone does not establish the collection percentage, payment frequency or treatment of sales outside the card channel.
Best for: A business with daily card transactions that can verify the relationship between card sales and collections.
Card-sales-linked advance pros
- The agreement can connect collections to the payment channel your business uses daily.
- A clearly stated collection formula lets you model the effect of different card-sales levels.
- Reviewing card receipts alongside collections helps you assess the operating cash left for other bills.
Card-sales-linked advance cons
- Businesses without qualifying daily card processing need a different structure.
- Card receipts alone do not show your full cash position, including supplier payments and payroll.
- Sales-linked collections do not remove the contractual obligation or make the funding cost disappear.
Ask the funder to explain how refunds, chargebacks and processing changes affect collections. Get the answers in writing rather than relying on a general description of flexibility.
Verdict: Buy only when the agreement explicitly links collections to card sales and your cash-flow forecast supports it.
3. Broker-arranged advances: best for an intermediary-led search
A merchant cash advance broker helps arrange funding from another provider. The broker is an intermediary, not the business supplying the capital. That distinction matters when you need to understand who makes decisions and who handles the account after funding.
The value of this route depends on the actual search process. Ask which funders the broker approaches, how information is shared and how compensation works before submitting documents.
Best for: An owner who wants an intermediary to manage a funding search and is prepared to check the underlying funder independently.
Broker-arranged advance pros
- An intermediary can coordinate the application process with the funders it works with.
- The broker can help explain the offers it presents.
- You can assess its proposed search process before authorising submissions.
Broker-arranged advance cons
- A broker's presence does not establish that every relevant funding option has been considered.
- You must distinguish the broker's responsibilities from the funder's contractual obligations.
- Compensation and information-sharing arrangements need separate scrutiny.
Compare written agreements, not just the broker's summary. Identify the legal funding counterparty, the party collecting payments and the contact responsible for account questions.
Verdict: Hold until you understand the funder, the broker's role and every disclosed charge.
4. Business lines of credit: best alternative for recurring draws
A business line of credit is borrowing access that lets you draw funds up to an approved limit, subject to the agreement. Repayments can restore available borrowing capacity under its terms. It is not a merchant cash advance.
Include this alternative when your real need is repeated access to working capital rather than one defined funding amount. Compare the lender's underwriting, interest, charges and account conditions with the advance being considered.
Best for: A business that needs recurring draws and can satisfy the lender's requirements.
Business line of credit pros
- You can draw funds as needed within the approved facility's terms.
- Repayment can restore borrowing capacity rather than requiring a separate advance.
- The structure supports a recurring funding need when the facility remains in place.
Business line of credit cons
- Approval and account terms depend on the lender's underwriting requirements.
- Interest, charges and security requirements need careful comparison.
- Access remains subject to the agreement rather than being an unconditional reserve.
A line of credit is not automatically the right answer. Match its draw rules and repayment requirements to your actual collection cycle, especially when customer payments arrive after supplier bills fall due.
Verdict: Buy if recurring access is the need and the facility's terms fit; skip it as a substitute for fixing persistent operating losses.
How to compare written offers before signing
In 2026, use the same business forecast for every offer. Otherwise, you risk comparing one proposal against an optimistic month and another against a conservative month.
Define the need
Name the expense and the business outcome it supports. Payroll, inventory replenishment and equipment purchases have different cash-flow patterns. Separate the amount needed for that purpose from any additional amount offered.
Confirm eligibility
Check the stated revenue, operating-history and processing requirements. Explain your revenue sources accurately. A business paid mainly by invoices should not evaluate a daily-card-processing requirement as though those payment channels were identical.
Review collections
Write down when collections occur and what determines their size. Identify the business account or payment channel involved. Ask what the agreement requires if sales fall or a scheduled payment cannot be completed.
Test cash flow
Place the proposed collections beside payroll, rent, supplier commitments and existing obligations. Use your own slower-period records rather than an invented industry average. The useful result is the cash left to operate, not simply whether the collection can clear.
Read conditions
Review early payment, additional funding, missed payments, security and any personal obligations. Ask for unclear terms to be explained before signing. Keep the signed agreement and disclosures together for reference.
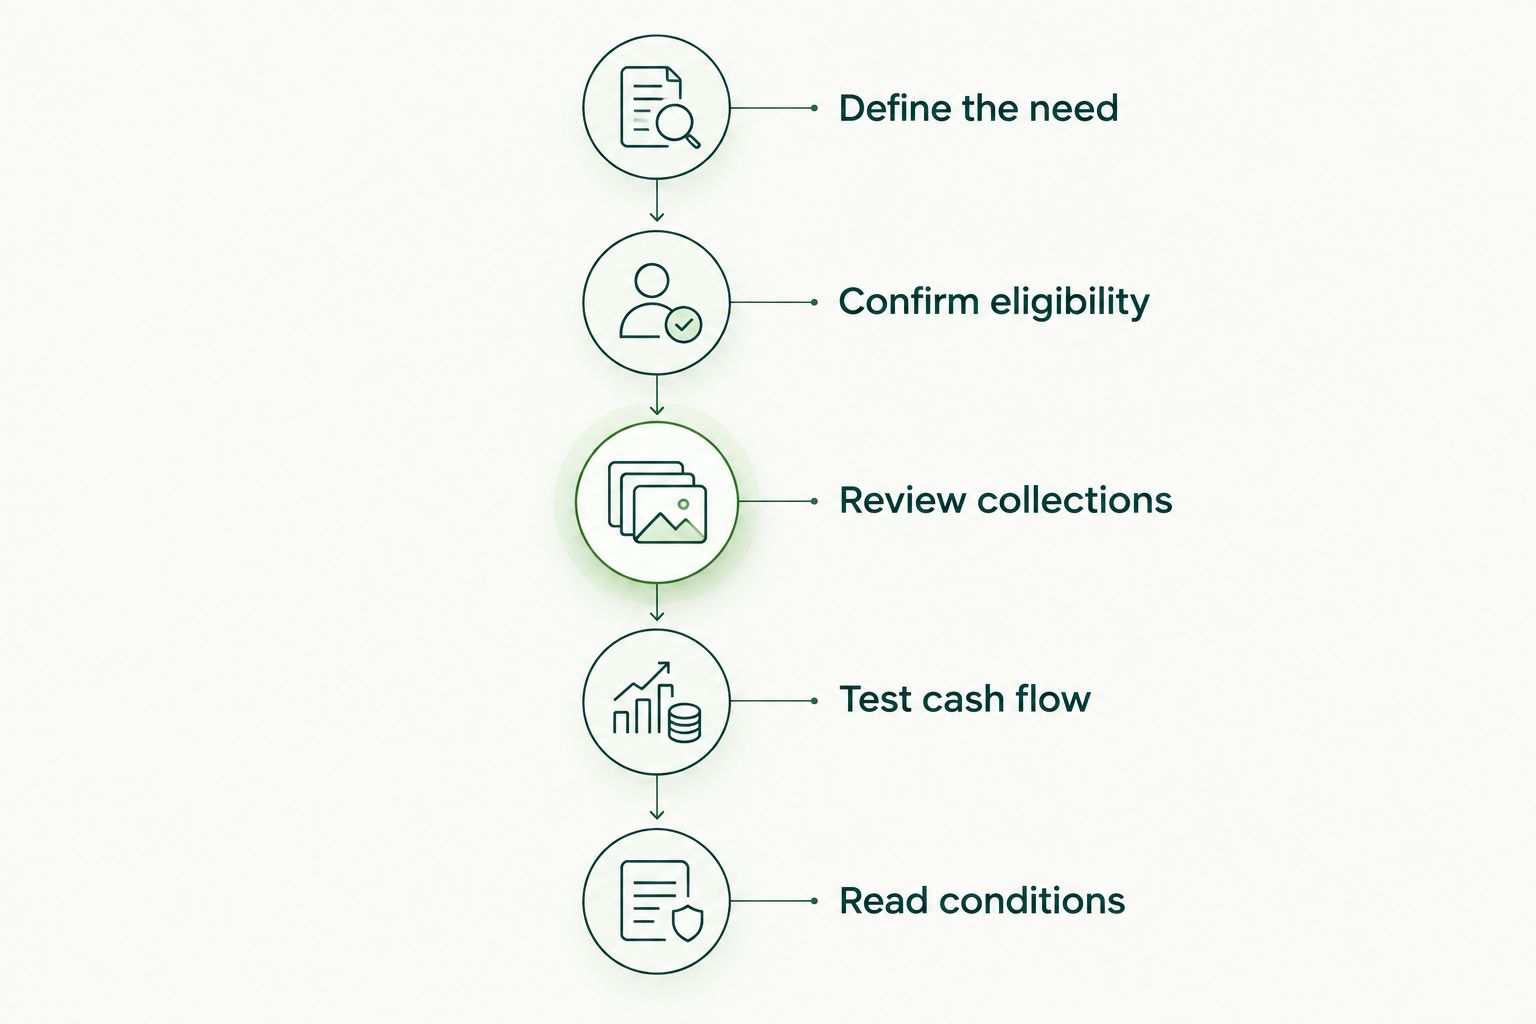
Check operating cash flow before accepting the agreement.
The final comparison should make the trade-off visible: how much operating cash the funding adds now, what your business must pay under the agreement and what remains available for ordinary expenses.
How this ranking works
The 2026 ranking prioritises a clear funding relationship, eligibility fit, collection transparency and a distinct use case. It does not treat direct funding, broker involvement and card-linked collections as mutually exclusive products.
The first recommendation answers who you deal with. The second addresses payment structure. The third addresses how you search. The fourth tests whether a different borrowing structure better matches recurring needs.
Which merchant cash advance option should you choose?
2M7 is best for Canadian business owners seeking a direct-funded merchant cash advance without a broker. Start there if that relationship is your priority and you meet the stated operating-history and revenue thresholds.
If daily card receipts drive your cash flow, scrutinise the collection formula next. If you prefer an intermediary-led search, check the broker's role and the underlying funder separately. If you need repeated draws, compare a business line of credit before committing to an advance.
For a 2026 decision, choose the agreement your business can support during a slower period, not the largest amount offered. Discuss your funding options with a funding specialist and ask for the complete terms before deciding.
FAQ
What's the best merchant cash advance option in Canada?
The best option is the one whose eligibility requirements, collection structure and contractual obligation fit your business. Choose a direct funder for a direct funding relationship, and assess card-linked collections separately from who supplies the capital.
Is a merchant cash advance a business loan?
A merchant cash advance is not a conventional business loan. It provides business funding against future sales under an agreement, so compare its actual terms rather than treating it as interchangeable with a line of credit.
Does every merchant cash advance adjust payments when sales fall?
No, the merchant cash advance label does not establish how collections change with sales. Check the written formula and ask the funder to explain what happens during a slower period.
Is a direct funder better than a broker?
A direct funder suits owners who want to deal with the capital provider rather than an intermediary. A broker suits owners who want help arranging a funding search, but the underlying funder's agreement still needs independent review.
Can a business with less-than-perfect credit apply?
Less-than-perfect credit does not rule out every merchant cash advance option. Check each provider's stated eligibility requirements, and distinguish permission to apply from an actual approval decision.
What should I compare besides the funding amount?
Compare the complete contractual obligation, collection frequency, collection formula and early-payment conditions. Test those terms against payroll, suppliers and other existing commitments using your own cash-flow records.
When is a business line of credit a better alternative?
A business line of credit fits a recurring need for draws and repayments when your business meets the lender's requirements. It is a different borrowing structure, so compare underwriting, interest, charges and account conditions rather than assuming it works like an advance.
One last thing
A payment that changes with sales and a cost that changes over time are different features. Do not confuse them. Ask two separate questions: what determines each collection, and what determines the total contractual obligation?
That distinction makes a funding conversation more useful. You can evaluate flexibility without assuming it changes what the agreement requires your business to pay.
Related guides


