ClickCease

What is Working Capital?

What is Working Capital?

Learn About Working Capital and How it Works
1
Sep 2023
20
Oct 2026

A big part of business is focusing on profit margins and productivity, but keeping a business operating healthily gets a bit more complicated than that. One of the concepts you can’t afford to neglect is working capital. Working capital is a necessary data point for any business, and while sometimes it’s taking a bit more time to understand, it is absolutely crucial for maintaining a healthy balance sheet and operating effectively. We’re going to go over what working capital is, why it’s important, and some of its uses in the business world. Let’s get started.

What is Working Capital?

Working capital is essentially what you have left after taking out all the money you need to pay the bills. Think of it like you would in your personal life with a normal job. You get paid, you add up all your household bills and debts, set that money aside to take care of those necessary expenses, and you can work with whatever you have left. If needed, you also have assets you can leverage such as your savings, valuables, and other things that can help beyond the cash you have on hand. In more professional terms, this is everything you have, assets and cash on hand, minus the liabilities you have such as credit card debt, the bills necessary to keep the business running, payable taxes, and more. How you determine your overall working capital is by adding up your assets and financial resources and subtracting the total amount required to pay your expenses. We’ll keep it easy with solid numbers, but your actual calculation will likely be slightly more complicated. Let’s say you add up your assets and have $100,000 in value. After you add up your liabilities, you calculate that you have $50,000 to pay in total. $100,000 minus $50,000 is $50,000. That's your working capital.

Why is Working Capital Important?

Working capital is important in two main ways. At a first glance, it seems as if having as much of it available as possible, but that’s not quite accurate. Let’s go over both ways it can go and why balance is important.

What is Negative Working Capital, and Why it is Important?

This is the primary concern most business owners are going to have, and it’s certainly one that is most immediately noticeable. Negative working capital is when you use the formula we provided earlier, and you don’t have enough to cover your liabilities. That means you don’t have enough to pay your bills, essentially. If you don’t have the capital available to pay off your liabilities, you certainly can’t commit to any sort of growth, and the immediate future of your business doesn’t look promising, either. There are solutions to this that we will talk about later, but this is the worst-case scenario in a lot of situations.

What is Positive Capital, and Why it is Important?

Positive working capital is the opposite of negative working capital. It’s when you do have some resources left over to work with. For example, if you were the average homeowner working a normal job, you’d have some money left over after paying bills. Not all of it is “take home money”. Some of it has to go into savings in case you plan something big, like a major family trip abroad. The same concept goes for positive capital in business. That doesn’t mean that having it in extreme excess is optimal, though. In fact, it can mean that you’re making poor business decisions. If you regularly have way more working capital than expected, it typically means that you’re not taking advantage of growth opportunities, low debt situations, and other crucial parts of the business world. In the long term, this can mean that your business growth stagnant and that excess will start to decline eventually. It can also mean that you’re not providing reasonable upkeep for your business, which has major consequences, or it can mean that you’ve failed to account for various liabilities and your results are false; which is a major accounting error. In the vast majority of situations, you want to have your growth goals in mind, and you want enough to facilitate those goals. It’s also “working” capital. So, make sure it’s working for you.

How to Increase Working Capital for Higher Growth Potential?

Whether your business has a negative working capital amount, or you simply have larger growth goals you want to accomplish, increasing your working capital is usually going to be attractive. As long as you’re actually using it. Doing that can be difficult, but there are some key data points to target and strategies to use. Primarily, you’ll have two core options: You can increase the number of assets you have to offset your liabilities, or you can get rid of some liabilities such as debts that are close to being paid off.

Increasing Working Capital Assets:

Increasing your working capital assets is going to focus on improving your margins. The larger your margin is, the more working capital you’ll have left over assuming you don’t increase your liabilities. This is essentially the same as telling you to "earn more money”, which isn’t very constructive if money is the problem in the first place. If you’re already generating positive working capital, focusing some of those resources on short-term growth that helps with your margins is a strategy you can use. However, that’s a problem if you’re in the negative since you don't have anything to work with. For example, let’s say you have positive working capital, but you don’t have enough to focus on your goals. You might not be financially capable right now. Instead, pump some of that into marketing a big sale, increasing your inventory in high-demand areas, and similar things to earn more working capital. That’s where a working capital loan comes in, and we’ll get to that shortly.

Decreasing Liabilities to Gain Working Capital:

The other way to earn more working capital is to get rid of liabilities where possible. If there is debt that can be paid off in the short term, paying that off frees up a little more to go toward working capital amounts. If you can lower your tax liability, that’s another way to keep a bit more of your margin. It can also be possible to delay purchases. While growth is the ultimate goal, if you’re struggling to maintain a healthy balance sheet, delaying purchases until you can generate more working capital to accommodate them is crucial. For example, let’s pretend you’re a restaurant. You’re moving around $50,000, but after you pay your vendors, staff, and landlord, you’re only keeping $10,000, and that’s your net working capital. If you can consolidate some of this cost, for example automate ordering process and reduce waiter’s team, you can lower the liability cost and generate more profits. Again, this is something that a working capital loan can help with if liability removal strategies aren’t working or aren’t feasible.

What is a Working Capital Loan?

Alright, we’ve talked about a variety of issues that can pop up with working capital and damage your ability to grow, but now it’s time to start talking about real solutions. There are a lot of situations where you just don’t have any room to work with. You can’t boost your assets, because you don’t have capital, and you can’t remove any liabilities, because they’re all long-term, non-negotiable, and absolutely required. So, how do you get over that speed bump? Primarily, you can get a working capital loan. A working capital loan is a loan used to overcome cash flow problems; but it’s not just used in negative circumstances. Any business owner can benefit from one at a certain point, and it can be a positive experience. Here are some of the ways it’s used.

Funding Growth Goals

1. Funding Growth Goals

Sometimes, you’ll have growth goals, and you’ll have positive working capital, but you just don’t have enough funds. In that circumstance, you can use a working capital loan to get that extra bit of funding you need in the short term. For example, let’s say it’s the perfect time to open a new location, but you’re $20,000 short on the overall costs. A working capital loan can help. Of course, the payments will become liabilities later. So, it’s best to be in a relatively healthy position when using a loan for this purpose. For another perspective on using funding to support growth, read merchant cash advance funding for business growth.

2. Overcoming Financial Speed Bumps

Every business will experience a speed bump in its financial growth at some point. Take COVID-19 for example. Nearly every business went from doing great to suddenly seeing a drop in assets for one reason or another. A working capital loan can help overcome those bumps. If you go into the negative slightly, you can get a working capital loan that helps you remove smaller liabilities and invest in ways to build up non-depreciating assets to grow your margins. There are strategies involved in using a working capital loan this way, but one can save a business and keep it above water in such situations. It’s a lot like when you accidentally spend too much of your check as an average person, and your car payment is coming up. You don’t want to lose your car. So, you get a personal loan to cover it until you’re in a better situation.

3. Waiting on Invoice Payments

In an ideal world, all customers would pay on time, and you’d know exactly when funds were going to arrive. Unfortunately, that’s not how it works. Sometimes, you’ll technically have plenty of working capital on the horizon, but invoices just aren’t getting paid on time. A working capital loan can work like an advance on those invoices to make sure you’re still able to make moves while you wait.

4. Taking Advantage of Opportunities

Sometimes, you’ll be presented with opportunities you don’t want to pass up. For example, maybe you rely heavily on a supplier’s hardware for one of the products you manufacture. For a limited time, they’re offering half-off on bulk shipments of that hardware. That can allow for tremendous savings in the future and a lot of potential for growth. However, you might not have the ability to fund it without throwing your balance sheet off balance. This is another situation where a working capital loan can be the little edge you need to come out on top. Its fast, gets the job done, and keeps you from missing such fruitful opportunities.

Understanding the Working Capital Cycle

Beyond noticing problems with your working capital and finding solutions, you’re also going to want to look at the working capital cycle. This will help you predict when you’re going to have certain assets available, and that allows you to plan for them efficiently. The working capital cycle is the time it takes for your assets to become cash that can pay off your liabilities. For instance, think about the customer invoices for a subscription service. You know that 1000 customers are set to pay their invoice on the 30th. That means that, while you have those accounts as assets, they aren’t realized yet. You don’t actually have the money. The time between now and those payments clearing is your working capital cycle. After the 30th, you would be able to pay your liabilities in this scenario. As such, you want to streamline your working capital cycle as much as possible to ensure everything is moving quickly and efficiently. The best way to do this is to ensure that your customer payments are covering your liabilities. Since waiting for accounts to clear usually takes the longest, ensuring that they pay the liabilities off allows your other assets to simply keep growing and building up more working capital.

The Risk of Certain Working Capital Assets

You’ve probably put together a decent understanding of what working capital assets are at this point. If not, the basics are your customer invoices, inventory, cash, and pre-paid debts. One of those is somewhat volatile, and you shouldn’t aim to build much of your working capital on it. That’s your inventory. Your inventory can be a risky asset. It can become obsolete, depreciate in value, and dramatically impact your working capital amount without any chance of turning into cash. Take fidget spinners for example. During the craze, everyone stocked up on them. That was almost guaranteed cash flow. However, when the trend stopped, that inventory became largely useless. Anyone with too much inventory consisting of that product saw their cash flow tank. This can happen with anything. So, it’s important to understand that risk, diversify assets, and have a solid plan to use your inventory; not just stockpile it for perceived working capital. Think of all the people who bought into Beanie Babies in the 90s, and then think of what happened a few years later when no one cared. The Beanie Babies represent your inventory, and no one caring represents your entire inventory devaluing like crazy. You don’t want things sitting around unless they are guaranteed to be necessary for the future.

3 Types of Working Capital

The Three Types of Working Capital and How to Differentiate

Finally, there are three types of working capital, and while they all generally work the same way, you will need to differentiate between them.

1. Net Working Capital

This is all the working capital you have at your disposal, and it’s the general number that you’re going to want to keep tabs on.

2. Temporary Working Capital

This is your working capital amount in temporary situations. Think of things such as the speed bumps we talked about earlier, or maybe even expected boosts such as holiday sales. Since the causes for the fluctuations are temporary, you have to work that into your understanding of your working capital during that time period.

3. Permanent Working Capital

The name of this one is misleading. It’s not the amount you’re guaranteed to have all the time. It’s the amount you absolutely need to make it. If you make less, your business’s health starts dropping, and you either fix it or lose it. This is the bottom line of what you need to barely get by, and you want to calculate it regularly since your liabilities and assets will change regularly.

Get a Working Capital Loan with 2M7 Financial Solutions

If you’ve gone through this brief guide and realized you could really use a working capital loan to help your business for any reason, contact us to start the process. We specialize in advanced loans that can help your business seize opportunities, fix temporary problems, and continue operating in a healthy state.

Related articles

October 19, 2026
October 19, 2026

Best equipment financing for healthcare and dental practices 2026

Best overall: a dedicated equipment loan for a planned, long-term purchase. Best for scheduled upgrades: equipment leasing. Best for equipment plus operating expenses: 2M7 merchant cash advance funding. This 2026 guide compares equipment financing for healthcare practices by ownership, payment structure and fit for your cash flow.

TL;DR

  • Dedicated equipment loans are the default equipment financing for healthcare practices buying assets for long-term use.
  • Equipment leasing suits dental and healthcare practices that want an agreed equipment replacement or return path.
  • 2M7 merchant cash advance funding suits equipment purchases combined with payroll, inventory or other working capital needs.
  • Compare total repayment, ownership terms and payment obligations before choosing funding.

Why this matters

A dental chair and the payroll needed to operate a practice are different funding needs. An equipment agreement addresses the asset; working capital addresses the business around it. Bundling both into the wrong agreement makes comparison harder.

For a 2026 purchase, start with the equipment's expected useful life and the practice's available cash. Then compare financing structures. A lower scheduled payment does not establish a lower total cost, and equipment delivery does not necessarily mean the equipment is ready to generate revenue.

Choose the funding structure before choosing the provider. That keeps ownership, payment obligations and installation expenses in the same decision.

What makes the best equipment financing for healthcare practices

Use these criteria to compare written offers for medical, dental and other practice equipment:

  • Ownership: Establish who owns the equipment during the agreement and what happens at the end.
  • Useful life: Match the funding period to how long you expect to use the asset, not just the payment you prefer.
  • Total obligation: Compare the full amount payable, including required fees and any end-of-term purchase obligation.
  • Cash flow fit: Check payment frequency against patient collections, insurer payments and other operating commitments.
  • Funding scope: Confirm whether the agreement covers equipment alone or also delivery, installation, training and operating expenses.
  • Exit terms: Read early settlement, equipment return, replacement and security provisions before signing.

For your 2026 shortlist, request these details in writing. An equipment quotation and a financing quotation answer different questions; you need both to judge the purchase.

Equipment financing options at a glance

The ranking below reflects a planned equipment purchase as the default situation. Each alternative serves a different need rather than claiming to be the cheapest for every practice.

Dedicated equipment loan

  • Best for: Planned purchases for long-term ownership
  • Standout feature: Borrowing tied to an equipment purchase
  • Key limitation: Security, guarantees and eligible expenses depend on the agreement

Equipment lease

  • Best for: Planned replacement or return
  • Standout feature: Contract defines equipment use and end-of-term choices
  • Key limitation: Ownership and exit rights are not automatic

2M7 merchant cash advance

  • Best for: Equipment plus working capital
  • Standout feature: Direct funding for equipment and operating needs
  • Key limitation: Existing business and revenue requirements apply

Business line of credit

  • Best for: Smaller purchases made in stages
  • Standout feature: Draw funding as eligible expenses arise
  • Key limitation: Access remains subject to the facility's terms and limit

1. Dedicated equipment loan: best for long-term ownership

A dedicated equipment loan finances an equipment purchase through a lending agreement. It is the strongest starting point when you know the asset, intend to keep it and can support scheduled payments from practice cash flow.

For a dental practice buying a chair or a healthcare practice buying diagnostic equipment, ownership matters beyond delivery. Check whether the lender takes security over the equipment, other business assets or both, and whether a personal guarantee is required.

Equipment loan pros

  • Supports a purchase intended for long-term use.
  • Separates a major capital purchase from routine operating spending.
  • Lets you compare a defined borrowing amount and repayment schedule.
  • Provides a clear basis for comparing purchase funding against leasing.

Equipment loan cons

  • Required security and guarantees can extend beyond the equipment itself.
  • Installation, training or related expenses need explicit approval for inclusion.
  • Selling or replacing financed equipment can require the lender's consent.

Best for: Established practices purchasing equipment they expect to keep rather than replace on a short cycle.

Ask the lender how it handles used equipment, supplier deposits and delivery delays. Do not assume approval for the machine also covers renovations or the period before it becomes operational.

Verdict: Buy with a dedicated equipment loan when long-term ownership is the priority and the complete repayment schedule fits your practice.

2. Equipment leasing: best for planned replacement

Equipment leasing gives your practice the right to use equipment under a contract. The agreement determines payments, responsibilities and what you can do when the term ends.

A lease deserves a place on your shortlist when you expect to replace equipment as practice requirements change. It is not automatically a subscription with a simple return process: purchase options, renewal provisions and return conditions must appear in the contract.

Equipment lease pros

  • Makes equipment use, rather than immediate ownership, the starting point.
  • Can support a planned replacement cycle when the contract provides for it.
  • Defines end-of-term choices before you commit.
  • Creates an alternative to borrowing for an outright purchase.

Equipment lease cons

  • Payments do not automatically give your practice ownership.
  • Early termination and equipment returns can create additional obligations.
  • Maintenance, insurance and servicing are not automatically included.

Best for: Dental and healthcare practices with a clear replacement plan and acceptable contractual return or purchase terms.

Before choosing a lease in 2026, ask what happens if the equipment stops meeting your clinical needs before the term ends. Also confirm who handles removal, shipping and any required restoration when you return it.

Verdict: Buy through leasing when the replacement plan is clear; skip a lease whose exit conditions you cannot accept.

3. 2M7 merchant cash advance: best for mixed funding needs

A merchant cash advance provides business funding rather than an equipment loan. This route fits a different problem: your practice needs equipment and working capital for expenses such as payroll, inventory or a cash flow gap.

2M7 is a Canadian direct funder, not a broker. It serves businesses operating for at least 3 months with $15,000 or more in monthly revenue, including businesses with less-than-perfect credit.

Merchant cash advance pros

  • Supports equipment and working capital needs through the same funding category.
  • Provides a direct relationship with the funder rather than a broker.
  • Includes consideration for businesses with less-than-perfect credit.
  • Uses one fixed cost of capital, disclosed before signing, that does not change with repayment duration.

Merchant cash advance cons

  • Minimum operating history and monthly revenue requirements apply.
  • A fixed cost of capital does not become lower simply because repayment takes less time.
  • Flex payments are only for businesses processing daily card payments.

Best for: Operating practices that need equipment funding alongside payroll, inventory or other working capital, rather than asset-only financing.

The published 75% approval rate is not an individual approval decision. Confirm your practice's eligibility, the proposed payment structure and the full obligation before treating funding as committed.

For healthcare practices paid through a mix of insurer reimbursements, patient payments and other sources, discuss that collection pattern directly. Do not assume a payment feature designed for daily card processing applies to your practice.

Verdict: Buy through merchant cash advance funding when the need spans equipment and operating expenses and the written payment terms fit your collections.

4. Business line of credit: best for staged smaller purchases

A business line of credit provides access to borrowing up to an approved limit, subject to its terms. It suits purchases made at different times rather than a single large asset acquisition.

For example, a practice adding equipment room by room can compare a credit facility with separate purchase agreements. The important distinction is access versus commitment: an available limit is not a reason to spend it all.

Business line of credit pros

  • Supports borrowing as individual eligible expenses arise.
  • Helps separate purchase timing from a single equipment delivery date.
  • Can address incidental business expenses as well as equipment, subject to permitted use.
  • Lets you reserve borrowing for actual purchases rather than estimated future needs.

Business line of credit cons

  • Equipment purchases consume capacity that might otherwise cover operating needs.
  • Rates, payment requirements and review conditions depend on the agreement.
  • A revolving balance needs a deliberate repayment plan.

Best for: Practices making smaller, staged purchases while preserving a defined reserve for day-to-day operations.

Set a repayment target for each equipment purchase before drawing funds. Otherwise, a long-lived asset can sit inside a revolving balance without a clear point at which the purchase is paid off.

Verdict: Buy through a line of credit for staged purchases; skip it when the purchase would absorb the practice's operating reserve.

Compare written offers in the same order

You cannot compare an equipment lease with working capital funding by looking at the scheduled payment alone. Put each offer against the same purchase plan and include the obligations that sit outside the headline payment.

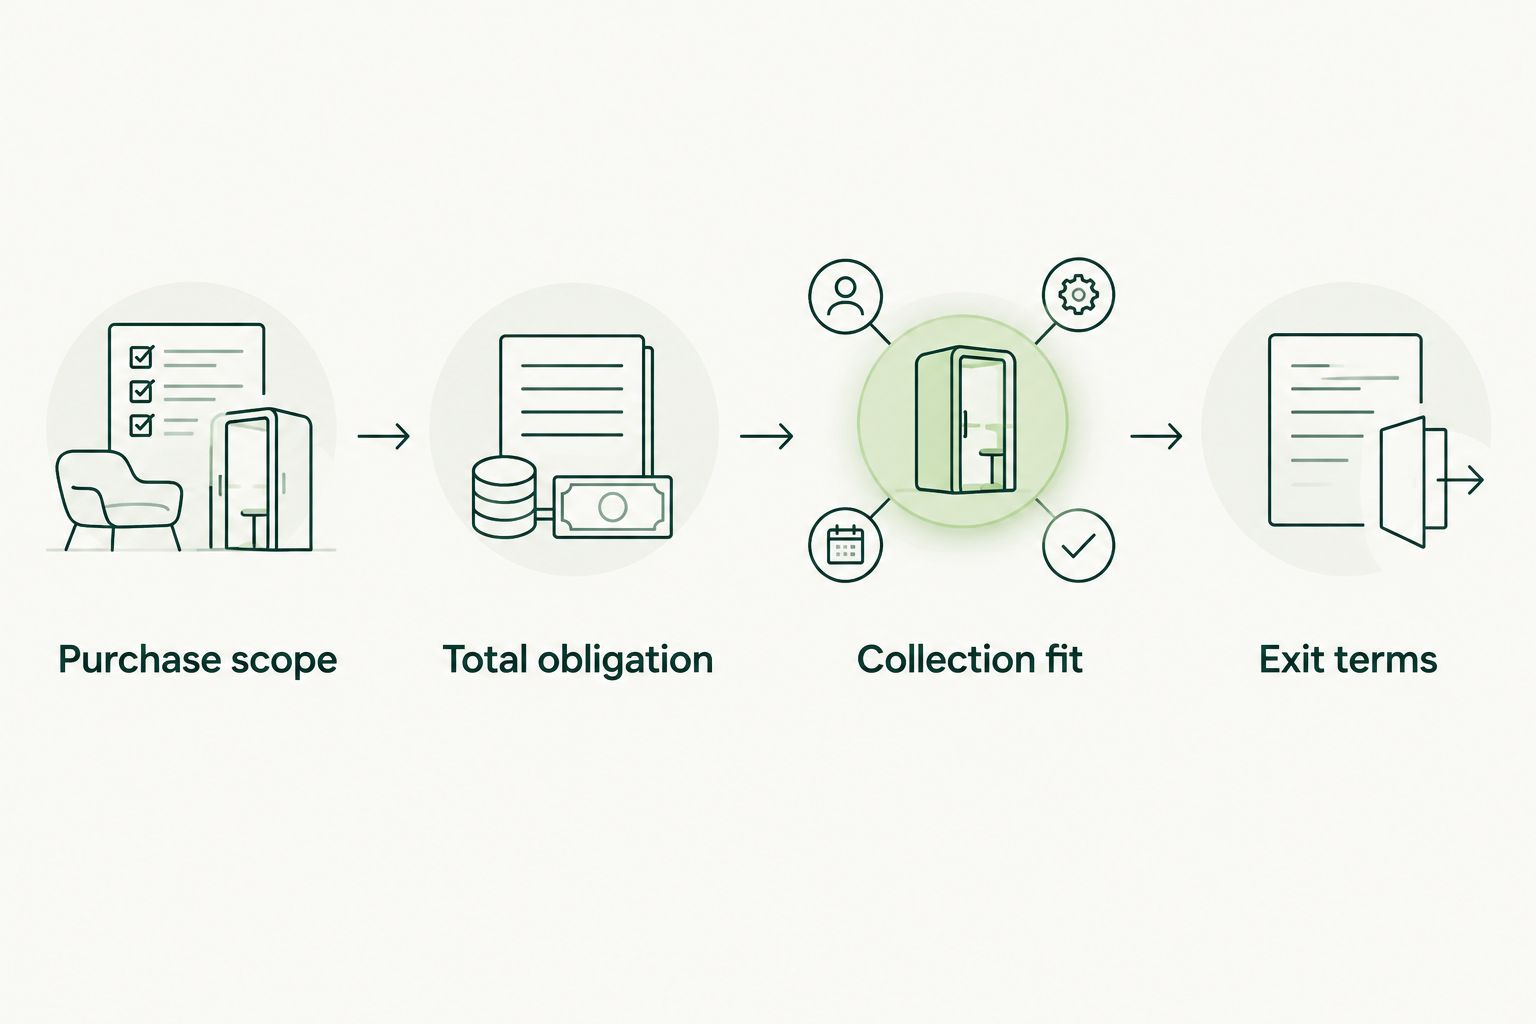
Purchase scope

List the equipment, delivery, installation, training and any site work separately. Mark which expenses each agreement actually covers. Confirm when suppliers require payment and when the practice becomes responsible for financing payments.

Total obligation

Request the full amount payable and the payment schedule. For a lease, include any required purchase payment if ownership is your goal. For other funding, confirm fees, early settlement conditions and security requirements.

Collection fit

Map the proposed payment dates against collections and existing commitments. Include payroll, rent and supplier payments. A purchase that fits annual revenue can still place pressure on cash between collection dates.

Exit terms

Ask what happens if you replace the equipment, sell the practice or settle the agreement early. Get written answers. A verbal explanation does not replace the signed terms.

Four checks for equipment funding: purchase scope, total obligation, collection fit and exit terms.

Compare the complete obligation and collection schedule, not just the scheduled payment.

How the options are ranked

This 2026 ranking puts a dedicated equipment loan first because the default task is purchasing equipment for continued use. Leasing takes the replacement-planning slot, merchant cash advance funding addresses mixed equipment and operating needs, and a line of credit addresses staged purchases.

The ranking uses ownership, useful life, total obligation, cash flow fit, funding scope and exit terms. It is a comparison of funding structures, not a provider scorecard or a claim that one agreement has the lowest cost.

Which equipment financing should you choose?

Start with a dedicated equipment loan for a defined purchase you intend to keep. Compare a lease alongside it when replacement or return is part of your plan, not simply because its scheduled payment looks smaller.

Choose 2M7 equipment funding when the purchase forms part of a broader working capital need and a merchant cash advance fits your practice's collections. Keep a line of credit focused on staged purchases that leave enough capacity for operating needs.

For a 2026 decision, the final test is practical: can you explain the complete payment obligation, ownership position and exit terms without relying on the sales presentation? If not, hold the decision until those points are clear.

FAQ

What's the best equipment financing for healthcare practices?

A dedicated equipment loan is the default starting point for a planned purchase intended for long-term use. Compare leasing for planned replacement, merchant cash advance funding for mixed operating needs, and a line of credit for staged purchases.

Is leasing better than buying equipment for a dental practice?

Leasing is a better fit when the agreement supports your intended replacement or return plan. Buying is the stronger starting point when long-term ownership matters; compare the complete obligations rather than scheduled payments alone.

Does 2M7 offer equipment loans to healthcare practices?

2M7 provides merchant cash advances and working capital, not equipment loans. Equipment is an eligible funding use, and a practice must meet the funder's business and revenue requirements.

Can a newer healthcare practice apply for merchant cash advance funding?

The stated entry requirements include at least 3 months in business and $15,000 or more in monthly revenue. Meeting those thresholds does not establish an individual approval decision or funding amount.

Can equipment financing cover installation and training?

Installation and training are covered only when the agreement includes them. Ask for an itemised list of eligible expenses before committing to equipment or supplier deposits.

What should a dental practice compare besides the payment amount?

Compare the full amount payable, payment frequency, ownership, security requirements and exit terms. Include maintenance obligations and any end-of-term purchase or return requirements.

Are flex payments suitable for every healthcare practice?

Flex payments are only for businesses that process daily card payments. A practice should confirm eligibility based on its actual collections rather than assuming all patient or insurer receipts qualify.

One last thing

Check the gap between equipment delivery and equipment use. Installation, training or site preparation can separate those dates, while payment obligations follow the agreement. Put both dates on your purchase plan before signing, then confirm which expenses your funding covers during that gap.

Related guides

Read more
March 30, 2021
August 10, 2026

How to Get Business Financing With Poor Credit

If you are looking to grow your business, then you may find it challenging if you have poor credit. However, there are a number of options that can help your business get the financing with poor credit. Here’s a look at the steps you can take to secure fencing for your business with poor credit.

1) Check your credit score

The first thing that you should do is know your credit score. If your credit score is below 700, then your credit will be considered subprime. Also, this can prevent you from the top business financing options. You can credit your credit score for free on Credit Karma. You can also request one credit report, per year, from the two major credit reporting agencies.

2) Know your options

Once you know your credit score, then you can explore your options. In fact, if you have a low credit score, then you will want to consider the following types of financing options:

  • Business credit cards - There are a number of business credit cards that allow customers with subprime credit scores. While these credit cards may have higher interest rates, they will allow your business to get the quick funding that you need.
  • Merchant cash advance - A merchant cash advance is an advance based on the credit card sales deposited into your business’s bank accounts. In short, a merchant cash advance can help you get access to your money faster for a small fee. Many businesses used merchant cash advance to gain faster cash flow.
  • Short-term line of credit - A short-term line of credit allows you to draw from a pool of funds. When you pay back the loan with interest, then you can draw from the line of credit again.

3) Create a business plan

If you are looking to secure a short-term business loan, it is a good idea to have a business plan. After all, the bank will want to know what type of business that you are in and how you intend to generate revenue. A well-organized business plan will increase your chances of being approved for a short-term business loan.

4) Have collateral

If you have any form of collateral, then you can secure a loan much more easily. Here are some types of collateral that can allow you to get the funds that your business needs:

  • Vehicle
  • Property
  • Inventory
  • Unpaid invoices
  • Cash

5) Find a co-singer

Finally, you can find a co-signer that can help you secure a loan or financing with poor credit. A co-signer can be anyone from a member of the family to a business partner. The co-signer should be aware that they are liable for the loan if you don’t pay back the principal or the interest.

Getting your business up and running

Bad credit doesn’t have to stop you from funding your business. At 2M7 Financial Solutions, we do not require a credit score to issue a merchant cash advance. Apply now to get a merchant cash advance today.

Read more
September 24, 2021
August 10, 2026

5 Most Common Reasons Businesses Look for Funding

Funding is the only way to turn startups into successful businesses. Getting funding is easier said than done. However, it’s a fact that you need sufficient money to get your business to the next level. Investment and funding are required to raise the necessary capital to either initiate or run a business. The working capital is the option on which companies rely for the smooth running of affairs and uncalled crisis. Funding coupled with motivation, determination, and brilliant ideas can kick start the business off the ground. Lack of proper and timely funding can collapse business strategies and decrease capital, which ultimately causes failure. If you’re wondering why businesses consider looking for funding, you’re at the right place. Following are some reasons due to which funding becomes essential for companies.

Development

Growth and development are the foremost motives of a business before seeking funding. Acquiring new clients, local businesses, and marketing to improve outreach are all the prospects of growth. Establishing additional branches and expanding services is also the result of the funding sought for the sake of growth.

Working Capital

Another significant reason for obtaining fundings is working capital. Working capital is the monetary assets that provide the companies with sustainability. Managing regular affairs and retaining the quality of services are done through the working capital. It can be used to stock the inventory and carry out successful purchases by efficient expenditure. Insufficient working capital can cause detrimental effects to the business in the longer run. The current affairs and prospects depend on the working capital, which is provided through funding.

Acquiring Assets

To hold a firm position in the market and among the competitors, businesses need to purchase assets. Eliminating the competitors in the market is the feature of having more assets. Businesses can emerge out as a winner when they become the sole provider of a service. Companies can either buy shares or completely acquire other businesses. Assets not only strengthen the company but also enhance its market value.

Initiating New Ventures

Companies use funding to plant new ventures. These endeavours can promote the business and increase its progress. To conduct these strategic ventures companies, need ambition and funding. They can articulate ambition in their employees, but for funding, they need help.

Boosting Startups

Funding is vital to support startups in the fierce market. Startups usually have scant resources that can soon become insufficient, leading to a business catastrophe. Startups need financial help and investments to accomplish their goals and thrive among the competitors.

Getting an MCA

Companies can find investors that either work independently or with an organization to gain the required funding. They can also opt for loans from banks. However, the much better alternative is a merchant cash advance that focuses on the growth of a business. Companies prefer MCA as the conditions of the loan are appropriate to their predicament. The best part about getting an MCA is that paying it back is extremely convenient. You’ll only be paying back a specific percentage of your monthly earning. And, if there’s a month where you don’t generate revenue due to whatever reason, you won’t need to pay the finance company back anything. Receiving timely fundings can save companies from derailments. If you’re looking for a financial organization that can get you the resources you need to boost your business, 2M7 is just the company you should work with. We’ve helped hundreds of companies like yours in the past with our 75% approval rating. We offer merchant cash advances to businesses in all industries and of all sizes. Gain an edge over your competition and contact us today.

Read more