ClickCease

How to Get a Business Line of Credit?

How to Get a Business Line of Credit?

How to Get a Business Line of Credit?
18
Nov 2019
27
Jul 2026

What is a business line of credit?

A business line of credit (LOC) is designed to meet the short-term financing needs of businesses. Basically, it is a revolving sum of money lent to a business owner. The borrower pays interest on the borrowed amount while the interest rate may be at a fixed or variable rate, depending on the borrower’s financial state. LOC is a type of debt financing, which is offered by traditional financial institutions in Canada. A business line of credit is often referred to as a “corporate line of credit”. As a debt instrument, they are both the same.LOC is very much like a credit card for your business. The business owner will be given a pre-approved credit amount from which he can draw capital as needed. Once the funds are used, the borrower will need to repay the amount including the interest over the repayment term as agreed. A business line of credit is one of the many options to fund your business or to get funds for a new business. It gives access to affordable credit if the borrower qualifies. The LOC provides ready cash flow, that could help solve the liquidity problems that small businesses tend to suffer the most.

What is a small business line of credit?

Lending providers offer a small business line of credits to small-sized businesses with different combinations of rates and qualifications. These may include the following:  

  • An unsecured line of credit (up to $50,000)
  • Secured credit (up to $1,250,000)
  • Floating interest rates
  • Business insurance
  • Shorter approval/processing times
  • Low monthly fees

A small line of credit under $300,000 can be approved online. For small business owners, a line of credit is one of the easiest ways to secure cash flow for their business operations. The application for a small business line of credit is typically short, and approval can be granted within one business day.

How to get a line of credit for your business?

Banks in Canada have a variety of LOC products for small and mid-sized businesses. You should consider applying for a business line of credit at a bank you’re already registered to. Make sure to apply for a line of credit ahead of time as, unlike loans, it can take up to a month to get approved. In order to apply for a line of credit, you should open a business bank account. Below is a list of documents that you would need to provide for your LOC application:

  • Two pieces of government-issued IDs
  • Proof of income
  • Business financial statements, including income, expenses, assets, and liabilities
  • Other personal- and business-specific information such as an address, license number (if applicable), and how long you’ve been in business

How to get approved for a business line of credit?

Whether or not your line of credit is approved depends on your credit score and your business qualifications. The higher your credit score and the more stable your business income, the more likely it is that you will be approved for a line of credit, and the larger it will be. It is very important to have a good credit score and to keep your business financial documents in order. If a bank is unable to adequately assess your business potential, it will lower the chance of receiving a line of credit. With a private lender, things are a bit easier as the lender may adopt different criteria and qualifications to advance the line of credit. Also, private lenders are more open to lending to businesses with lower credit scores. Remember, when looking for a small business loan line of credit, make sure to evaluate several options. The majority of small businesses prefer to choose private lenders as they are able to receive more flexible offers. Check out how merchant cash advance works to see if your business qualifies.

Why is a business line of credit better than a loan?

A business loan is typically obtained and disbursed only for a specific purpose. It is meant to provide access to capital for a one-time, major financial expenditure. Therefore, to manage your operating cash flow, you will have to apply for multiple business loans – each of which will negatively affect your credit score.However, a business line of credit allows you to improve your credit score. You only borrow the money you need and pay interest based on that amount. A business LOC allows for greater financial planning and resolves cash flow problems that small businesses often experience.

Why you may be denied a line of credit?

There are a number of reasons why you may be denied a business LOC. Most likely, your bad credit score will lead to a refusal, but that is not the only reason. The line of credit may be refused for a number of reasons, including:

  • Purpose of LOC does not meet the required criteria
  • Your industry is too risky
  • The commercial bureau reports negative performance
  • Business revenues indicate insufficient ability to handle monthly payments

Having a low credit score doesn't mean you can't take any type of loan. Check out some ways to get a business loan with a bad credit score.

Approaching a private lender for a small line of credit

If you require a moderate-sized line of credit, it is worth approaching a private lender. A small lender will not require as many documents as the bank, and the approval process will be faster as well. Also, private lenders accept applications for LOCs online and you can get request a quote online. Private lenders will help you understand why your line of credit has been denied by the bank and can provide the necessary funding in a shorter time with less hassle and stress and treated as bad credit debt help. If you are interested in an alternative solution made for small businesses, talk to one of our experts today for the best business cash advance loans.

Related articles

October 19, 2026
October 19, 2026

Best equipment financing for trucking companies in Canada 2026

Best overall for truck ownership: an equipment loan. Best for planned replacement: an equipment lease. Best for recurring repair bills: a business line of credit. Best for equipment-related working capital: a merchant cash advance when its repayment terms fit your revenue. This 2026 guide compares equipment financing for trucking companies by purpose, ownership and cash flow, rather than treating every funding option as interchangeable.

TL;DR

  • Equipment financing for trucking companies starts with a choice: finance the vehicle or fund the business around it.
  • Equipment loans suit ownership; equipment leases suit businesses that prefer use over immediate ownership.
  • Business lines of credit suit recurring operating expenses, subject to approved terms and limits.
  • 2M7 provides merchant cash advances for Canadian businesses seeking equipment-related working capital, not conventional equipment loans.

Why this matters

A truck purchase and a repair-related cash flow gap are different funding problems. A vehicle can support your business for years, while a repair bill needs to be matched against the cash available after the truck returns to work.

Match the funding structure to the expense before comparing providers. Otherwise, you can end up using operating cash for a long-term asset or taking on a repayment schedule that leaves too little room for fuel, insurance and payroll.

2M7 is a Canadian direct funder, not a broker, offering merchant cash advances and working capital. That makes it relevant to equipment-related cash needs, but not interchangeable with a lender financing a specific truck.

What makes the best trucking equipment financing?

Use these criteria to compare your 2026 options before requesting an offer:

  • Funding purpose: Separate buying a truck from paying for repairs, equipment, payroll or a cash flow gap.
  • Ownership: Establish who owns the equipment during the agreement and what happens at the end.
  • Cash flow: Compare payment timing with actual collections, not just the dates you issue invoices.
  • Security: Identify the truck, other assets or guarantees covered by the agreement.
  • Total obligation: Review the complete repayment obligation, charges and end-of-term requirements in writing.
  • Eligibility: Check business history, revenue, credit and equipment requirements before preparing an application.

No option wins every category. A suitable purchase agreement can still be unsuitable for recurring expenses, and an accessible working capital offer can still put pressure on operating cash.

Trucking equipment financing at a glance

Equipment loan

  • Best for: Buying a truck you intend to keep
  • Standout feature: Financing tied to an equipment purchase
  • Key limitation: Security and repayment obligations require close review

Equipment lease

  • Best for: Using equipment with a planned replacement strategy
  • Standout feature: Contract defines equipment use and end-of-term choices
  • Key limitation: Ownership is not automatic

Business line of credit

  • Best for: Recurring repairs and operating expenses
  • Standout feature: Reusable borrowing capacity under the agreement
  • Key limitation: Approval, limits and renewal terms constrain access

Merchant cash advance

  • Best for: Equipment-related working capital supported by business revenue
  • Standout feature: Funding assessed against the operating business
  • Key limitation: It is not a substitute for reviewing truck-specific financing

These are financing structures, not a ranking of named lenders. Actual suitability depends on the written offer, your business finances and the equipment involved.

1. Equipment loan: best for long-term truck ownership

An equipment loan finances an equipment purchase through a lending agreement. For a trucking company buying a vehicle it intends to keep, it is the clearest starting point because the funding decision centres on the asset and the business's ability to repay.

Ask whether the lender accepts the truck's age, condition, seller and intended use. Do not assume an offer for one vehicle applies to another, even when both serve the same route.

Equipment loan pros:

  • Connects the financing request to a defined equipment purchase.
  • Supports an ownership-focused fleet plan.
  • Provides a repayment schedule you can assess against operating cash flow.

Equipment loan cons:

  • Security arrangements can restrict your ability to sell or refinance the truck.
  • Payments continue when the truck is idle or undergoing repairs, unless the agreement provides otherwise.

Best for: An established owner-operator or fleet buying equipment for continued use.

Before accepting an equipment loan in 2026, ask what happens if you sell the truck, repay early or need to replace it after a breakdown. Also confirm whether the agreement covers only the equipment or requires additional security.

Verdict: Buy through an equipment loan when ownership is the goal and the payment leaves room for maintenance and downtime.

2. Equipment lease: best for a planned replacement strategy

An equipment lease gives your business the right to use equipment under a contract. The agreement determines payments, responsibilities and what happens when the lease ends.

A lease belongs on your shortlist when access to the truck matters more than immediate ownership. It requires careful end-of-term planning, not just a comparison of periodic payments.

Equipment lease pros:

  • Separates the decision to use equipment from outright ownership.
  • Can support a defined equipment replacement plan.
  • Establishes contractual choices for the end of the lease.

Equipment lease cons:

  • Returning or purchasing the equipment depends on the specific agreement.
  • Usage, condition and early termination provisions can limit flexibility.

Best for: A trucking company with a clear replacement plan and predictable equipment requirements.

Request the full end-of-term wording before signing. Check for purchase obligations, return conditions and any restrictions that conflict with your intended operation. Do not assume maintenance, insurance or repairs are included simply because the vehicle is leased.

For a 2026 comparison, put the lease's total obligations beside the equipment loan's total obligations. A smaller periodic payment does not establish which agreement is better for your business.

Verdict: Buy into a lease only when its use restrictions and end-of-term terms fit your fleet plan.

3. Business line of credit: best for recurring repair expenses

A business line of credit lets you borrow within an approved limit under the lender's terms. Its main role in trucking is managing recurring operating expenses, rather than replacing a dedicated truck-purchase agreement.

Repairs, parts and maintenance do not always line up with customer collections. A credit line gives you a structure to assess those repeated cash needs without treating each expense as a separate equipment acquisition.

Business line of credit pros:

  • Provides reusable borrowing capacity under the agreement.
  • Supports different operating expenses rather than one named asset.
  • Lets you distinguish short-term cash needs from long-term equipment ownership.

Business line of credit cons:

  • Approved limits and renewal conditions can constrain your plans.
  • A continuously drawn balance can conceal an unresolved operating shortfall.

Best for: A trucking business with recurring expenses and a credible plan to restore available credit from collections.

Check whether the facility is secured, what reporting is required and how repayment works. Ask about the lender's rights to change or demand repayment of the facility; do not assume access remains unchanged indefinitely.

If your plan depends on keeping the line fully drawn, reassess the underlying cash flow. Reusable credit works best when your business can repay drawings, not simply move expenses into a growing balance.

Verdict: Hold off on using a line of credit for a truck purchase unless the written terms and repayment plan support that use.

4. Merchant cash advance: best for equipment-related working capital

A merchant cash advance provides business funding through an agreement distinct from a conventional equipment loan. Consider it when the need extends beyond acquiring a vehicle, such as equipment expenses alongside payroll, inventory or a cash flow gap.

2M7 is best suited to Canadian businesses seeking merchant cash advance working capital, rather than a conventional truck-purchase loan. It serves businesses operating for at least 3 months with $15,000 or more in monthly revenue, including businesses with less-than-perfect credit.

Merchant cash advance pros:

  • Addresses operating-business needs, including equipment-related expenses.
  • Offers an alternative structure to conventional equipment borrowing.
  • Provides a direct-funder option through 2M7, without a broker between the business and funder.

Merchant cash advance cons:

  • It is not an equipment loan and should not be compared as though the contracts are identical.
  • Repayment obligations still need to fit cash flow after essential operating expenses.

Best for: A revenue-generating Canadian business that meets the funder's requirements and needs working capital rather than asset-specific financing.

For 2M7 working capital, the cost structure is one fixed cost of capital shown before signing; it does not change based on how long repayment takes. Review the total obligation and repayment mechanism alongside your other written offers. Flex payments are only for businesses that process daily card payments, so do not assume that feature applies to a trucking operation paid through invoices.

Verdict: Buy into a merchant cash advance only when its business purpose and repayment terms fit your collections.

How to compare your written offers

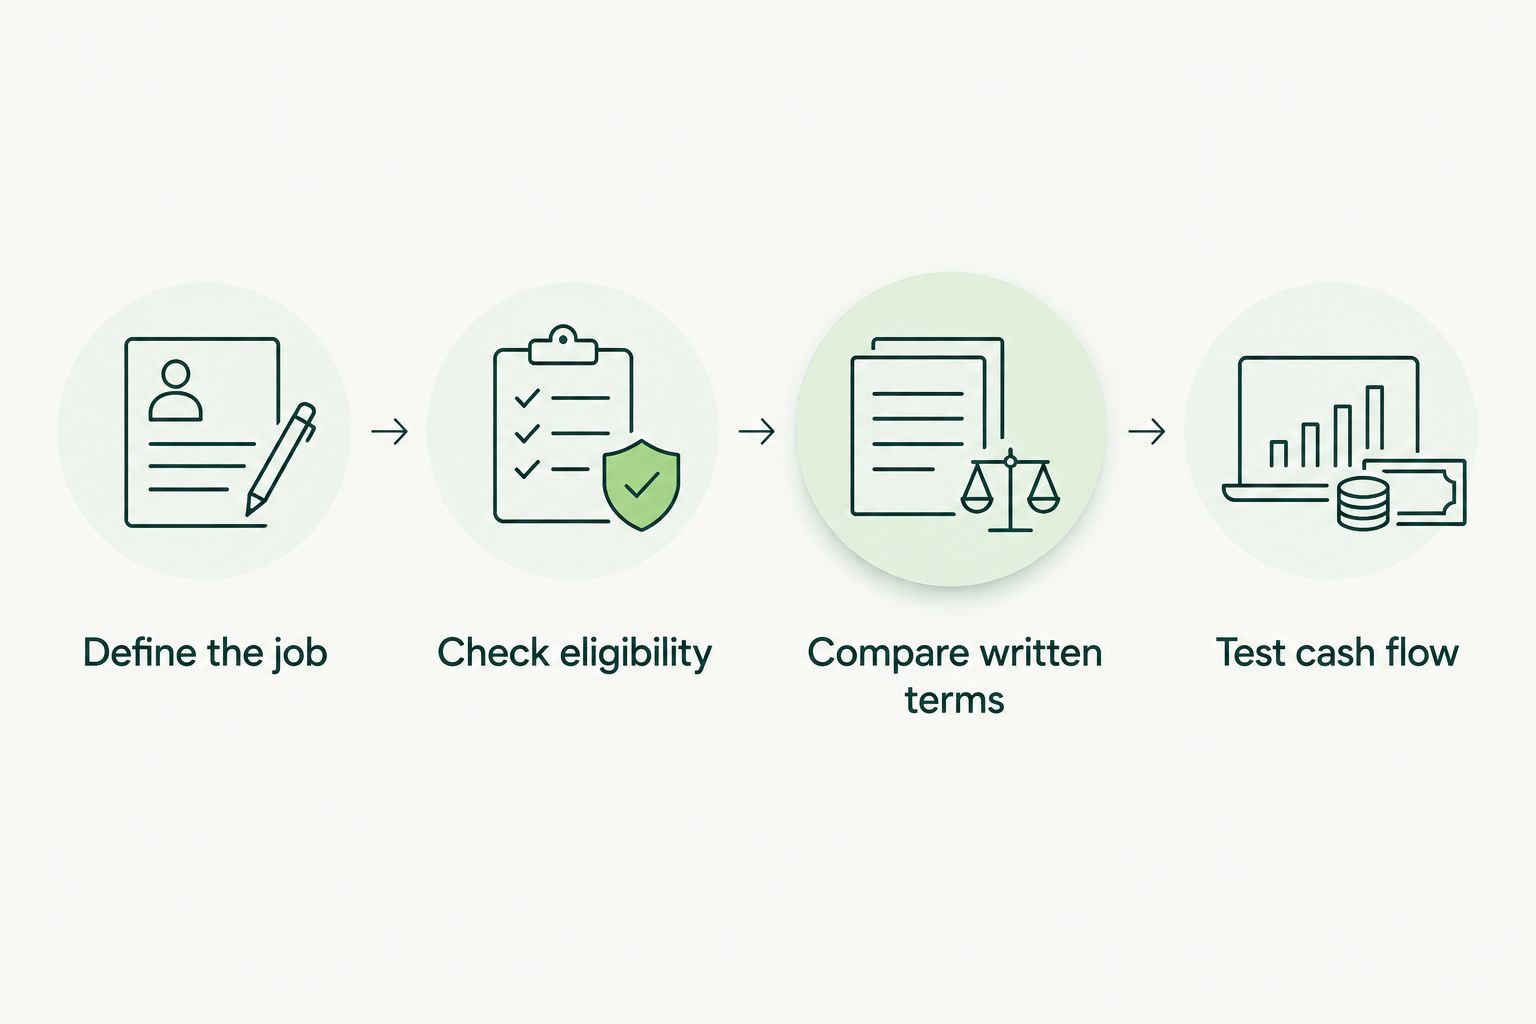
Use the same sequence for every 2026 offer. Comparing unlike figures, such as a lease payment against an advance amount, does not tell you which agreement fits.

  1. Define the job: Write down whether you need a truck, a repair, replacement equipment or operating cash. Separate expenses that serve different purposes.
  2. Check eligibility: Confirm business, revenue, credit and equipment requirements before committing to an application process.
  3. Compare written terms: Record the amount provided, total obligation, payment timing, security, guarantees and exit conditions.
  4. Test cash flow: Place repayments beside expected collections and essential expenses. Check what happens during downtime or delayed customer payments.

A workable offer leaves your business able to operate the truck after obtaining the funding. Approval alone does not answer that question.

Four steps for comparing trucking equipment funding offers

Start with the expense and finish by testing the repayment against operating cash flow.

How the options are ranked

The ranking follows funding purpose, ownership, cash flow, security, total obligation and eligibility. Equipment loans lead for ownership; leases serve planned use and replacement; credit lines address recurring expenses; merchant cash advances address operating-business funding needs.

This is a purpose-based buying guide, not a claim that one provider offers the lowest cost or approves every trucking business. Compare the actual contracts before choosing.

Which equipment financing should you choose?

Start with an equipment loan if you are buying a truck you intend to keep. Compare a lease when your priority is equipment use with a defined replacement plan.

Choose a business line of credit for recurring expenses only when you can explain how collections will repay drawings. Consider a merchant cash advance when the need is working capital and the agreement fits your revenue.

For your 2026 decision, keep the truck purchase and the operating reserve separate on paper. You need to know both how you will acquire the equipment and how you will keep it earning.

Discuss your funding options

Speak with a funding specialist about working capital for your Canadian business.

Discuss funding options

FAQ

What's the best equipment financing for trucking companies in Canada?

An equipment loan is the strongest starting point when your goal is to buy and keep a truck. Compare a lease for planned equipment use, a credit line for recurring expenses and a merchant cash advance for working capital needs.

Is leasing a truck better than financing a purchase?

Leasing is better suited to a use-and-replacement plan, while an equipment loan suits an ownership plan. Compare total obligations, return conditions, security and early exit terms before choosing.

Can I use working capital for truck equipment?

Working capital can support equipment-related business expenses when the funding agreement permits the use. Separate the equipment expense from ongoing payroll, fuel and maintenance so you can assess the full cash requirement.

Does 2M7 offer conventional equipment loans?

2M7 provides merchant cash advances and working capital, not conventional equipment loans. It is a Canadian direct funder, not a broker.

Can a newer trucking business qualify for a merchant cash advance?

The stated eligibility baseline is at least 3 months in business and $15,000 or more in monthly revenue. Meeting that baseline does not establish approval or the terms of an offer.

What should I check before signing a trucking finance agreement?

Check the total obligation, payment timing, security, guarantees and early exit terms. For leases, also check equipment return conditions and any purchase requirements.

Do flexible payments apply if customers pay trucking invoices?

Do not assume flexible payments apply to invoice-based collections. The flex-payment feature described here is only for businesses that process daily card payments.

One last thing

The truck payment is not the truck's full cash requirement. Before signing, put fuel, insurance, maintenance, payroll and a downtime allowance beside the proposed repayment. An agreement that fits only while every invoice arrives on time does not leave your business room to handle disruption.

Related guides

Read more
October 14, 2026
October 14, 2026

Best working capital loan options for small businesses 2026

Best overall for recurring cash gaps: an operating line of credit. Best for a defined expense: a short-term business loan. Best for supplier purchases: trade credit. Start your working capital loan Canada comparison with 2M7, then assess each option against your cash collection cycle—not just the amount offered.

TL;DR

  • For your working capital loan Canada search, compare repayment timing before choosing a lender, including 2M7.
  • An operating line of credit fits recurring cash gaps; a term loan fits a defined expense.
  • Invoice factoring fits unpaid customer invoices, while trade credit addresses supplier purchases.
  • A merchant cash advance requires careful review of deductions, total repayment and weaker-sales cash flow.

Why this matters

Working capital financing covers the gap between paying business expenses and collecting customer revenue. That gap matters even when your business is profitable: unpaid invoices cannot fund payroll, and unsold inventory cannot pay a supplier.

The best working capital financing matches repayment to the cash that will repay it. For your 2026 comparison, separate a temporary timing gap from an ongoing operating loss. Financing can bridge the first; borrowing alone does not fix the second.

This guide ranks financing structures, not individual lenders. A line of credit, a loan, factoring, supplier credit and a merchant cash advance solve different problems. Some are not loans at all, despite appearing alongside loans in a funding search.

What makes the best working capital financing?

Use these criteria before comparing offers. An attractive funding amount is not enough if the repayment schedule leaves your business short of operating cash.

  • Repayment fit: Match payment dates to customer collections. Frequent deductions need a different cash-flow test from monthly instalments.
  • Access pattern: Choose reusable borrowing for recurring gaps and a defined advance for a specific expense.
  • Total obligation: Identify the full amount payable, mandatory charges and any obligations that survive early repayment.
  • Security and liability: Check business security, personal guarantees and restrictions on additional borrowing.
  • Customer involvement: Establish whether customers receive payment instructions or collection contact from a financing provider.
  • Exit conditions: Read cancellation, renewal, prepayment and default provisions before accepting funds.

For any offer you consider through 2M7, apply the same criteria you would use with a bank or another financing provider. Compare written terms, not assumptions about a provider's business model.

Working capital options at a glance

The table ranks options by the cash-flow problem they address. Each structure has a distinct use case; the first entry is not automatically the right answer for every business.

1. Operating line of credit

  • Best for: Recurring timing gaps
  • Standout feature: Draw, repay and redraw within agreed terms
  • Key limitation: Access remains subject to the facility's conditions

2. Short-term business loan

  • Best for: A defined operating expense
  • Standout feature: Scheduled repayment of a defined amount
  • Key limitation: Payments continue when collections slow

3. Invoice factoring

  • Best for: Cash tied up in customer invoices
  • Standout feature: Converts eligible receivables into earlier cash
  • Key limitation: Customer involvement and recourse terms need review

4. Trade credit

  • Best for: Supplier purchases before customer collection
  • Standout feature: Delays payment for an agreed purchase
  • Key limitation: Does not provide general-purpose cash

5. Merchant cash advance

  • Best for: Businesses evaluating sales-linked funding
  • Standout feature: Repayment or collection structure tied to the agreement
  • Key limitation: Frequent deductions can pressure operating cash

For your 2026 shortlist, identify the expense first. Payroll needs usable cash; a supplier order might only need a later payment date. This distinction prevents you from comparing financing that cannot solve the same problem.
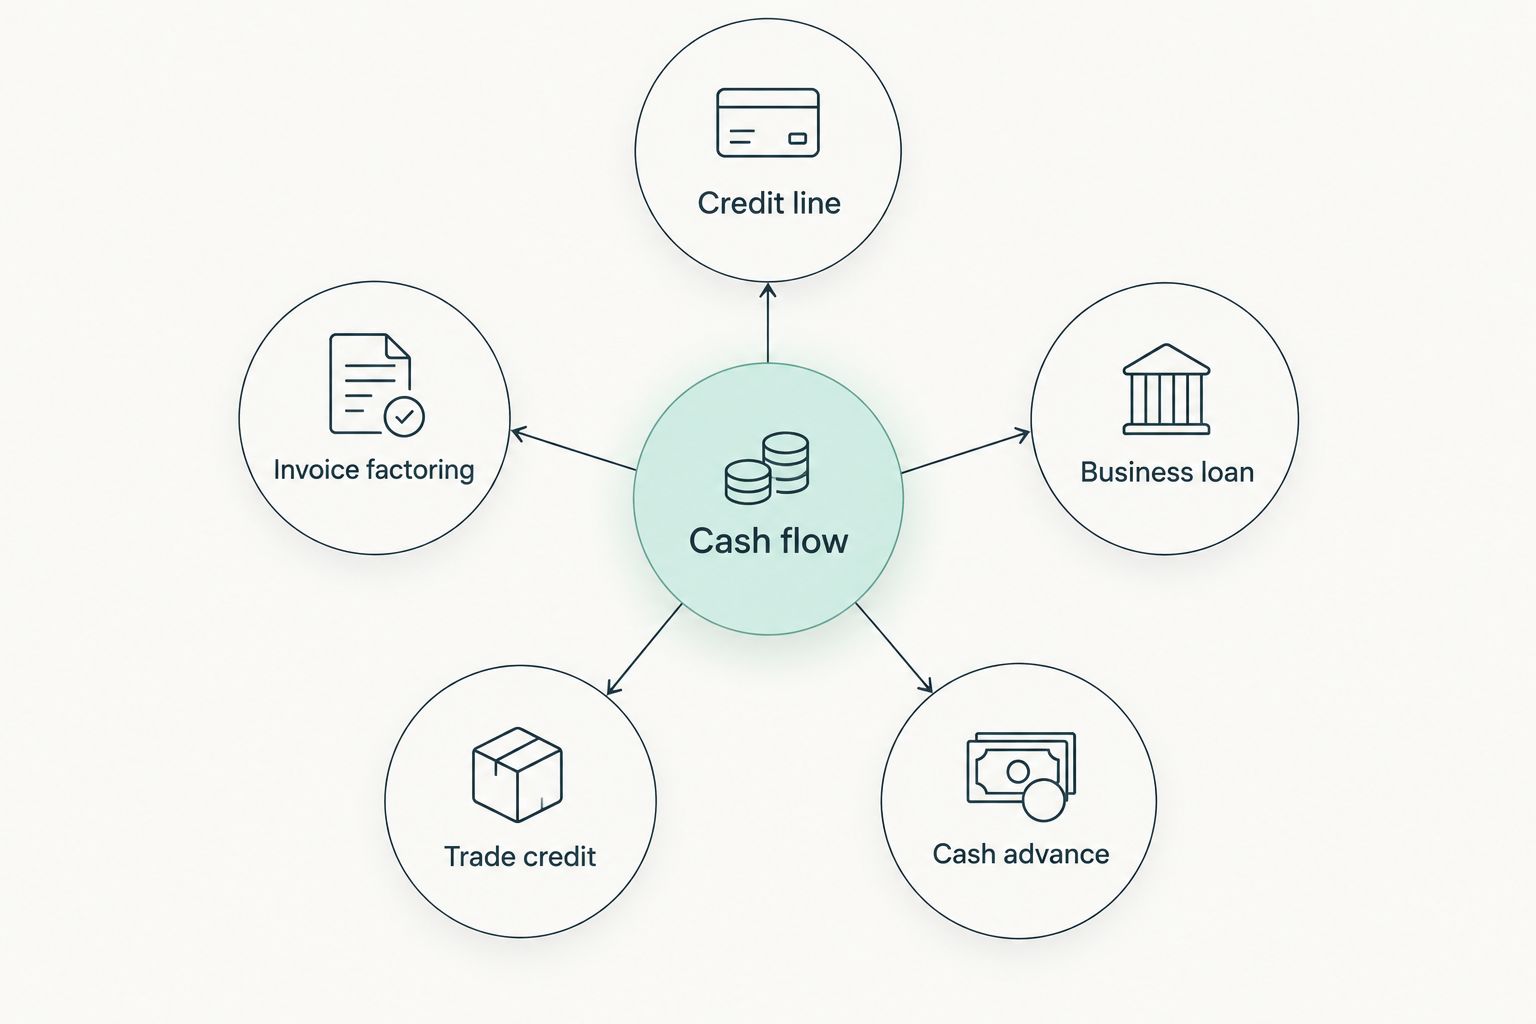
Five working capital financing structures connected to a central cash-flow need

Choose the financing structure that addresses the actual cash-flow gap.

1. Operating line of credit: best for recurring cash gaps

An operating line of credit lets you borrow within an approved limit, repay the balance and borrow again under the agreement. It suits a repeating mismatch between outgoing expenses and incoming customer payments. You do not need to treat every recurring gap as a separate borrowing decision.

Best for: Businesses with repeatable collection cycles and a clear source of repayment.

The strongest use case is timing, not permanent dependence. Draw against a temporary shortfall, then reduce the balance when customers pay. If the balance never falls, examine whether the facility is covering a structural cash deficit.

Operating line of credit pros:

  • Reusable access supports repeated working capital needs.
  • You can draw against the current gap rather than a single larger planned expense.
  • Customer collections can reduce the outstanding balance.

Operating line of credit cons:

  • Renewal, reporting and borrowing conditions require ongoing attention.
  • Security or personal guarantees can extend the consequences of default.
  • A persistent balance can hide a business that is not generating enough cash.

Ask whether access depends on receivables, inventory or financial reporting. Read the conditions governing limit changes and repayment demands rather than assuming an approved limit is unconditional.

Verdict: Buy only when your forecast shows a recurring gap and a credible route back to a lower balance.

2. Short-term business loan: best for a defined expense

A short-term business loan provides a defined borrowing amount with an agreed repayment schedule. It fits an identifiable operating need better than an open-ended shortfall. Examples include funding an inventory purchase or covering a documented seasonal cash gap.

Best for: Businesses that can connect a specific expense to a specific repayment source.

For a 2026 decision, explain the transaction in plain language: what you need to pay, when the expense produces cash and when repayments begin. A loan becomes harder to assess when its purpose is simply to keep the business account positive.

Short-term business loan pros:

  • A defined amount makes the funding purpose easy to track.
  • Scheduled payments can be incorporated into a cash forecast.
  • A set repayment endpoint helps distinguish this expense from ongoing borrowing.

Short-term business loan cons:

  • Scheduled obligations continue even when customer payments arrive late.
  • Additional funding generally requires a separate arrangement unless the agreement provides otherwise.
  • Early repayment benefits depend on the contract, not the remaining term alone.

Check whether repayments begin before the funded purchase generates cash. Also establish how the agreement calculates the amount due if you repay early; do not assume every remaining charge disappears.

Verdict: Buy for a defined expense with a repayment source; skip for an unexplained recurring deficit.

3. Invoice factoring: best for unpaid customer invoices

Invoice factoring involves selling eligible receivables to obtain cash before customers pay. Unlike a general-purpose loan assessment, the transaction centres on invoices and the customers responsible for paying them. Agreement terms determine eligibility, collections and responsibility for unpaid invoices.

Best for: Businesses whose working capital gap sits in issued customer invoices rather than future sales.

An invoice is not automatically suitable for factoring. Disputes, customer acceptance, contractual restrictions and the provider's eligibility rules all belong in the review. Separate completed, billable work from orders that have not yet become receivables.

Invoice factoring pros:

  • Connects funding to existing customer invoices.
  • Can address collection delays without waiting for the invoice payment date.
  • Provides a distinct alternative to borrowing for general operating expenses.

Invoice factoring cons:

  • Customer payment instructions or collection arrangements can change.
  • Recourse provisions can leave your business responsible for unpaid invoices.
  • Eligibility restrictions mean not every invoice produces usable funding.

Ask who contacts customers, who handles disputes and what happens if a customer does not pay. Recourse and non-recourse labels are not enough; read the covered events and exclusions.

Verdict: Buy when eligible receivables are the bottleneck; skip when your need depends on sales not yet invoiced.

4. Trade credit: best for supplier purchases

Trade credit allows you to receive goods or services and pay the supplier later under agreed terms. It addresses the purchase directly rather than depositing general-purpose financing into your business account. That makes it a separate option from a working capital loan.

Best for: Businesses whose immediate shortfall is a supplier payment rather than payroll or another cash expense.

In your 2026 planning, compare the supplier payment date with the expected customer collection date. If customers pay after the supplier is due, trade credit leaves a remaining gap. Do not mistake delayed payment for a complete funding solution.

Trade credit pros:

  • Directly addresses the timing of a supplier purchase.
  • Avoids arranging separate cash financing for that purchase when the terms fit.
  • Can align purchasing and collections when both schedules are understood.

Trade credit cons:

  • Cannot fund expenses outside the supplier arrangement.
  • Late payment can damage an important supplier relationship.
  • Limits, charges and payment conditions vary by agreement.

Get the due date and consequences of late payment in writing. If the supplier is essential to operations, include supplier continuity in your decision rather than focusing only on the immediate cash benefit.

Verdict: Buy when the purchase and collection dates align; hold when the arrangement merely pushes the same shortfall later.

5. Merchant cash advance: best for evaluating sales-linked funding

A merchant cash advance provides business funding under an agreement connected to future sales or receivables. Collection arrangements vary: examine whether deductions actually change with sales or follow a fixed schedule. The product name does not establish how your cash balance will behave.

Best for: Businesses that understand their sales pattern and can assess the agreement's collection mechanics.

Evaluate an advance separately from a conventional instalment loan. The full obligation, deduction method, reconciliation provisions and default terms matter more than a short description of access to funding.

Merchant cash advance pros:

  • Provides an alternative structure to a conventional business loan.
  • Sales-linked collection can connect payments to revenue where the agreement provides for it.
  • A defined advance can address an identifiable operating need.

Merchant cash advance cons:

  • Frequent deductions can reduce cash available for essential expenses.
  • Fixed collection amounts do not automatically shrink during weaker sales.
  • A quoted factor is not directly comparable to an annual interest rate.

Ask for the complete repayment obligation and a written explanation of deductions. If the agreement permits adjustment when sales fall, identify the request process and required evidence before relying on that provision.

Verdict: Hold until the deduction schedule passes a weaker-sales cash-flow test.

How to compare written financing offers

Build a 13-week cash forecast before accepting working capital financing. Use weekly opening cash, expected customer receipts, essential outflows, financing deductions and closing cash. This is a planning recommendation, not an approval requirement.

Then extend the review into a 12-month operating plan so renewal dates, seasonality and other borrowing obligations remain visible. A short forecast answers whether you can meet immediate payments; the longer view shows whether the funding purpose resolves or repeats.

Use these steps for each written offer:

  1. Define the gap. State the expense and the event expected to repay the funding.
  2. Map collections. Separate expected receipts from cash already collected.
  3. Add repayments. Enter deductions on their actual scheduled dates.
  4. Test delays. Model a 30-day customer payment delay as a planning scenario, not a prediction.
  5. Read obligations. Check guarantees, security, default triggers and exit terms.

When assessing a 2M7 working capital financing offer, use the same forecast and questions. A comparison only becomes useful when competing agreements address the same funding need and expose their full obligations.

Review your financing starting point

Use the cash-flow checklist before discussing a working capital financing offer.

Visit 2M7

How these options are ranked

The ranking prioritizes repayment fit, repeated access, a defined funding purpose and visibility into obligations. It does not score providers on approval speed, eligibility or customer satisfaction.

An operating line of credit ranks first for recurring timing gaps because its reusable structure matches that problem. The remaining options earn separate use-case positions: a specific expense, unpaid invoices, supplier purchases and sales-linked funding. Choose by the problem, not the position.

Which working capital option should you choose?

For an undecided business owner in 2026, start with an operating line of credit if the shortfall repeats and customer collections can reduce the balance. Choose a short-term business loan when the expense and repayment source are defined.

Use invoice factoring when issued invoices are holding up cash. Discuss trade credit when the immediate need is a supplier purchase. Evaluate a merchant cash advance only after understanding how its deductions affect essential operating payments.

For a working capital loan Canada comparison, use 2M7 as a starting point—not a substitute for reviewing written repayment terms. Keep the final decision tied to your forecast. This guide explains financing structures and does not replace advice on your business's contractual or financial obligations.

FAQ

What's the best working capital loan in Canada for a small business?

An operating line of credit is the strongest starting point for recurring cash-flow timing gaps. A short-term business loan fits a defined expense better; the right choice depends on repayment terms and the cash that will repay it.

Is a business line of credit better than a working capital loan?

A business line of credit is better suited to repeated borrowing and repayment, while a term loan suits a defined funding amount. Compare access conditions and repayment obligations before choosing either structure.

Can invoice factoring help if customers pay late?

Invoice factoring can turn eligible unpaid invoices into earlier cash. Check customer involvement, invoice eligibility and who carries responsibility if an invoice remains unpaid.

Is trade credit the same as a business loan?

Trade credit is not the same as a general-purpose business loan. It delays payment to a supplier under agreed terms and does not provide cash for unrelated operating expenses.

What should I check before accepting a merchant cash advance?

Check the full repayment obligation, deduction schedule and adjustment provisions before accepting a merchant cash advance. Test whether essential expenses remain covered during weaker sales or delayed customer payments.

Do working capital loans require a personal guarantee?

Personal guarantee requirements depend on the provider and agreement. Read the actual guarantee and security provisions rather than assuming they apply—or do not apply—to an entire financing category.

How should I compare a 2M7 offer with another financing offer?

Compare a 2M7 working capital financing offer using the same funding purpose and cash forecast as any competing offer. Review total obligations, repayment dates, guarantees, security, early repayment terms and default provisions.

One last thing

Repayment timing can defeat an otherwise sensible funding plan. A forecast showing enough cash at month-end can still contain a shortfall before payroll or a supplier payment falls due. Review the dates—not just the totals—before signing.

Read more
October 19, 2026
October 19, 2026

Best business lines of credit for small businesses in Canada 2026

Best overall for collateral-backed borrowing: a secured business line of credit. Best without pledged business assets: an unsecured line. Best alternative for eligible businesses comparing merchant cash advances: 2M7, a direct funder, not a line-of-credit provider. This 2026 guide ranks funding structures by business need rather than naming a bank winner without comparable offers.

TL;DR

  • A secured business line of credit suits established businesses willing to pledge acceptable collateral.
  • An unsecured business line of credit avoids specified collateral, but personal guarantees can still apply.
  • Receivables-backed credit suits businesses with eligible unpaid customer invoices.
  • 2M7 offers merchant cash advances, not revolving credit; compare the repayment structure before choosing.

What makes the best business line of credit?

  • Reusable access: You can draw, repay and borrow again within the approved limit, subject to the agreement.
  • Cash-flow fit: Required payments leave enough money for payroll, suppliers and taxes.
  • Clear obligations: You understand interest, fees, guarantees and collateral requirements.
  • Usable capacity: The amount actually available matches your operating needs.
  • Acceptable conditions: Reporting, renewal and cancellation terms fit how your business operates.

Business credit options at a glance

1. Secured business line of credit

  • Best for: Established businesses with acceptable collateral
  • Standout feature: Revolving access supported by pledged assets
  • Key limitation: Collateral is exposed if you default

2. Unsecured business line of credit

  • Best for: Businesses seeking credit without specified pledged assets
  • Standout feature: Revolving access without designated collateral
  • Key limitation: A personal guarantee can still apply

3. Receivables-backed line of credit

  • Best for: Businesses selling to customers on payment terms
  • Standout feature: Borrowing availability tied to eligible invoices
  • Key limitation: Availability changes with receivables eligibility

4. 2M7 merchant cash advance

  • Best for: Eligible businesses considering an alternative to revolving credit
  • Standout feature: Direct funding for working-capital needs
  • Key limitation: Not a reusable credit facility

Why this matters

A business line of credit addresses a timing problem: expenses arrive before customer payments, and you need access to funds between the two. A revolving facility lets you borrow again after repayment, subject to its terms. A merchant cash advance works differently and should not be treated as an interchangeable product.

For your 2026 comparison, start with the problem you need to solve. Recurring supplier payments, outstanding invoices and a defined equipment purchase call for different conversations. The best option is the one whose repayment obligations fit your cash flow, not simply the one offering the largest limit.

1. Secured credit: best for businesses with collateral

A secured business line of credit gives you revolving access to funds against collateral the lender accepts. That security can include business assets, depending on the agreement. You draw what you need within the available limit and restore borrowing capacity through repayment, subject to the facility's conditions.

Best for: Established businesses that need recurring working capital and are comfortable pledging assets.

Secured credit pros

  • Reusable borrowing suits repeated cash-flow gaps rather than a single purchase.
  • An approved facility provides access without a separate application for every draw, subject to its terms.
  • Collateral gives the lender a defined source of security when assessing the application.

Secured credit cons

  • Pledged assets are exposed if the business defaults.
  • Security requirements can complicate future financing involving the same assets.
  • Reporting obligations and lender reviews can affect continued access.

What to check: Ask exactly which assets secure the facility. A security interest covering broad business assets has different consequences from security over one identified asset. Also ask whether a personal guarantee is required; business collateral does not automatically remove personal obligations.

Do not choose secured credit just because your business owns equipment or property. First check whether pledging those assets restricts another financing arrangement you need.

Verdict: Hold until the collateral, guarantee and renewal terms are clear. Secured credit is the default comparison point for established businesses willing to provide security, not an automatic recommendation for every asset-owning business.

2. Unsecured credit: best without specified collateral

An unsecured business line of credit provides revolving access without specified pledged collateral. The lender still evaluates the business and the application. Unsecured does not mean approval without underwriting, and it does not necessarily mean the owner has no personal responsibility.

Best for: Businesses seeking reusable working capital without assigning specified assets as collateral.

Unsecured credit pros

  • You avoid pledging specified business assets under the facility.
  • Revolving access supports repeated borrowing and repayment.
  • Keeping assets outside a specific security arrangement can preserve flexibility for other financing discussions.

Unsecured credit cons

  • A personal guarantee can still create obligations for the owner.
  • The approved limit and application requirements depend on the lender's assessment.
  • Renewal, review and cancellation provisions still matter.

What to check: Ask the lender to explain what unsecured means in the actual agreement. Confirm whether guarantees, account conditions or other obligations apply. Do not rely on the product name alone.

For a 2026 application, compare the usable limit with your largest expected cash-flow gap. A facility that cannot cover that gap does not solve your operating problem, even if its collateral requirements are attractive.

Keep the distinction between qualification and suitability clear. Approval tells you the lender accepts the application; it does not establish that the required payments fit your business.

Verdict: Hold until you understand the personal guarantee and available limit. Choose unsecured revolving credit for its structure, not because the word unsecured sounds consequence-free.

3. Receivables-backed credit: best for unpaid invoices

A receivables-backed line of credit links borrowing availability to eligible customer invoices. The lender assesses which receivables qualify and applies the agreement's borrowing rules. This differs from receiving an unrestricted limit based only on the business's overall profile.

Best for: Businesses that invoice customers on payment terms and have receivables a lender accepts.

Receivables-backed credit pros

  • The facility connects working-capital access to unpaid customer invoices.
  • Revolving borrowing can support the gap between delivering work and collecting payment.
  • Availability can reflect changes in qualifying receivables, subject to the agreement.

Receivables-backed credit cons

  • Overdue, disputed or otherwise ineligible invoices can reduce borrowing availability.
  • Reporting and invoice administration create ongoing work.
  • Customer concentration rules can limit how much of the receivables balance qualifies.

What to check: Ask how the lender treats overdue invoices, customer disputes and sales concentrated with one customer. Then calculate borrowing availability using those rules, rather than assuming every dollar invoiced creates an equal amount of credit.

A growing invoice balance does not automatically mean more usable funding. If the additional invoices fail the eligibility rules, the facility will not expand in the way you expect.

Also distinguish a receivables-backed line from factoring. A credit facility and an arrangement involving the sale of invoices have different contractual structures. Ask who collects customer payments and what happens when a customer does not pay.

Verdict: Hold until an invoice-level review confirms usable borrowing capacity. This option fits an invoicing business only when its receivables qualify.

4. 2M7: best for comparing a merchant cash advance alternative

A merchant cash advance is an alternative funding structure, not a business line of credit. It does not give you a revolving limit that automatically replenishes after repayment. Treat it as a separate decision when your business needs working capital.

2M7 merchant cash advances suit eligible Canadian businesses comparing direct funding with revolving credit. The company is a direct funder, not a broker, serving businesses operating for at least 3 months with $15,000 or more in monthly revenue. Its stated uses include payroll, inventory, equipment and cash-flow gaps.

Best for: Eligible small and mid-sized Canadian businesses considering working capital outside a revolving credit facility, including businesses with less-than-perfect credit.

Merchant cash advance pros

  • You discuss funding with a direct funder rather than a broker.
  • The stated eligibility includes businesses with at least 3 months of operating history.
  • Working-capital uses include payroll, inventory and equipment.
  • The fixed cost of capital is disclosed before signing and does not change based on repayment duration.

Merchant cash advance cons

  • Repayment does not automatically restore a reusable credit limit.
  • Eligibility requirements still apply; meeting initial thresholds is not an approval promise.
  • Flex payments apply only to businesses processing daily card payments.

What to check: Confirm the total repayment obligation, collection method and effect on operating cash flow. If flexible payments matter to your decision, establish whether your business meets the daily card-payment condition before comparing that feature with other offers.

Verdict: Skip if you specifically need revolving credit. Consider this structure when you need defined working capital and the repayment obligations fit your business.

How to compare written offers in 2026

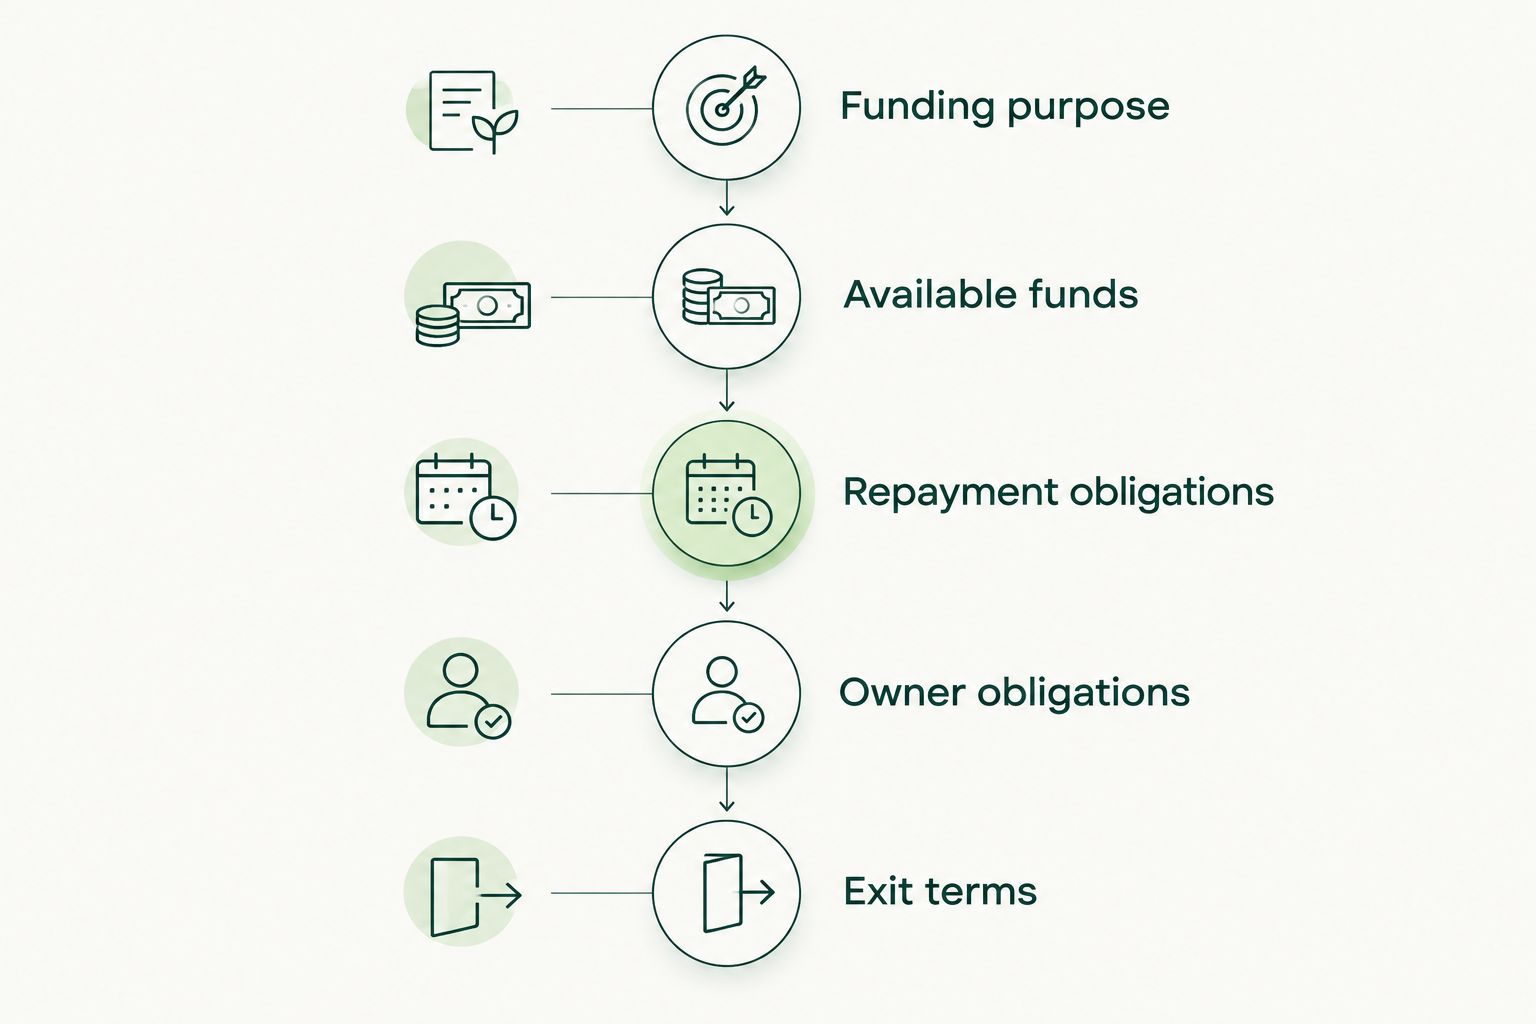
A useful funding comparison follows the money through your business. Check these elements in order before deciding which offer fits.

  1. Funding purpose: Identify the expense and whether it recurs. Separate an ongoing operating gap from a single purchase.
  2. Available funds: Confirm what you can actually draw, including restrictions tied to collateral or eligible invoices.
  3. Repayment obligations: Map required payments against expected customer receipts and essential operating expenses.
  4. Owner obligations: Identify guarantees, pledged assets and reporting duties before signing.
  5. Exit terms: Read renewal, cancellation and early-repayment provisions, including any conditions attached to them.

Do not compare a revolving credit limit directly with the amount of an advance. One describes access that can be reused under an agreement; the other describes funding that does not automatically replenish.

Five checks for comparing funding offers, from funding purpose to exit terms

Compare obligations and usable access, not just the headline funding amount.

Build your comparison from written terms rather than a headline claim. If an important condition is unclear, ask the provider to explain it before you commit. Keep the explanation with the agreement so your operating decisions reflect the same terms.

How these options are ranked

This 2026 ranking prioritises revolving access, cash-flow fit, clear obligations, usable capacity and acceptable conditions. Secured credit comes first for established businesses willing to pledge collateral; unsecured credit serves a different need, while receivables-backed credit depends on qualifying invoices.

The merchant cash advance sits separately because it is not a line of credit. This is a structure-based buying guide, not a claim that one lender offers the best terms to every Canadian applicant. Your written offer determines the final comparison.

Which business line of credit should you choose?

Start with a secured business line of credit if your established business needs reusable funding and can accept the collateral obligations. Compare unsecured credit when you want to avoid specified pledged assets. Investigate receivables-backed credit when unpaid customer invoices drive the funding gap.

If you do not need reusable access, compare a merchant cash advance separately. Ask a funding specialist to explain the repayment structure in plain language. Do not choose a non-revolving product expecting it to behave like a credit line.

Discuss your funding options

Speak with a funding specialist about working capital and whether a merchant cash advance fits your business.

Discuss funding options

FAQ

What's the best business line of credit for a small business in Canada?

The best fit depends on collateral, cash flow and the need for reusable access. Start with secured credit if you can accept asset security, unsecured credit if you want to avoid specified collateral, or receivables-backed credit if eligible invoices support the facility.

Is an unsecured business line of credit free of personal obligations?

No. An unsecured business line of credit can still require a personal guarantee. Read the guarantee and other obligations rather than treating unsecured as a promise of no personal responsibility.

Does repaying a business line of credit let me borrow again?

A revolving business line of credit generally restores borrowing availability as you repay, subject to the agreement. Limits, lender reviews and other conditions still govern what you can draw.

Is a merchant cash advance the same as a business line of credit?

No. A merchant cash advance does not provide a revolving limit that automatically replenishes after repayment. Compare its repayment obligations separately from a reusable credit facility.

Can a newer Canadian business consider 2M7 funding?

2M7 serves businesses operating for at least 3 months with $15,000 or more in monthly revenue. Those are initial eligibility criteria, not an approval promise, and its product is a merchant cash advance rather than a business line of credit.

What should I ask before signing a business credit agreement in 2026?

Ask about usable borrowing availability, repayment obligations, guarantees, collateral, reporting, renewal and cancellation. Request clarification of anything that could restrict access or affect your operating cash flow.

Is receivables-backed credit the same as invoice factoring?

No. A receivables-backed credit facility and an arrangement involving the sale of invoices have different contractual structures. Confirm invoice ownership, collection responsibilities and what happens if a customer does not pay.

One last thing

A credit limit is not the same as money you can safely spend. Before accepting any 2026 offer, place its required payments alongside payroll, tax obligations and supplier commitments. If the funding solves one payment gap but creates another, change the amount or structure before signing.

Related guides

Read more