ClickCease

Funding for Businesses with Bad Credit History

Funding for Businesses with Bad Credit History

nding for Businesses with Bad Credit History
24
Mar 2023
11
Aug 2026

Businesses need a robust cash flow to sustain their operations and generate profits. At times they may need to borrow funds to acquire resources, maintain operations, or grow.

Unfortunately, various factors can adversely affect a business's ability to borrow from traditional financial institutions. These factors include having a poor credit history or insufficient credit history, missed or late payments, high debt-to-service ratio, bankruptcy, records of default, or simply being a relatively new business.

However, there are many funding solutions available for Small Businesses that don’t fit the bank or credit Union model. These options are:

1. Merchant Cash Advance

A merchant cash advance is a financing option that offers businesses a lump sum cash payment in exchange for a percentage of their future credit card or debit card sales. This type of financing is best suited for businesses that require quick cash and have a high volume of credit or debit card sales.

The primary advantage of a merchant cash advance is the speed and ease of accessing immediate cash funding. The process typically takes only a few days, and the funds become available within a short period. Business owners should take into account that while merchant cash advance is a convenient cash flow instrument and allows you to get funding within a few days, it may come with higher fees and interest rates due to their quick access to cash.

2. Invoice Factoring or Cheque Factoring

Invoice factoring, also known as cheque factoring, is a financing option that enables businesses to utilize their outstanding invoices in exchange for a cash advance that is immediately available. The lender collects payment from the business's customers and pays the business the remaining balance minus the financing cost. This type of financing is ideal for businesses with bad credit history since their ability to borrow is based on the creditworthiness of their invoice customers rather than the borrower.

Businesses with long-term contracts, high-value invoices, or those needing cash to immediately purchase materials to fulfill high-value invoices should consider this type of bridge financing. Manufacturing, construction, transportation, and wholesale/distribution are businesses that can benefit from this type of financing to meet their immediate cash flow needs. The main advantage of invoice factoring is that the lender typically assumes responsibility for collecting payment from the invoice customers or payers. This can free up valuable time and resources for the business to focus on other aspects of their operations.

Furthermore, businesses with long payment cycles, delayed payments, or long-term contracts that involve milestone payments can obtain the necessary cash to expand or continue operating their businesses immediately. Similarly to merchant cash advance companies, factoring lenders may charge a high fee for assuming the risk of collecting on the invoice and the time gap until the invoice is due for payment.

3. B-Lender Loans

B-Lender loans are non-traditional financing options provided by private equity firms or online lenders. These lenders are often willing to lend to businesses with bad credit or little credit history for various purposes. They understand the complexity and cash flow requirements of small businesses and work with them regularly. This type of loan comes in various sizes and forms, depending on the business needs and the business entity's qualifications and lending risks.

B-Lender loans are a great financing option for start-ups, small businesses, seasonal revenue businesses, or those in urgent need of short-term financing. Traditional lenders typically require creditworthiness, good credit history, and collateral, but B-Lenders often have significantly more flexibility. These lenders are specialized in dealing with the complexity of newer and smaller businesses and can provide loans with less stringent due diligence processes and quicker turnaround times to meet business needs.

However, it is highly advisable for borrowers to understand the terms of the loan and carefully review the terms and conditions before accepting them. B-Lender loans are less standardized and customizable and can vary significantly in terms such as repayment, interest, default events, settlement, and legal jurisdiction. Businesses should also be aware that B-Lender loans may come with higher fees and interest rates due to their higher risk tolerance.

B-Lender loans can be a great option for businesses that are just starting or facing challenges with traditional lenders. These loans can provide flexibility, speed, and customized financing solutions to meet their specific needs. However, careful consideration of the terms and conditions and full understanding of the associated costs are crucial before committing to this type of financing.

4. Instant Payday Loans

Instant payday loans are short-term loans that can be used to cover unexpected expenses or emergencies. They are easy to obtain and are often offered by online lenders. Borrowers may receive access to immediate relief cash within hours, thanks to the quick and standardized approval process of the lenders that provide these loans. Instant payday loans are suitable for individuals with emergency cash needs or who need access to immediate cash to cover unexpected expenses.

Some typical uses for instant payday loans include medical bills, car repair bills, and home repair bills. These loans can offer immediate cash relief to ensure a person has the cash to cover daily living needs to continue working and earning money. Payday loans can be useful for individuals who have low credit scores or limited credit history and may not qualify for traditional loans. Borrowers should know that instant payday loans typically have high interest rates and fees for their ease of access and quick approval process. The repayment period is often within two to four weeks. As these loans can be accessed quickly and easily with minimal documentation requirements, these could be beneficial for individuals who need immediate cash and don't mind the associated fees.

‍

The Right Option For Your Busineness

There are various types of non-traditional lending and financial services available to businesses and consumers in Canada. These services can provide cash relief for a variety of situations, depending on the borrower's needs and qualifications. Merchant cash loans are suitable for businesses with high credit or debit card transaction volume and immediate cash needs. Invoice or cheque factoring can benefit businesses with valuable invoices with longer repayment terms. B-Lender loans are a great option for start-ups or small businesses with an immediate cash need to expand or maintain operations. Instant payday loans can provide relief for individuals with unexpected or emergency cash needs.

Overall, non-traditional lending and financial services can provide valuable solutions for businesses and consumers with unique financial needs. It is also vital to approach them with caution and careful consideration of the associated costs and repayment terms. With the right lender and loan terms, these financial services can help businesses and individuals overcome cash flow challenges and achieve their financial goals.

Related articles

May 26, 2021
September 20, 2026

5 Reasons Why Successful Businesses Also Borrow Money

There's a huge misconception in the world of business. People tend to think that if a company (that's not a startup) has to borrow money, it's not successful. Yes, in certain situations, you do need some capital to get up and running from a few bad months. However, usually, it isn't bad for your company. It can be a huge boost for your business and take your sales to a new height that you didn't know existed. Here are five reasons why successful businesses needs to borrow money.

Meet Consumer Demands

If you're running a successful business, you're going to scale over time. Your customers will increase, and your current production capacity won't meet your future demands. Scaling is an important part of the journey, and if you don't speed up production, the sign that says 'out of stock' will run your enterprise into the ground. Taking a merchant cash advance (MCA) could be a great way to upgrade equipment and start meeting consumer demands. It does cost you money upfront, but in the long run, it'll boost your profits tenfold. For a closer look at how this type of funding fits a growing business, read using a merchant cash advance to grow your business.

Stepping Away from a Rough Patch

We mentioned COVID-19 a while ago, and it is a major reason why companies need to be open to the idea of borrowing money. Millions of businesses globally shut down because either their services weren't required by the public or they couldn't maintain enough profits to stay above water. If your company struggled to find ground but still made it to the early post-COVID era we're in right now, you're lucky. However, things might not be such food to you if you can't get yourself back to a certain level of stability. By taking a merchant cash advance, you might be able to hire new personnel, find new contractors to work with, spend more on advertising, and get back to work!

Making Payments on Time

Even some of the top businesses in the world need raw materials to make their products. And, most of the time, payments from customers take months until they're in the pocket of the finance department. To make sure you make all your payments on time, an MCA will help you keep the wheel spinning, and since you already have the money needed to pay it back, you're good to go.

Keeping Up With Competition

No matter what you sell, there's probably some other businesses out there that has been in the same industry for longer than you have. This means that they have a stable grip on the market and have a better cash flow to scale their business. Taking a merchant cash advance is like a quick hack to catch up to your competition and speed up sales much quickly as compared to the other, more traditional routes.

Reducing Personal Investments

If you’re running a small to medium business, it’s always tempting to put in all your personal savings to keep the business afloat. Building a cash reserve is a good way to keep financial problems at bay. However, a recommendable way to save yourself from the pitfall of personal investments is to borrow money. By bringing in the cash you need from other places, you’re keeping your bank account safe and sound.

Closing Thoughts

The word 'debt' is not the final nail in the coffin for your company. With proper planning, it can help you reach heights that you never imagined. That is where we come in. 2M7 Financial Solutions is a company that offers merchants cash advances, which you can return from a specific percentage of your sales. If you're looking for a reliable company to help you outshine your competition, request a quote, we will be happy to assist you.

Read more
October 16, 2026
October 16, 2026

Best alternative business lenders in Canada 2026

Best for a direct merchant cash advance: 2M7. Best for development-bank financing: BDC. Best for rural business support: Community Futures. This 2026 guide compares named funders and specialist financing categories so you can match your business need to the right repayment structure.

TL;DR

  • For alternative business lenders Canada-wide, compare funding purpose and repayment structure before choosing a provider.
  • 2M7 suits operating Canadian businesses seeking a direct merchant cash advance, not a conventional business loan.
  • BDC and Community Futures serve different financing needs; check the specific programme before applying.
  • Invoice factoring fits receivables gaps; equipment financing fits asset purchases. Neither replaces a full cash-flow assessment.

Why this matters

Alternative business funding is not one product. A merchant cash advance, a business loan, invoice factoring and equipment financing create different obligations, even when they support the same business expense.

Choose the funding structure before choosing the provider. Otherwise, you risk comparing offers that solve different problems. An invoice-backed arrangement addresses unpaid customer invoices; an equipment agreement addresses an asset purchase. Neither is automatically the right way to cover payroll.

This shortlist separates those purposes. It does not name a cheapest provider because the right comparison requires written offers for your business, not a headline claim.

What makes the best alternative business lender?

Use these criteria to assess your 2026 shortlist before submitting applications:

  • Product fit: Identify whether you need a merchant cash advance, a loan, invoice factoring or equipment financing. Ask what agreement you will actually sign.
  • Eligibility fit: Check operating history, revenue requirements, location and any conditions attached to the funding programme.
  • Repayment fit: Understand the payment schedule, collection method and what happens when revenue falls or customers pay late.
  • Contract clarity: Review the amount you receive, your full contractual obligation, security requirements and default provisions together.
  • Provider role: Establish whether you are dealing with the funder, a broker or a referral service. Know who makes the decision and services the agreement.
  • Purpose fit: Match the obligation to the expense. A recurring operating shortfall needs a different assessment from a productive asset purchase.

A strong offer passes all these checks. Approval alone does not establish that the funding works for your business.

Alternative business funding options at a glance

The 2026 comparison below combines named organisations with specialist provider categories. Category entries are not endorsements of every business operating within them.

1. 2M7

  • Best for: Direct merchant cash advances for operating businesses
  • Standout feature: Direct funder rather than a broker
  • Key limitation: Minimum operating history and monthly revenue requirements apply

2. BDC

  • Best for: Businesses considering development-bank financing
  • Standout feature: Canadian business development bank
  • Key limitation: The specific financing product must match your purpose and eligibility

3. Community Futures

  • Best for: Rural businesses seeking local financing and support
  • Standout feature: Community-based business development organisations
  • Key limitation: Service areas and local programme requirements matter

4. Invoice factoring providers

  • Best for: Businesses waiting on eligible customer invoices
  • Standout feature: Funding tied to receivables
  • Key limitation: Depends on invoices, customers and the factoring agreement

5. Equipment financing providers

  • Best for: Businesses acquiring equipment
  • Standout feature: Funding structured around an asset
  • Key limitation: Equipment-focused agreements do not provide unrestricted working capital

1. 2M7: best for a direct merchant cash advance

2M7 provides merchant cash advances and working capital directly to Canadian small and mid-sized businesses. It is not a broker, and its merchant cash advance is not a conventional business loan.

The stated eligibility baseline is at least 3 months in business and $15,000 in monthly revenue. Businesses with less-than-perfect credit are within its stated customer scope, but meeting the baseline does not establish approval.

Best for: An operating Canadian business considering a direct merchant cash advance for payroll, inventory, equipment or a cash-flow gap.

2M7 pros:

  • You deal with the direct funder rather than a funding broker.
  • The stated customer scope includes businesses with less-than-perfect credit.
  • Working capital can support the business uses listed above.

2M7 cons:

  • Businesses below the stated operating-history or revenue thresholds do not meet the baseline.
  • Flex payments apply only to businesses that process daily card payments.
  • The suitability of an advance still depends on the business's ability to meet the agreement.

The company reports funding more than 5,000 Canadian businesses. That establishes experience, not a prediction about your application or a substitute for reviewing your contract.

Before signing, ask how payments are collected and how the obligation fits your quieter trading periods. Verdict: Hold until the written agreement and your cash-flow forecast support the commitment.

2. BDC: best for development-bank financing

BDC is Canada's business development bank. Include BDC when you want to assess business financing through an organisation with a development mandate rather than treating every non-bank search result as the same kind of provider.

Start with the purpose of your application. Funding an expansion, buying equipment and supporting working capital require different conversations, even when the same organisation offers several financing routes.

Best for: A Canadian business assessing development-bank financing for a defined business purpose.

BDC pros:

  • Its role as Canada's business development bank is clearly established.
  • You can begin the discussion with the business objective rather than a generic funding request.
  • It provides a useful comparison point when assessing other financing structures.

BDC cons:

  • BDC's name alone does not tell you whether a particular financing product fits your business.
  • You still need to assess the specific eligibility conditions, documentation and repayment obligation.

Do not assume that a development mandate means automatic qualification or that every product serves every business stage. Request the requirements for the actual financing under discussion.

Verdict: Hold until you identify a suitable product and confirm the application requirements.

3. Community Futures: best for rural business support

Community Futures organisations provide business development support and financing in rural communities. The relevant starting point is the organisation serving your location, not a national assumption about one standard offer.

For a rural business owner, local programme fit belongs near the top of the assessment. Confirm the service area, eligible business activities and intended use of funds before building an application around this route.

Best for: A rural Canadian business seeking locally delivered business financing and support.

Community Futures pros:

  • The community-based model gives rural businesses a distinct starting point.
  • Financing and business support can be considered together.
  • Local programme information helps you assess geographic eligibility early.

Community Futures cons:

  • Your business must fit the relevant service area and programme requirements.
  • An offer or condition described by one local organisation does not establish the terms elsewhere.

Ask the local organisation which programmes match your business stage and intended expense. Keep that answer separate from any general information about the wider network.

Verdict: Hold until the local organisation confirms programme and geographic fit.

4. Invoice factoring providers: best for unpaid customer invoices

Invoice factoring involves selling receivables to a factoring provider under an agreement. It addresses money tied up in eligible customer invoices rather than funding based solely on your business's general sales outlook.

This makes factoring a specific tool, not a general substitute for every working-capital need. The invoices, the customers responsible for paying them and the contract all matter.

Best for: A business with eligible business-to-business receivables that needs to address a gap between invoicing and customer payment.

Invoice factoring pros:

  • The funding need connects directly to existing receivables.
  • You can assess the arrangement against identifiable invoices and customer payment dates.
  • The structure distinguishes an invoice-collection gap from a lack of underlying sales.

Invoice factoring cons:

  • A business without eligible invoices cannot use this structure for that purpose.
  • Customer notification and collection arrangements require review.
  • Recourse provisions can leave responsibilities with your business if customers do not pay.

Ask who contacts customers, who handles collections and what happens if an invoice is disputed. Do not assume that selling an invoice removes every payment-related obligation.

Verdict: Hold until invoice eligibility, customer handling and recourse terms are clear.

5. Equipment financing providers: best for an asset purchase

Equipment financing supports the acquisition of business equipment through arrangements such as equipment loans or leases. It belongs on your shortlist when the asset itself is the reason you need funding.

Separate the equipment decision from the financing decision. First establish that the asset serves a business need; then compare the obligations attached to acquiring it.

Best for: A business purchasing or leasing equipment for a defined operational purpose.

Equipment financing pros:

  • The financing purpose connects to a specific asset.
  • Equipment loans and leases provide different structures to evaluate.
  • You can compare the payment obligation with the equipment's expected business use.

Equipment financing cons:

  • An equipment-focused agreement does not solve unrelated payroll or inventory needs.
  • Ownership, maintenance responsibilities and end-of-term provisions differ by agreement.
  • Security and default provisions need review before you commit the asset or business.

Check whether you own the equipment during the agreement and what happens at its end. A payment figure alone does not answer either question.

Verdict: Hold until the ownership structure and full agreement match the asset's intended use.

How these options were ranked

This 2026 ranking follows distinct business needs: direct merchant cash advances, development-bank financing, rural support, receivables and equipment. It is not a ranking of approval likelihood or a claim that one provider offers the best terms to every applicant.

The order puts a direct working-capital option first, then separates routes whose suitability depends on a development mandate, geography, invoices or an asset. Use the criteria above to change the order for your business.

A rural equipment purchase, for example, deserves a different shortlist from an urban retailer's inventory requirement. The business purpose decides which entry moves to the top.

How to compare the offers you receive

Before choosing from alternative business lenders in Canada in 2026, put each written offer through the same review:

  • Purpose: State the expense the funding will cover and why the business needs it.
  • Repayment source: Identify the revenue or receivables expected to support the obligation.
  • Total obligation: Read the complete amount owed, payment mechanics and any conditional charges together.
  • Contract review: Check security, guarantees, default provisions and early-payment conditions before signing.
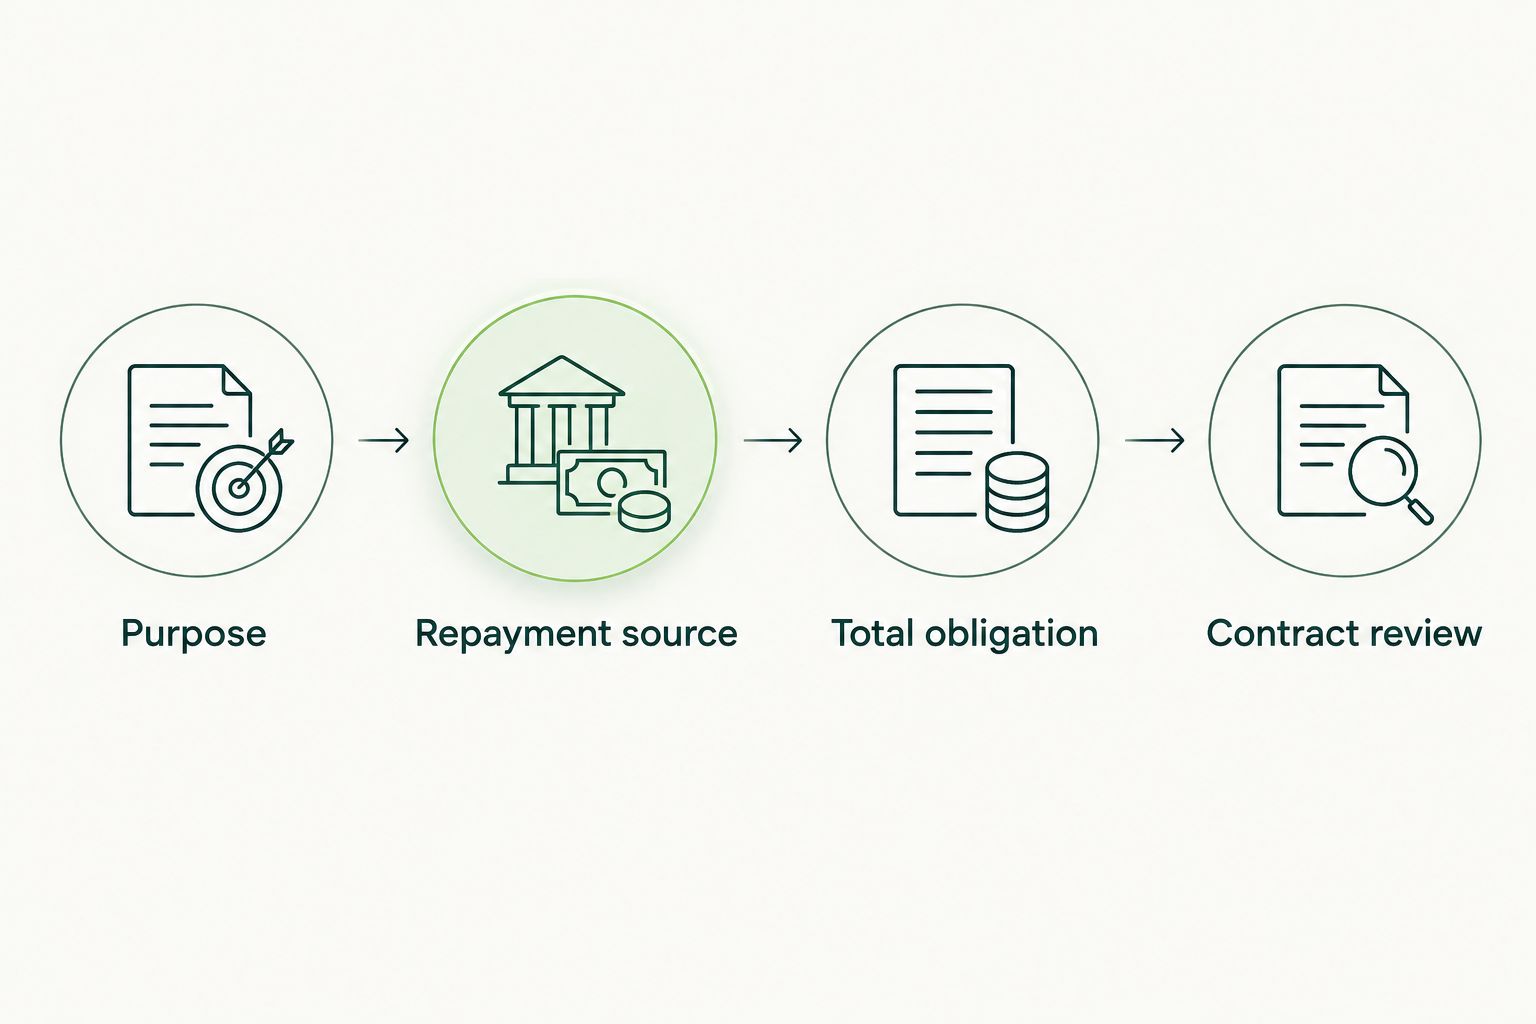
Four checks for comparing funding offers, from business purpose to contract review

Compare the agreement against your business need, not just the approval decision.

Use a cash-flow forecast that reflects your actual trading pattern. Include existing commitments and customer payment timing, rather than treating every expected sale as money already collected.

Ask each provider to explain anything you cannot reproduce in your own forecast. A clear explanation should connect the contract to the way your business receives and spends money.

Which alternative business funding option should you choose?

2M7 is best suited to operating Canadian businesses seeking a direct merchant cash advance. If that describes your need, assess the stated eligibility baseline and request the written terms before deciding.

Choose a different starting point when the funding purpose is more specific: BDC for development-bank financing, Community Futures for rural programme fit, factoring for eligible invoices, or equipment financing for an asset purchase.

For your 2026 decision, the default is simple: shortlist by purpose, then compare contracts. Do not apply everywhere before establishing what kind of obligation your business can support.

Discuss your funding options

Speak with a funding specialist about your business purpose and eligibility.

Discuss funding options

FAQ

What's the best alternative business lender in Canada?

The best fit depends on your funding purpose, eligibility and repayment capacity. Compare direct merchant cash advances, development-bank financing, local programmes, factoring and equipment financing as different structures, not interchangeable offers.

Is a merchant cash advance the same as a business loan?

No. A merchant cash advance is not a conventional business loan. Review the advance agreement's payment structure and obligations rather than assuming that loan terminology applies.

Can I apply for business funding with less-than-perfect credit?

Some funders consider businesses with less-than-perfect credit. That does not establish approval; operating history, revenue and the provider's assessment still matter.

Is BDC the same as a private alternative lender?

No. BDC is Canada's business development bank. Assess its specific financing products separately from private funding arrangements.

Can Community Futures fund any Canadian business?

Community Futures financing depends on the relevant local organisation's service area and programme requirements. Start by confirming that your location and business fit the programme.

Is invoice factoring better than equipment financing?

Neither is universally better because they address different needs. Invoice factoring concerns eligible receivables, while equipment financing supports acquiring an asset.

What should I check before accepting business funding in 2026?

Check the full obligation, payment mechanics, security requirements, guarantees and default provisions. Compare those terms with your cash-flow forecast before signing.

One last thing

The reason cash is missing matters more than the label on the funding. Slow customer payments, an equipment purchase and an ongoing operating loss are different problems. Write down which one you are addressing before you request an offer.

That sentence becomes a practical filter. If the provider cannot connect the proposed structure to your stated need, return to the shortlist instead of forcing a fit.

Related guides

Read more
May 4, 2026
October 2, 2026

Which Industries Benefit the Most from Merchant Cash Advance?

According to the Canadian Federation of Independent Business (CFIB), 2025 was a divided year for Canadian small business: while 37% of owners reported a good year in terms of revenues and profits, 35% reported a poor one. The smallest firms felt it most. Among businesses with fewer than five employees, only 35% described 2025 as a good year, compared to 42% of larger firms. Tariff pressures, high operating costs, and slowing business dynamism have left many owners caught in a difficult position.

For those who have turned to the bank for help, the options are often limited. The federal government's Canada Small Business Financing Program (CSBFP) issued just 6,409 loans totalling nearly $1.9 billion in 2024-25, a record in program history. But with approximately 1.2 million small businesses in Canada, the reach of traditional financing programs remains narrow. The average CSBFP loan size was $294,067, which is far more than what most small business owners need to solve a specific, immediate cash flow problem.

A Merchant Cash Advance (MCA) is one alternative worth understanding. It is not a bank loan. It is an advance on your future revenue, repaid as a percentage of daily sales, with a single fixed cost of capital disclosed upfront. There are no interest charges, no hidden fees, and no collateral requirements.

Some industries tend to benefit from this kind of flexible, short-term working capital more than others. Below are five industries which benefit from a merchant cash advance:

1. Restaurants and Food Service

Canada's foodservice sector added nearly 24,000 jobs between January and November 2025 according to Restaurants Canada, a sign that demand is holding up. Growth, however, requires capital, and restaurant revenue is inherently unpredictable. Equipment needs replacing without warning. A slow season can erode a cash position that looked healthy a few months earlier. Traditional lenders typically want two or more years of financial history and strong collateral before approving financing, which many independent restaurant owners cannot provide.

A merchant cash advance can provide working capital in the range of $5,000 to $300,000, with approval typically within one business day and funds deposited within 24 hours. Because repayments are tied to a percentage of daily sales, owners pay more when business is strong and less when it slows. This structure suits the seasonal and variable nature of restaurant revenue better than a fixed monthly payment.

One restaurant owner who used 2M7 funding for a kitchen equipment upgrade described the experience this way: "Highly recommend 2M7 if you are planning any big purchases. They helped us get funding for the new kitchen equipment and we continue to upgrade our facility."

2. Construction and Trades

Construction businesses routinely face a timing problem: materials, equipment, and labour costs arrive before client payments do. Payment terms of 30, 60, or even 90 days are common, which means contractors are often funding project costs out of their own cash flow while waiting for invoices to clear. Banks are generally reluctant to lend against this kind of irregular, project-based revenue, which leaves many contractors with limited options when they need capital quickly.

A merchant cash advance can help bridge the gap between project start and payment receipt, allowing contractors to cover immediate costs without waiting on a lengthy approval process or pledging personal assets.

Sean Morales, who needed funding for a demolition project, noted: "We need funds for a demolition project for our office. These guys got it done in less than 24 hrs."

More information on how working capital applies to the construction sector is available on 2M7's construction and trades funding page.

3. Retail and E-Commerce

Canadian e-commerce orders rose 20% in 2025 according to Omnisend, reflecting continued growth in both online and in-store retail. Sustaining that growth requires inventory investment well ahead of actual sales. Retailers need to order stock months before peak seasons, and suppliers often require payment before goods are delivered. A bank approval process that takes weeks is rarely compatible with those timelines.

Merchant cash advances allow retailers to access the capital they need for inventory, seasonal staffing, or store improvements without lengthy documentation requirements or the need to pledge collateral.

Morgan Lowe, a boutique retailer who used an MCA to expand her store, said: "I am a small business owner that just recently expanded and was struggling to find funding. 2M7 came through and has been wonderful to deal with."

For businesses where inventory is the core challenge, the impact can be ongoing. Visionary Hydroponics noted: "We are a small business and maintaining inventory can be a challenge. These types of [advances] help keep product on the shelf."

Details on how 2M7 works with retailers are available on the retail inventory and growth funding page.

4. Trucking and Transportation

BMO's Fall 2025 Canada Truck Transportation update describes the Canadian trucking industry as still in a fragile state, with trade barriers and tariff uncertainty continuing to weigh on domestic and cross-border freight volumes, rates, and fleet fundamentals. For owner-operators and small fleets, this means running lean while still needing to cover fuel, maintenance, and payroll between loads.

Traditional financing in this sector often requires an established credit history and years of documented revenue, which can be difficult to demonstrate during a period of industry-wide softness. A merchant cash advance offers a more accessible path to short-term working capital, with repayments that adjust alongside revenue rather than remaining fixed regardless of conditions.

More detail on how this applies to transportation businesses is available on 2M7's trucking funding page.

5. Landscaping and Seasonal Businesses

Seasonal businesses face a structural cash flow challenge that most financing products are not designed for. Revenue arrives in concentrated bursts, while costs related to insurance, equipment upkeep, and preparing for the next season continue year-round. A lender evaluating a landscaping company's winter financials will often see a picture that looks worse than the underlying business actually is.

The CFIB's December 2025 survey found that smaller firms are the most vulnerable to sudden cost pressures and disruptions. For seasonal operators, that kind of pressure is predictable and recurring rather than exceptional.

A merchant cash advance with flexible repayment can work with this pattern rather than against it. When revenue is strong in peak season, repayments reflect that. When it drops in the off-season, repayments decrease proportionally. Owners are not locked into a fixed payment schedule that ignores the realities of how their business operates.

Who Qualifies

Businesses interested in a merchant cash advance through 2M7 need to meet a straightforward set of criteria:

  • The business is located in Canada
  • The business has been operating for at least 3 months
  • Monthly revenue is at least $15,000
  • There are no open bankruptcies

No collateral is required. Approval decisions take into account overall revenue and business activity, not credit score alone.

How Repayment Works

2M7 offers two repayment structures. Fixed payments mean the same amount is debited on a regular schedule, with the option to request a reduction if revenue drops significantly. Flex payments are tied directly to a percentage of daily sales, so repayment amounts naturally rise and fall with business activity. The flex option is available to businesses that process daily credit and debit transactions.

Before signing, the total cost of capital is presented clearly. There are no origination fees, application fees, interest charges, brokerage fees, annual maintenance fees, or early repayment penalties. The cost disclosed upfront is the only cost.

Once a business is an existing client, requesting additional funding is straightforward. Clients can contact their dedicated representative directly by phone or text, and if approved, funds can be deposited within 30 minutes.

What Business Owners Have Said

"2M7 greatly guided us through the entire process of funding for our small business. We're extremely pleased with their clear explanations of what to expect and their steady commitment to helping us." -- Kotryna Zis

"Had the pleasure of dealing with 2M7 and Yakov, who helped our business get approved with funds in my account the next day. Greatly appreciate their help. Everything that we talked about was provided." -- Brady Douglas

"2M7 has been so wonderful to work with. Every employee I speak with is incredibly helpful and kind. I would never have been able to get back on my feet after COVID-19 if not for them." -- Jenny Watson

Is a Merchant Cash Advance Right for Your Business?

A merchant cash advance is not the right fit for every situation. It works best for businesses that have consistent revenue, need capital quickly, and want repayment terms that reflect how their business actually performs rather than a fixed schedule set by a lender.

Canada's government financing programs reached fewer than 6,500 businesses last year in a country with over a million small businesses. For many owners who fall outside the criteria those programs require, alternative working capital solutions are worth exploring.

If your business is based in Canada, has been operating for at least three months, and brings in at least $15,000 per month in revenue, you can check your eligibility with 2M7 without a lengthy application process.

Related reading: What is a Merchant Cash Advance? 2M7 vs. Other Merchant Cash Advance Options The Truth About Small Business Loans 5 Low-Cost Ways to Market Your Small Business in Canada

Sources: CFIB: A Divided Year, Small Business Performance in 2025 ISED: Canada Small Business Financing Program, Overview and Highlights 2024-25 Retail Insider / Restaurants Canada: Foodservice sector added nearly 24,000 jobs in 2025 BMO: Industry Update, Canada Truck Transportation, Fall 2025 Retail Insider / Omnisend: Canadian E-Commerce Orders Rose 20% in 2025

‍

Read more