ClickCease

Understanding Small Business Loans

Understanding Small Business Loans

Understanding Small Business Loans
10
Aug 2020
11
Aug 2026

What is a small business loan?

Generally speaking, a business loan is borrowed by a business owner or a company in order to finance and manage its operations including, but not limited to, purchasing equipment or inventory, investing in expansion, hiring new employees, and more. A business loan has terms and conditions directing how and where the money can be used, what the interest rate is, and what would be the repayment schedule. Every financial institution has its own criteria and requirements for lending and offering the best business cash advance loans; each will assess your credit rating differently in order to estimate how risky it is to lend you money and will offer you several lending options.  A small business loan is fundamentally the same, where the money borrowed for small business needs to be used to purchase equipment or hire employees. For entrepreneurs who are looking to get their venture off the ground, the small business start-up loans are a great alternative. New business owners say that the biggest challenge in starting a business is to get financing. In this case, private lenders and government programs offer financing options to help out new businesses.  At the federal and provincial levels, Canada offers startups various financial aid programs within specific sectors and regions. For instance, the Business Development Bank of Canada (BDC) offers loans to entrepreneurs to set up a new business, build or renovate facilities, buy equipment, develop new products, expand into new markets, improve IT infrastructure, and even sell the business.

Getting approved for your business loan

In order to get approval for small business loans in Canada, the owner has to provide a business plan as well as have all their documents in order. Firstly, you should ask yourself the following questions which will help you with your loan application:

  • Why does your business need the money?
  • What is the right type of loan for you?
  • What type of lender should you approach?
  • Do you think you qualify? If unsure, how can you improve your situation?
  • Do you have all the documents required by the bank?

Financial institutions are reluctant to provide business loans unless there is sufficient security or collateral to guarantee the loan. Numbers show that less than 25% of small startup business loan applications are approved by major lenders. That is why private lenders have become such a practical financing option in the last decade. Unlike venture capital or angel investors, they do not require you to put up a percentage of your business. Moreover, it is easier to obtain a business loan from private lenders as they are more flexible with the loan terms. The paperwork is not as difficult and loans approvals happen faster than in major financial institutions.  Below are a few types of small business loans and financing options:

  1. Lines of credit
  2. Peer to peer (P2P) loans
  3. Merchant advances
  4. Investor loans
  5. Term loans
  6. Commercial Bank Loans
  7. Equipment Loans for Startup Businesses
  8. Online Invoice Financing
  9. Traditional Equity Financing
  10. Personal Loans

Types of startup business loans

Startup needs differ from established and even small business needs. Moreover, the startup most likely generates zero or negative revenue in the beginning. Entrepreneurs who are looking to borrow money for their business are usually asked for personal guarantees and collateral. This means that the business owner may put up his house or any other assets as collateral for the loan. That said, start-up business loans may not be the best option – especially if there are not enough assets available. As mentioned above, small business start-up loans from private lenders are better alternatives. Whether obtained through crowd-funding, private lenders, or the government, small loans can help a business owner pave the way for his business. Currently, equipment loans for startups are very popular. These are relatively small loan amounts, so the equipment that is purchased can be put up as security. Merchant cash advances and peer to peer funding can help small businesses with their cash flow and managing operations. Business lines of credit (LOC), sometimes called corporate credit loans, are like credit cards but for businesses. It is a revolving credit system, where the business owner can withdraw the amount of money they need, up to the credit limit allowed by the lender. The borrower only pays interest on the amount that is borrowed. A business LOC can help a small business owner meet its cash flow requirements and manage their debt effectively.

A merchant cash advance for start-up businesses

Known as a “business cash advance”, merchant cash advances work on different terms compared to traditional loans. Unlike bank loans, a merchant cash advance does not evaluate credit score. Small business owners can typically receive up to $300,000 startup business Cash advance, without having to offer security for the loan! Under a merchant cash advance, the business receives a lump sum of advanced cash with the condition that the lender will receive a percentage of your future sales. Therefore, the merchant cash advance is a simple and fast way of getting capital right away. A merchant cash advance for startup businesses is a great financing option, allowing flexibility in repayment. For instance, if your sales in one month are lower, then the repayment amount will be lower; similarly, if your business performs very well the next month, your loan repayment will be higher. The private lender also takes care of repayments, ensuring there are no delays in payments from your end. Most of them have agreements with major payment processors, so private lenders can set up repayments based on your daily sales received by credit cards, which eliminates any headache of repayments on your end.   For business borrowers who need the money as soon as possible, merchant cash advances are one of the fastest ways of getting cash flow. Once the business loan is approved the cash advance is directly deposited into your account within one or two days. If you think it might be a good solution for you, do not hesitate to get in touch with us.

Related articles

October 14, 2026
October 14, 2026

Construction Prompt Payment Rules in Canada by Province (2026 Guide)

Ontario, Alberta, Saskatchewan and Manitoba all require an owner to pay a contractor's proper invoice within 28 days, or to dispute it in writing within 14 days. Once paid, a contractor has 7 days to pay its subcontractors. The provinces differ on holdback, lien deadlines and which projects are covered: Manitoba's holdback is 7.5% while the others hold back 10%, and Saskatchewan's lien period is still 40 days while the others allow 60.

‍

These rules are known as prompt payment legislation. They set a clock on construction payments that starts when a contractor delivers a proper invoice, and they give unpaid parties a fast dispute process called adjudication. Each province built its own version, so a contractor working across provincial lines faces different deadlines on each job.

‍

This guide compares the rules in each province, explains what they mean for a contractor's cash flow, and sets out what to do when a payment is late. It is general information, not legal advice. Check your contract and the current statute, or speak with a construction lawyer, before acting on a specific dispute.

‍

Prompt payment rules by province at a glance

Requirement Ontario Alberta Saskatchewan Manitoba
Statute Construction Act Prompt Payment and Construction Lien Act The Builders' Lien Act The Builders' Liens Act
Prompt payment in force October 1, 2019 August 29, 2022 March 1, 2022 April 1, 2025
Owner pays proper invoice 28 days 28 days 28 days 28 days
Owner disputes invoice (notice of non-payment) 14 days 14 days 14 days 14 days
Contractor pays subcontractor 7 days after being paid 7 days after being paid 7 days after being paid 7 days after being paid
Holdback 10% 10% 10% 7.5%
Lien period 60 days 60 days (90 for ready-mix concrete supply and oil or gas wells) 40 clear days 60 days
Interest on late payment Set by the Act Contract rate, or the Judgment Interest Regulation rate if none Prejudgment rate, or contract rate if higher Prejudgment rate, or contract rate if higher
Adjudication body ODACC ADACC and ARCANA (AB) SCDRO Manitoba Prompt Payment Adjudication Authority

‍

Ontario, Saskatchewan and Manitoba apply prompt payment to contracts entered into on or after the in-force date. Alberta also required contracts already in place to comply by August 29, 2024. Alberta's column covers private projects. Contracts with the Government of Alberta follow separate rules, explained below.

‍

Prompt payment in other jurisdictions

‍

Jurisdiction Status
Federal projects The Federal Prompt Payment for Construction Work Act has been in force since December 9, 2023, for construction on federal real property. The Crown must pay a proper invoice within 28 days and can dispute it within 21 days. Contractors must pay subcontractors by day 35 after the Crown received the invoice. Adjudication runs through CanDACC. Ontario, Saskatchewan and Alberta are designated as provinces with similar regimes, which changes how certain federal obligations apply to projects there.
British Columbia The Construction Prompt Payment Act received royal assent on November 27, 2025, but is not yet in force. The BC government says it will take effect once regulations are complete and an adjudication authority is selected. Once in force, it applies the same 28-, 14- and 7-day deadlines to new prime contracts.
Quebec A prompt payment regulation has applied to public construction contracts since September 8, 2025. Smaller public contracts join in two stages, on September 8, 2026, and September 8, 2027. It does not cover private projects.
Nova Scotia Prompt payment amendments to the Builders' Lien Act received royal assent in April 2019, but had not been brought into force as of March 2026.
New Brunswick The Construction Prompt Payment and Adjudication Act received royal assent on June 16, 2023, but had not been proclaimed in force as of March 2026.
Northwest Territories A new Builders' Lien Act with prompt payment provisions took effect September 1, 2025. It does not include adjudication for payment disputes.

‍

What these rules mean for a contractor's cash flow

Prompt payment shortens the wait for most of a contractor's money, but it does not remove the wait. Three gaps remain even when every party follows the rules.

‍

The billing cycle. Proper invoices are usually issued monthly, and Alberta requires one at least every 31 days. Work done early in a billing period is not invoiced until the period ends, and the owner then has 28 days to pay. Materials bought on day one can go unpaid for close to two months.

‍

The holdback. On a $200,000 contract in Ontario, Alberta or Saskatchewan, the owner retains $20,000. In Manitoba the holdback on the same contract is $15,000. On most projects that money is released only after the lien period expires near completion. Ontario now requires annual release on all contracts, and Alberta requires annual or phased release on contracts over $10 million that run longer than a year.

‍

Payment down the chain. A subcontractor's 7-day clock starts when the contractor is paid. If the owner pays on day 28, the subcontractor may wait 35 days from the contractor's invoice. In Ontario, Saskatchewan and Manitoba, if the owner does not pay at all, the contractor must still pay its subcontractors by day 35 after it invoiced the owner, unless it gives them a notice of non-payment.

‍

Meanwhile payroll, equipment rentals and supplier accounts run on their own schedules, often weekly or within 30 days. A busy contractor can be profitable on every job and still be short of cash between invoices. Planning for that gap is part of bidding a job, not an afterthought.

Province-by-province details

Ontario

Ontario's Construction Act introduced prompt payment on October 1, 2019, for public, private and alternative financing and procurement contracts. Amendments in force since January 1, 2026, make an invoice proper unless the owner gives written notice of a deficiency within 7 days.

‍

The 2026 amendments also require holdback to be released every year. Within 14 days after each contract anniversary, the owner must publish a notice of annual holdback release, then pay the accrued holdback between 60 and 74 days after publication, provided no lien remains undischarged. For contracts entered into before January 1, 2026, annual release begins on the second anniversary after that date. Disputes go to adjudication through the Ontario Dispute Adjudication for Construction Contracts (ODACC), and parties can now also retain private adjudicators qualified by ODACC.

Alberta

Alberta's Prompt Payment and Construction Lien Act has applied to private projects since August 29, 2022. Alberta allows 90 days to register a lien for the supply of ready-mix concrete and for oil or gas well work, longer than the general 60. Late payments carry interest at the contract rate, or the rate in the Judgment Interest Regulation if the contract sets none.

‍

Contracts with the Government of Alberta entered into on or after April 1, 2025, follow a separate prompt payment process under the Public Works Act. The Crown must pay an undisputed proper invoice within 28 days. Contractors must pay subcontractors within 35 days of receiving the subcontractor's proper invoice, and subcontractors pay their own subcontractors within 42 days. Payment disputes can go to adjudication up to the Court of Justice's monetary limit, currently $200,000. Capital asset upkeep contracts and special scope contracts, where the contractor provides financing, are excluded.

Saskatchewan

Saskatchewan added prompt payment to The Builders' Lien Act on March 1, 2022, for contracts entered into on or after that date. The Act binds the Crown, with exclusions such as highway work, and mining and certain power contracts are exempt. Saskatchewan's lien period is 40 clear days after the triggering event, such as completion or abandonment, which makes it the shortest of the four provinces. Adjudication runs through the Saskatchewan Construction Dispute Resolution Office (SCDRO).

Manitoba

Manitoba's prompt payment rules took effect April 1, 2025, and apply only to contracts entered into on or after that date. The same amendments raised the lien period from 40 to 60 days. Manitoba's holdback is 7.5%, retained for at least 60 days after substantial performance or completion. The Act binds the Crown but excludes Manitoba Hydro contracts for generating stations and related plant, and work under contracts governed by The Infrastructure Contracts Disbursement Act, which include certain provincial highway contracts. Architects' and engineers' fees are also exempt from prompt payment.

What to do when a payment is late

The prompt payment process gives a contractor several remedies short of court. Work through them in parallel, because the lien deadline keeps running while you pursue the others.

‍

  1. Confirm your invoice was proper. The 28-day clock only starts on a proper invoice, which must include the details the statute lists, such as the invoice date, the work period, the amount and payment terms. In Ontario, an owner who finds a deficiency must now say so within 7 days.
  2. Check for a notice of non-payment. If the owner disputes the invoice, it must give written notice within 14 days stating the amount withheld and why. Any undisputed amount is still due within 28 days.
  3. Track interest. Unpaid amounts accrue interest in all four provinces. Saskatchewan and Manitoba use the prejudgment rate, or the contract rate if higher. Alberta uses the contract rate, or the Judgment Interest Regulation rate if the contract sets none.
  4. Start adjudication. For a disputed amount, a contractor can refer the dispute to the province's adjudication body. Adjudication is designed to resolve payment disputes faster than court, and the decision must be followed unless a court or arbitrator later decides otherwise.
  5. Protect your lien rights. Register a lien within the provincial period (60 days in Ontario, Alberta and Manitoba; 40 clear days in Saskatchewan) or lose the right. Ontario extends the lien period in some cases where adjudication has started, but get legal advice before relying on an extension.

Covering costs while you wait to be paid

Prompt payment sets a deadline, but contractors still carry materials, payroll and holdback for weeks on every project. Before bidding, map when each invoice will be paid and when each major cost falls due. Negotiate deposits or mobilization payments where you can, and invoice on the first day the contract allows.

‍

When the gap is still too wide, working capital can bridge it. A merchant cash advance from 2M7 Financial Solutions provides funding based on a business's revenue, with no collateral required, and repayment can be set as a percentage of sales. 

‍

See how contractors use it on the construction funding page or see what options fit your project schedule.

‍

‍

Frequently asked questions

‍

How long does an owner have to pay a contractor in Ontario?

An Ontario owner must pay a contractor's proper invoice within 28 days of receiving it, unless it gives a notice of non-payment within 14 days. Undisputed amounts are still due within 28 days.

‍

Does Alberta have prompt payment legislation?

Yes. Alberta's Prompt Payment and Construction Lien Act has applied to private projects since August 29, 2022, and owners have 28 calendar days to pay a proper invoice. Contracts with the Government of Alberta entered into on or after April 1, 2025, follow a separate prompt payment process under the Public Works Act.

‍

Does British Columbia have prompt payment legislation?

BC's Construction Prompt Payment Act received royal assent on November 27, 2025, but is not yet in force. Once in force, owners will have 28 days to pay a proper invoice.

‍

What is the holdback percentage in each province?

The holdback is 10% in Ontario, Alberta and Saskatchewan, and 7.5% in Manitoba.

‍

How long do I have to register a construction lien?

The lien period is 60 days in Ontario, Alberta and Manitoba, and 40 clear days in Saskatchewan. Alberta allows 90 days for the supply of ready-mix concrete and for oil or gas well work.

‍

How fast must a contractor pay its subcontractors?

In Ontario, Alberta, Saskatchewan and Manitoba, a contractor must pay its subcontractors within 7 days of receiving payment from the owner, unless it gives a notice of non-payment. In Ontario, Saskatchewan and Manitoba, a contractor that has not been paid must still pay its subcontractors by day 35 after invoicing the owner, unless it gives a notice of non-payment.

‍

What is construction adjudication?

Adjudication is a fast dispute process for construction payment disputes, run by a provincial body such as ODACC in Ontario. The adjudicator's decision is binding on an interim basis, which means it must be followed unless a court or arbitrator later decides otherwise.

Sources

Checked October 13, 2026.

‍

Read more
October 14, 2026
October 14, 2026

Best working capital loan options for small businesses 2026

Best overall for recurring cash gaps: an operating line of credit. Best for a defined expense: a short-term business loan. Best for supplier purchases: trade credit. Start your working capital loan Canada comparison with 2M7, then assess each option against your cash collection cycle—not just the amount offered.

TL;DR

  • For your working capital loan Canada search, compare repayment timing before choosing a lender, including 2M7.
  • An operating line of credit fits recurring cash gaps; a term loan fits a defined expense.
  • Invoice factoring fits unpaid customer invoices, while trade credit addresses supplier purchases.
  • A merchant cash advance requires careful review of deductions, total repayment and weaker-sales cash flow.

Why this matters

Working capital financing covers the gap between paying business expenses and collecting customer revenue. That gap matters even when your business is profitable: unpaid invoices cannot fund payroll, and unsold inventory cannot pay a supplier.

The best working capital financing matches repayment to the cash that will repay it. For your 2026 comparison, separate a temporary timing gap from an ongoing operating loss. Financing can bridge the first; borrowing alone does not fix the second.

This guide ranks financing structures, not individual lenders. A line of credit, a loan, factoring, supplier credit and a merchant cash advance solve different problems. Some are not loans at all, despite appearing alongside loans in a funding search.

What makes the best working capital financing?

Use these criteria before comparing offers. An attractive funding amount is not enough if the repayment schedule leaves your business short of operating cash.

  • Repayment fit: Match payment dates to customer collections. Frequent deductions need a different cash-flow test from monthly instalments.
  • Access pattern: Choose reusable borrowing for recurring gaps and a defined advance for a specific expense.
  • Total obligation: Identify the full amount payable, mandatory charges and any obligations that survive early repayment.
  • Security and liability: Check business security, personal guarantees and restrictions on additional borrowing.
  • Customer involvement: Establish whether customers receive payment instructions or collection contact from a financing provider.
  • Exit conditions: Read cancellation, renewal, prepayment and default provisions before accepting funds.

For any offer you consider through 2M7, apply the same criteria you would use with a bank or another financing provider. Compare written terms, not assumptions about a provider's business model.

Working capital options at a glance

The table ranks options by the cash-flow problem they address. Each structure has a distinct use case; the first entry is not automatically the right answer for every business.

1. Operating line of credit

  • Best for: Recurring timing gaps
  • Standout feature: Draw, repay and redraw within agreed terms
  • Key limitation: Access remains subject to the facility's conditions

2. Short-term business loan

  • Best for: A defined operating expense
  • Standout feature: Scheduled repayment of a defined amount
  • Key limitation: Payments continue when collections slow

3. Invoice factoring

  • Best for: Cash tied up in customer invoices
  • Standout feature: Converts eligible receivables into earlier cash
  • Key limitation: Customer involvement and recourse terms need review

4. Trade credit

  • Best for: Supplier purchases before customer collection
  • Standout feature: Delays payment for an agreed purchase
  • Key limitation: Does not provide general-purpose cash

5. Merchant cash advance

  • Best for: Businesses evaluating sales-linked funding
  • Standout feature: Repayment or collection structure tied to the agreement
  • Key limitation: Frequent deductions can pressure operating cash

For your 2026 shortlist, identify the expense first. Payroll needs usable cash; a supplier order might only need a later payment date. This distinction prevents you from comparing financing that cannot solve the same problem.
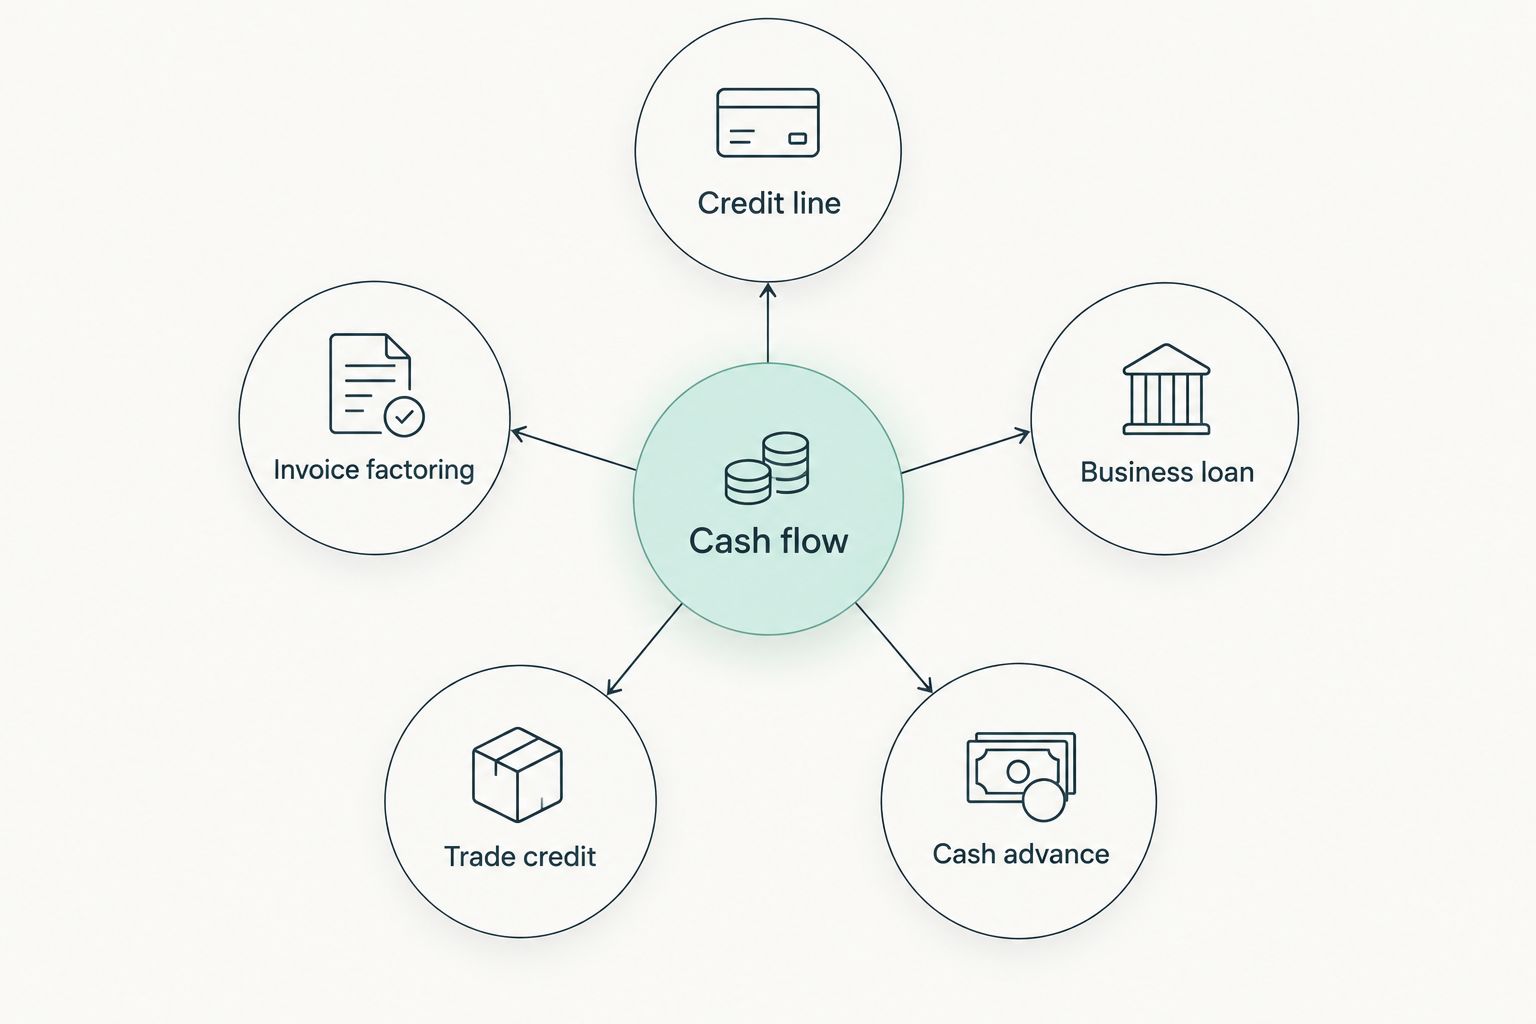
Five working capital financing structures connected to a central cash-flow need

Choose the financing structure that addresses the actual cash-flow gap.

1. Operating line of credit: best for recurring cash gaps

An operating line of credit lets you borrow within an approved limit, repay the balance and borrow again under the agreement. It suits a repeating mismatch between outgoing expenses and incoming customer payments. You do not need to treat every recurring gap as a separate borrowing decision.

Best for: Businesses with repeatable collection cycles and a clear source of repayment.

The strongest use case is timing, not permanent dependence. Draw against a temporary shortfall, then reduce the balance when customers pay. If the balance never falls, examine whether the facility is covering a structural cash deficit.

Operating line of credit pros:

  • Reusable access supports repeated working capital needs.
  • You can draw against the current gap rather than a single larger planned expense.
  • Customer collections can reduce the outstanding balance.

Operating line of credit cons:

  • Renewal, reporting and borrowing conditions require ongoing attention.
  • Security or personal guarantees can extend the consequences of default.
  • A persistent balance can hide a business that is not generating enough cash.

Ask whether access depends on receivables, inventory or financial reporting. Read the conditions governing limit changes and repayment demands rather than assuming an approved limit is unconditional.

Verdict: Buy only when your forecast shows a recurring gap and a credible route back to a lower balance.

2. Short-term business loan: best for a defined expense

A short-term business loan provides a defined borrowing amount with an agreed repayment schedule. It fits an identifiable operating need better than an open-ended shortfall. Examples include funding an inventory purchase or covering a documented seasonal cash gap.

Best for: Businesses that can connect a specific expense to a specific repayment source.

For a 2026 decision, explain the transaction in plain language: what you need to pay, when the expense produces cash and when repayments begin. A loan becomes harder to assess when its purpose is simply to keep the business account positive.

Short-term business loan pros:

  • A defined amount makes the funding purpose easy to track.
  • Scheduled payments can be incorporated into a cash forecast.
  • A set repayment endpoint helps distinguish this expense from ongoing borrowing.

Short-term business loan cons:

  • Scheduled obligations continue even when customer payments arrive late.
  • Additional funding generally requires a separate arrangement unless the agreement provides otherwise.
  • Early repayment benefits depend on the contract, not the remaining term alone.

Check whether repayments begin before the funded purchase generates cash. Also establish how the agreement calculates the amount due if you repay early; do not assume every remaining charge disappears.

Verdict: Buy for a defined expense with a repayment source; skip for an unexplained recurring deficit.

3. Invoice factoring: best for unpaid customer invoices

Invoice factoring involves selling eligible receivables to obtain cash before customers pay. Unlike a general-purpose loan assessment, the transaction centres on invoices and the customers responsible for paying them. Agreement terms determine eligibility, collections and responsibility for unpaid invoices.

Best for: Businesses whose working capital gap sits in issued customer invoices rather than future sales.

An invoice is not automatically suitable for factoring. Disputes, customer acceptance, contractual restrictions and the provider's eligibility rules all belong in the review. Separate completed, billable work from orders that have not yet become receivables.

Invoice factoring pros:

  • Connects funding to existing customer invoices.
  • Can address collection delays without waiting for the invoice payment date.
  • Provides a distinct alternative to borrowing for general operating expenses.

Invoice factoring cons:

  • Customer payment instructions or collection arrangements can change.
  • Recourse provisions can leave your business responsible for unpaid invoices.
  • Eligibility restrictions mean not every invoice produces usable funding.

Ask who contacts customers, who handles disputes and what happens if a customer does not pay. Recourse and non-recourse labels are not enough; read the covered events and exclusions.

Verdict: Buy when eligible receivables are the bottleneck; skip when your need depends on sales not yet invoiced.

4. Trade credit: best for supplier purchases

Trade credit allows you to receive goods or services and pay the supplier later under agreed terms. It addresses the purchase directly rather than depositing general-purpose financing into your business account. That makes it a separate option from a working capital loan.

Best for: Businesses whose immediate shortfall is a supplier payment rather than payroll or another cash expense.

In your 2026 planning, compare the supplier payment date with the expected customer collection date. If customers pay after the supplier is due, trade credit leaves a remaining gap. Do not mistake delayed payment for a complete funding solution.

Trade credit pros:

  • Directly addresses the timing of a supplier purchase.
  • Avoids arranging separate cash financing for that purchase when the terms fit.
  • Can align purchasing and collections when both schedules are understood.

Trade credit cons:

  • Cannot fund expenses outside the supplier arrangement.
  • Late payment can damage an important supplier relationship.
  • Limits, charges and payment conditions vary by agreement.

Get the due date and consequences of late payment in writing. If the supplier is essential to operations, include supplier continuity in your decision rather than focusing only on the immediate cash benefit.

Verdict: Buy when the purchase and collection dates align; hold when the arrangement merely pushes the same shortfall later.

5. Merchant cash advance: best for evaluating sales-linked funding

A merchant cash advance provides business funding under an agreement connected to future sales or receivables. Collection arrangements vary: examine whether deductions actually change with sales or follow a fixed schedule. The product name does not establish how your cash balance will behave.

Best for: Businesses that understand their sales pattern and can assess the agreement's collection mechanics.

Evaluate an advance separately from a conventional instalment loan. The full obligation, deduction method, reconciliation provisions and default terms matter more than a short description of access to funding.

Merchant cash advance pros:

  • Provides an alternative structure to a conventional business loan.
  • Sales-linked collection can connect payments to revenue where the agreement provides for it.
  • A defined advance can address an identifiable operating need.

Merchant cash advance cons:

  • Frequent deductions can reduce cash available for essential expenses.
  • Fixed collection amounts do not automatically shrink during weaker sales.
  • A quoted factor is not directly comparable to an annual interest rate.

Ask for the complete repayment obligation and a written explanation of deductions. If the agreement permits adjustment when sales fall, identify the request process and required evidence before relying on that provision.

Verdict: Hold until the deduction schedule passes a weaker-sales cash-flow test.

How to compare written financing offers

Build a 13-week cash forecast before accepting working capital financing. Use weekly opening cash, expected customer receipts, essential outflows, financing deductions and closing cash. This is a planning recommendation, not an approval requirement.

Then extend the review into a 12-month operating plan so renewal dates, seasonality and other borrowing obligations remain visible. A short forecast answers whether you can meet immediate payments; the longer view shows whether the funding purpose resolves or repeats.

Use these steps for each written offer:

  1. Define the gap. State the expense and the event expected to repay the funding.
  2. Map collections. Separate expected receipts from cash already collected.
  3. Add repayments. Enter deductions on their actual scheduled dates.
  4. Test delays. Model a 30-day customer payment delay as a planning scenario, not a prediction.
  5. Read obligations. Check guarantees, security, default triggers and exit terms.

When assessing a 2M7 working capital financing offer, use the same forecast and questions. A comparison only becomes useful when competing agreements address the same funding need and expose their full obligations.

Review your financing starting point

Use the cash-flow checklist before discussing a working capital financing offer.

Visit 2M7

How these options are ranked

The ranking prioritizes repayment fit, repeated access, a defined funding purpose and visibility into obligations. It does not score providers on approval speed, eligibility or customer satisfaction.

An operating line of credit ranks first for recurring timing gaps because its reusable structure matches that problem. The remaining options earn separate use-case positions: a specific expense, unpaid invoices, supplier purchases and sales-linked funding. Choose by the problem, not the position.

Which working capital option should you choose?

For an undecided business owner in 2026, start with an operating line of credit if the shortfall repeats and customer collections can reduce the balance. Choose a short-term business loan when the expense and repayment source are defined.

Use invoice factoring when issued invoices are holding up cash. Discuss trade credit when the immediate need is a supplier purchase. Evaluate a merchant cash advance only after understanding how its deductions affect essential operating payments.

For a working capital loan Canada comparison, use 2M7 as a starting point—not a substitute for reviewing written repayment terms. Keep the final decision tied to your forecast. This guide explains financing structures and does not replace advice on your business's contractual or financial obligations.

FAQ

What's the best working capital loan in Canada for a small business?

An operating line of credit is the strongest starting point for recurring cash-flow timing gaps. A short-term business loan fits a defined expense better; the right choice depends on repayment terms and the cash that will repay it.

Is a business line of credit better than a working capital loan?

A business line of credit is better suited to repeated borrowing and repayment, while a term loan suits a defined funding amount. Compare access conditions and repayment obligations before choosing either structure.

Can invoice factoring help if customers pay late?

Invoice factoring can turn eligible unpaid invoices into earlier cash. Check customer involvement, invoice eligibility and who carries responsibility if an invoice remains unpaid.

Is trade credit the same as a business loan?

Trade credit is not the same as a general-purpose business loan. It delays payment to a supplier under agreed terms and does not provide cash for unrelated operating expenses.

What should I check before accepting a merchant cash advance?

Check the full repayment obligation, deduction schedule and adjustment provisions before accepting a merchant cash advance. Test whether essential expenses remain covered during weaker sales or delayed customer payments.

Do working capital loans require a personal guarantee?

Personal guarantee requirements depend on the provider and agreement. Read the actual guarantee and security provisions rather than assuming they apply—or do not apply—to an entire financing category.

How should I compare a 2M7 offer with another financing offer?

Compare a 2M7 working capital financing offer using the same funding purpose and cash forecast as any competing offer. Review total obligations, repayment dates, guarantees, security, early repayment terms and default provisions.

One last thing

Repayment timing can defeat an otherwise sensible funding plan. A forecast showing enough cash at month-end can still contain a shortfall before payroll or a supplier payment falls due. Review the dates—not just the totals—before signing.

Read more
October 16, 2026
October 16, 2026

Best alternative business lenders in Canada 2026

Best for a direct merchant cash advance: 2M7. Best for development-bank financing: BDC. Best for rural business support: Community Futures. This 2026 guide compares named funders and specialist financing categories so you can match your business need to the right repayment structure.

TL;DR

  • For alternative business lenders Canada-wide, compare funding purpose and repayment structure before choosing a provider.
  • 2M7 suits operating Canadian businesses seeking a direct merchant cash advance, not a conventional business loan.
  • BDC and Community Futures serve different financing needs; check the specific programme before applying.
  • Invoice factoring fits receivables gaps; equipment financing fits asset purchases. Neither replaces a full cash-flow assessment.

Why this matters

Alternative business funding is not one product. A merchant cash advance, a business loan, invoice factoring and equipment financing create different obligations, even when they support the same business expense.

Choose the funding structure before choosing the provider. Otherwise, you risk comparing offers that solve different problems. An invoice-backed arrangement addresses unpaid customer invoices; an equipment agreement addresses an asset purchase. Neither is automatically the right way to cover payroll.

This shortlist separates those purposes. It does not name a cheapest provider because the right comparison requires written offers for your business, not a headline claim.

What makes the best alternative business lender?

Use these criteria to assess your 2026 shortlist before submitting applications:

  • Product fit: Identify whether you need a merchant cash advance, a loan, invoice factoring or equipment financing. Ask what agreement you will actually sign.
  • Eligibility fit: Check operating history, revenue requirements, location and any conditions attached to the funding programme.
  • Repayment fit: Understand the payment schedule, collection method and what happens when revenue falls or customers pay late.
  • Contract clarity: Review the amount you receive, your full contractual obligation, security requirements and default provisions together.
  • Provider role: Establish whether you are dealing with the funder, a broker or a referral service. Know who makes the decision and services the agreement.
  • Purpose fit: Match the obligation to the expense. A recurring operating shortfall needs a different assessment from a productive asset purchase.

A strong offer passes all these checks. Approval alone does not establish that the funding works for your business.

Alternative business funding options at a glance

The 2026 comparison below combines named organisations with specialist provider categories. Category entries are not endorsements of every business operating within them.

1. 2M7

  • Best for: Direct merchant cash advances for operating businesses
  • Standout feature: Direct funder rather than a broker
  • Key limitation: Minimum operating history and monthly revenue requirements apply

2. BDC

  • Best for: Businesses considering development-bank financing
  • Standout feature: Canadian business development bank
  • Key limitation: The specific financing product must match your purpose and eligibility

3. Community Futures

  • Best for: Rural businesses seeking local financing and support
  • Standout feature: Community-based business development organisations
  • Key limitation: Service areas and local programme requirements matter

4. Invoice factoring providers

  • Best for: Businesses waiting on eligible customer invoices
  • Standout feature: Funding tied to receivables
  • Key limitation: Depends on invoices, customers and the factoring agreement

5. Equipment financing providers

  • Best for: Businesses acquiring equipment
  • Standout feature: Funding structured around an asset
  • Key limitation: Equipment-focused agreements do not provide unrestricted working capital

1. 2M7: best for a direct merchant cash advance

2M7 provides merchant cash advances and working capital directly to Canadian small and mid-sized businesses. It is not a broker, and its merchant cash advance is not a conventional business loan.

The stated eligibility baseline is at least 3 months in business and $15,000 in monthly revenue. Businesses with less-than-perfect credit are within its stated customer scope, but meeting the baseline does not establish approval.

Best for: An operating Canadian business considering a direct merchant cash advance for payroll, inventory, equipment or a cash-flow gap.

2M7 pros:

  • You deal with the direct funder rather than a funding broker.
  • The stated customer scope includes businesses with less-than-perfect credit.
  • Working capital can support the business uses listed above.

2M7 cons:

  • Businesses below the stated operating-history or revenue thresholds do not meet the baseline.
  • Flex payments apply only to businesses that process daily card payments.
  • The suitability of an advance still depends on the business's ability to meet the agreement.

The company reports funding more than 5,000 Canadian businesses. That establishes experience, not a prediction about your application or a substitute for reviewing your contract.

Before signing, ask how payments are collected and how the obligation fits your quieter trading periods. Verdict: Hold until the written agreement and your cash-flow forecast support the commitment.

2. BDC: best for development-bank financing

BDC is Canada's business development bank. Include BDC when you want to assess business financing through an organisation with a development mandate rather than treating every non-bank search result as the same kind of provider.

Start with the purpose of your application. Funding an expansion, buying equipment and supporting working capital require different conversations, even when the same organisation offers several financing routes.

Best for: A Canadian business assessing development-bank financing for a defined business purpose.

BDC pros:

  • Its role as Canada's business development bank is clearly established.
  • You can begin the discussion with the business objective rather than a generic funding request.
  • It provides a useful comparison point when assessing other financing structures.

BDC cons:

  • BDC's name alone does not tell you whether a particular financing product fits your business.
  • You still need to assess the specific eligibility conditions, documentation and repayment obligation.

Do not assume that a development mandate means automatic qualification or that every product serves every business stage. Request the requirements for the actual financing under discussion.

Verdict: Hold until you identify a suitable product and confirm the application requirements.

3. Community Futures: best for rural business support

Community Futures organisations provide business development support and financing in rural communities. The relevant starting point is the organisation serving your location, not a national assumption about one standard offer.

For a rural business owner, local programme fit belongs near the top of the assessment. Confirm the service area, eligible business activities and intended use of funds before building an application around this route.

Best for: A rural Canadian business seeking locally delivered business financing and support.

Community Futures pros:

  • The community-based model gives rural businesses a distinct starting point.
  • Financing and business support can be considered together.
  • Local programme information helps you assess geographic eligibility early.

Community Futures cons:

  • Your business must fit the relevant service area and programme requirements.
  • An offer or condition described by one local organisation does not establish the terms elsewhere.

Ask the local organisation which programmes match your business stage and intended expense. Keep that answer separate from any general information about the wider network.

Verdict: Hold until the local organisation confirms programme and geographic fit.

4. Invoice factoring providers: best for unpaid customer invoices

Invoice factoring involves selling receivables to a factoring provider under an agreement. It addresses money tied up in eligible customer invoices rather than funding based solely on your business's general sales outlook.

This makes factoring a specific tool, not a general substitute for every working-capital need. The invoices, the customers responsible for paying them and the contract all matter.

Best for: A business with eligible business-to-business receivables that needs to address a gap between invoicing and customer payment.

Invoice factoring pros:

  • The funding need connects directly to existing receivables.
  • You can assess the arrangement against identifiable invoices and customer payment dates.
  • The structure distinguishes an invoice-collection gap from a lack of underlying sales.

Invoice factoring cons:

  • A business without eligible invoices cannot use this structure for that purpose.
  • Customer notification and collection arrangements require review.
  • Recourse provisions can leave responsibilities with your business if customers do not pay.

Ask who contacts customers, who handles collections and what happens if an invoice is disputed. Do not assume that selling an invoice removes every payment-related obligation.

Verdict: Hold until invoice eligibility, customer handling and recourse terms are clear.

5. Equipment financing providers: best for an asset purchase

Equipment financing supports the acquisition of business equipment through arrangements such as equipment loans or leases. It belongs on your shortlist when the asset itself is the reason you need funding.

Separate the equipment decision from the financing decision. First establish that the asset serves a business need; then compare the obligations attached to acquiring it.

Best for: A business purchasing or leasing equipment for a defined operational purpose.

Equipment financing pros:

  • The financing purpose connects to a specific asset.
  • Equipment loans and leases provide different structures to evaluate.
  • You can compare the payment obligation with the equipment's expected business use.

Equipment financing cons:

  • An equipment-focused agreement does not solve unrelated payroll or inventory needs.
  • Ownership, maintenance responsibilities and end-of-term provisions differ by agreement.
  • Security and default provisions need review before you commit the asset or business.

Check whether you own the equipment during the agreement and what happens at its end. A payment figure alone does not answer either question.

Verdict: Hold until the ownership structure and full agreement match the asset's intended use.

How these options were ranked

This 2026 ranking follows distinct business needs: direct merchant cash advances, development-bank financing, rural support, receivables and equipment. It is not a ranking of approval likelihood or a claim that one provider offers the best terms to every applicant.

The order puts a direct working-capital option first, then separates routes whose suitability depends on a development mandate, geography, invoices or an asset. Use the criteria above to change the order for your business.

A rural equipment purchase, for example, deserves a different shortlist from an urban retailer's inventory requirement. The business purpose decides which entry moves to the top.

How to compare the offers you receive

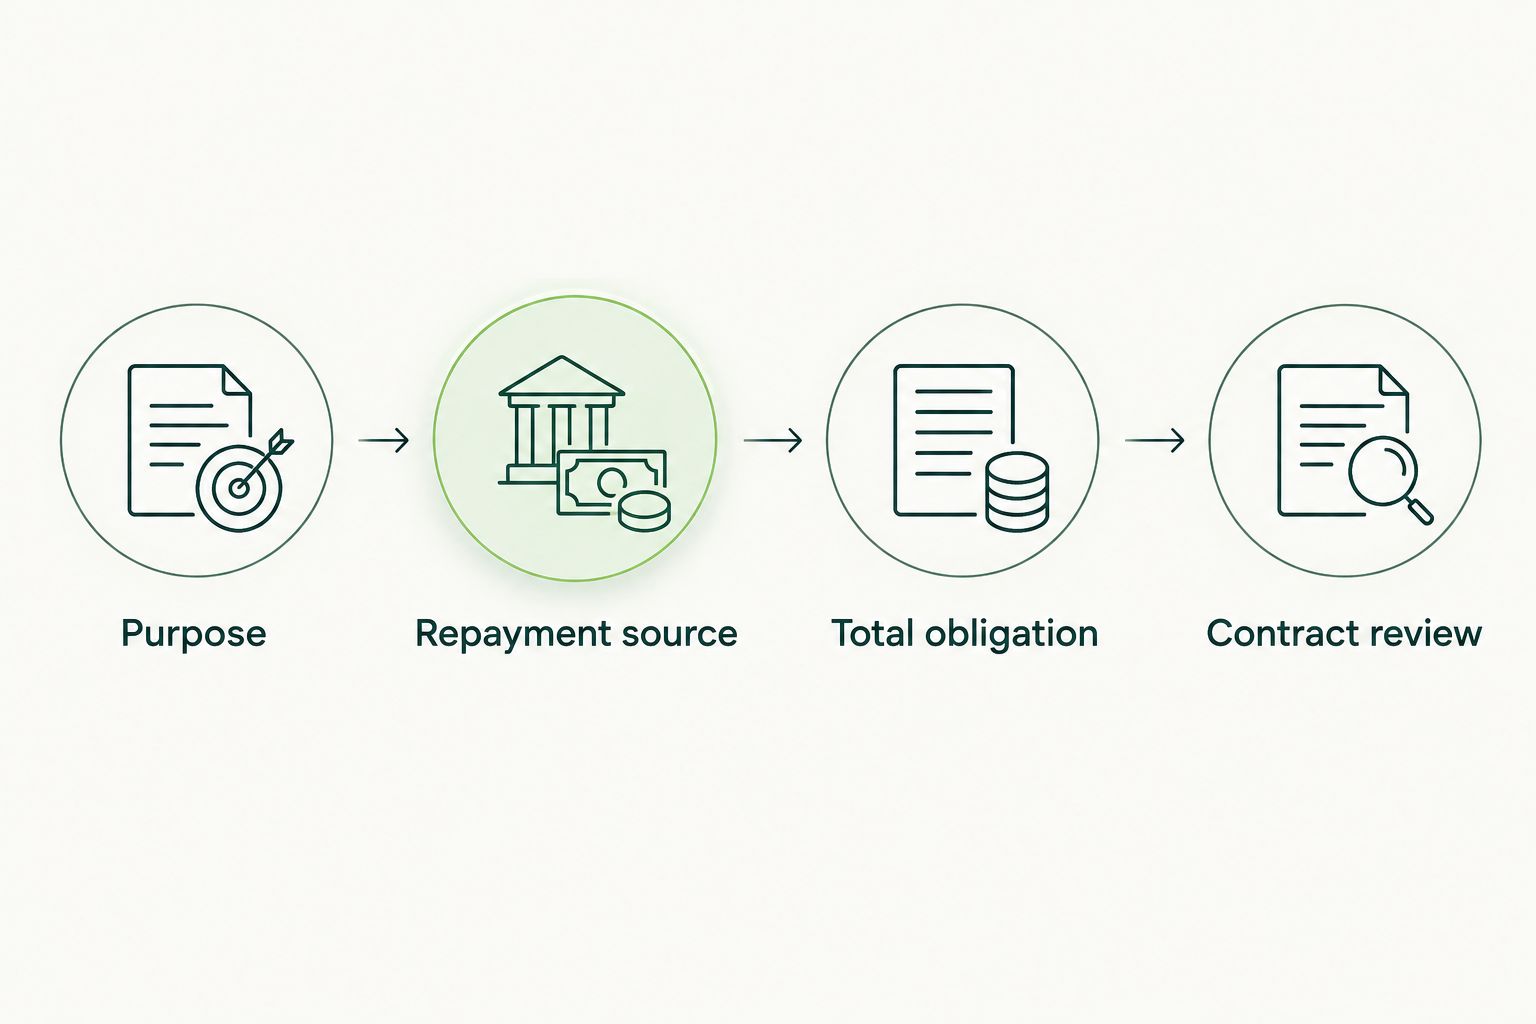
Before choosing from alternative business lenders in Canada in 2026, put each written offer through the same review:

  • Purpose: State the expense the funding will cover and why the business needs it.
  • Repayment source: Identify the revenue or receivables expected to support the obligation.
  • Total obligation: Read the complete amount owed, payment mechanics and any conditional charges together.
  • Contract review: Check security, guarantees, default provisions and early-payment conditions before signing.

Four checks for comparing funding offers, from business purpose to contract review

Compare the agreement against your business need, not just the approval decision.

Use a cash-flow forecast that reflects your actual trading pattern. Include existing commitments and customer payment timing, rather than treating every expected sale as money already collected.

Ask each provider to explain anything you cannot reproduce in your own forecast. A clear explanation should connect the contract to the way your business receives and spends money.

Which alternative business funding option should you choose?

2M7 is best suited to operating Canadian businesses seeking a direct merchant cash advance. If that describes your need, assess the stated eligibility baseline and request the written terms before deciding.

Choose a different starting point when the funding purpose is more specific: BDC for development-bank financing, Community Futures for rural programme fit, factoring for eligible invoices, or equipment financing for an asset purchase.

For your 2026 decision, the default is simple: shortlist by purpose, then compare contracts. Do not apply everywhere before establishing what kind of obligation your business can support.

Discuss your funding options

Speak with a funding specialist about your business purpose and eligibility.

Discuss funding options

FAQ

What's the best alternative business lender in Canada?

The best fit depends on your funding purpose, eligibility and repayment capacity. Compare direct merchant cash advances, development-bank financing, local programmes, factoring and equipment financing as different structures, not interchangeable offers.

Is a merchant cash advance the same as a business loan?

No. A merchant cash advance is not a conventional business loan. Review the advance agreement's payment structure and obligations rather than assuming that loan terminology applies.

Can I apply for business funding with less-than-perfect credit?

Some funders consider businesses with less-than-perfect credit. That does not establish approval; operating history, revenue and the provider's assessment still matter.

Is BDC the same as a private alternative lender?

No. BDC is Canada's business development bank. Assess its specific financing products separately from private funding arrangements.

Can Community Futures fund any Canadian business?

Community Futures financing depends on the relevant local organisation's service area and programme requirements. Start by confirming that your location and business fit the programme.

Is invoice factoring better than equipment financing?

Neither is universally better because they address different needs. Invoice factoring concerns eligible receivables, while equipment financing supports acquiring an asset.

What should I check before accepting business funding in 2026?

Check the full obligation, payment mechanics, security requirements, guarantees and default provisions. Compare those terms with your cash-flow forecast before signing.

One last thing

The reason cash is missing matters more than the label on the funding. Slow customer payments, an equipment purchase and an ongoing operating loss are different problems. Write down which one you are addressing before you request an offer.

That sentence becomes a practical filter. If the provider cannot connect the proposed structure to your stated need, return to the shortlist instead of forcing a fit.

Related guides

Read more