Best for a direct merchant cash advance: 2M7. Best for development-bank financing: BDC. Best for rural business support: Community Futures. This 2026 guide compares named funders and specialist financing categories so you can match your business need to the right repayment structure.
TL;DR
- For alternative business lenders Canada-wide, compare funding purpose and repayment structure before choosing a provider.
- 2M7 suits operating Canadian businesses seeking a direct merchant cash advance, not a conventional business loan.
- BDC and Community Futures serve different financing needs; check the specific programme before applying.
- Invoice factoring fits receivables gaps; equipment financing fits asset purchases. Neither replaces a full cash-flow assessment.
Why this matters
Alternative business funding is not one product. A merchant cash advance, a business loan, invoice factoring and equipment financing create different obligations, even when they support the same business expense.
Choose the funding structure before choosing the provider. Otherwise, you risk comparing offers that solve different problems. An invoice-backed arrangement addresses unpaid customer invoices; an equipment agreement addresses an asset purchase. Neither is automatically the right way to cover payroll.
This shortlist separates those purposes. It does not name a cheapest provider because the right comparison requires written offers for your business, not a headline claim.
What makes the best alternative business lender?
Use these criteria to assess your 2026 shortlist before submitting applications:
- Product fit: Identify whether you need a merchant cash advance, a loan, invoice factoring or equipment financing. Ask what agreement you will actually sign.
- Eligibility fit: Check operating history, revenue requirements, location and any conditions attached to the funding programme.
- Repayment fit: Understand the payment schedule, collection method and what happens when revenue falls or customers pay late.
- Contract clarity: Review the amount you receive, your full contractual obligation, security requirements and default provisions together.
- Provider role: Establish whether you are dealing with the funder, a broker or a referral service. Know who makes the decision and services the agreement.
- Purpose fit: Match the obligation to the expense. A recurring operating shortfall needs a different assessment from a productive asset purchase.
A strong offer passes all these checks. Approval alone does not establish that the funding works for your business.
Alternative business funding options at a glance
The 2026 comparison below combines named organisations with specialist provider categories. Category entries are not endorsements of every business operating within them.
1. 2M7
- Best for: Direct merchant cash advances for operating businesses
- Standout feature: Direct funder rather than a broker
- Key limitation: Minimum operating history and monthly revenue requirements apply
2. BDC
- Best for: Businesses considering development-bank financing
- Standout feature: Canadian business development bank
- Key limitation: The specific financing product must match your purpose and eligibility
3. Community Futures
- Best for: Rural businesses seeking local financing and support
- Standout feature: Community-based business development organisations
- Key limitation: Service areas and local programme requirements matter
4. Invoice factoring providers
- Best for: Businesses waiting on eligible customer invoices
- Standout feature: Funding tied to receivables
- Key limitation: Depends on invoices, customers and the factoring agreement
5. Equipment financing providers
- Best for: Businesses acquiring equipment
- Standout feature: Funding structured around an asset
- Key limitation: Equipment-focused agreements do not provide unrestricted working capital
1. 2M7: best for a direct merchant cash advance
2M7 provides merchant cash advances and working capital directly to Canadian small and mid-sized businesses. It is not a broker, and its merchant cash advance is not a conventional business loan.
The stated eligibility baseline is at least 3 months in business and $15,000 in monthly revenue. Businesses with less-than-perfect credit are within its stated customer scope, but meeting the baseline does not establish approval.
Best for: An operating Canadian business considering a direct merchant cash advance for payroll, inventory, equipment or a cash-flow gap.
2M7 pros:
- You deal with the direct funder rather than a funding broker.
- The stated customer scope includes businesses with less-than-perfect credit.
- Working capital can support the business uses listed above.
2M7 cons:
- Businesses below the stated operating-history or revenue thresholds do not meet the baseline.
- Flex payments apply only to businesses that process daily card payments.
- The suitability of an advance still depends on the business's ability to meet the agreement.
The company reports funding more than 5,000 Canadian businesses. That establishes experience, not a prediction about your application or a substitute for reviewing your contract.
Before signing, ask how payments are collected and how the obligation fits your quieter trading periods. Verdict: Hold until the written agreement and your cash-flow forecast support the commitment.
2. BDC: best for development-bank financing
BDC is Canada's business development bank. Include BDC when you want to assess business financing through an organisation with a development mandate rather than treating every non-bank search result as the same kind of provider.
Start with the purpose of your application. Funding an expansion, buying equipment and supporting working capital require different conversations, even when the same organisation offers several financing routes.
Best for: A Canadian business assessing development-bank financing for a defined business purpose.
BDC pros:
- Its role as Canada's business development bank is clearly established.
- You can begin the discussion with the business objective rather than a generic funding request.
- It provides a useful comparison point when assessing other financing structures.
BDC cons:
- BDC's name alone does not tell you whether a particular financing product fits your business.
- You still need to assess the specific eligibility conditions, documentation and repayment obligation.
Do not assume that a development mandate means automatic qualification or that every product serves every business stage. Request the requirements for the actual financing under discussion.
Verdict: Hold until you identify a suitable product and confirm the application requirements.
3. Community Futures: best for rural business support
Community Futures organisations provide business development support and financing in rural communities. The relevant starting point is the organisation serving your location, not a national assumption about one standard offer.
For a rural business owner, local programme fit belongs near the top of the assessment. Confirm the service area, eligible business activities and intended use of funds before building an application around this route.
Best for: A rural Canadian business seeking locally delivered business financing and support.
Community Futures pros:
- The community-based model gives rural businesses a distinct starting point.
- Financing and business support can be considered together.
- Local programme information helps you assess geographic eligibility early.
Community Futures cons:
- Your business must fit the relevant service area and programme requirements.
- An offer or condition described by one local organisation does not establish the terms elsewhere.
Ask the local organisation which programmes match your business stage and intended expense. Keep that answer separate from any general information about the wider network.
Verdict: Hold until the local organisation confirms programme and geographic fit.
4. Invoice factoring providers: best for unpaid customer invoices
Invoice factoring involves selling receivables to a factoring provider under an agreement. It addresses money tied up in eligible customer invoices rather than funding based solely on your business's general sales outlook.
This makes factoring a specific tool, not a general substitute for every working-capital need. The invoices, the customers responsible for paying them and the contract all matter.
Best for: A business with eligible business-to-business receivables that needs to address a gap between invoicing and customer payment.
Invoice factoring pros:
- The funding need connects directly to existing receivables.
- You can assess the arrangement against identifiable invoices and customer payment dates.
- The structure distinguishes an invoice-collection gap from a lack of underlying sales.
Invoice factoring cons:
- A business without eligible invoices cannot use this structure for that purpose.
- Customer notification and collection arrangements require review.
- Recourse provisions can leave responsibilities with your business if customers do not pay.
Ask who contacts customers, who handles collections and what happens if an invoice is disputed. Do not assume that selling an invoice removes every payment-related obligation.
Verdict: Hold until invoice eligibility, customer handling and recourse terms are clear.
5. Equipment financing providers: best for an asset purchase
Equipment financing supports the acquisition of business equipment through arrangements such as equipment loans or leases. It belongs on your shortlist when the asset itself is the reason you need funding.
Separate the equipment decision from the financing decision. First establish that the asset serves a business need; then compare the obligations attached to acquiring it.
Best for: A business purchasing or leasing equipment for a defined operational purpose.
Equipment financing pros:
- The financing purpose connects to a specific asset.
- Equipment loans and leases provide different structures to evaluate.
- You can compare the payment obligation with the equipment's expected business use.
Equipment financing cons:
- An equipment-focused agreement does not solve unrelated payroll or inventory needs.
- Ownership, maintenance responsibilities and end-of-term provisions differ by agreement.
- Security and default provisions need review before you commit the asset or business.
Check whether you own the equipment during the agreement and what happens at its end. A payment figure alone does not answer either question.
Verdict: Hold until the ownership structure and full agreement match the asset's intended use.
How these options were ranked
This 2026 ranking follows distinct business needs: direct merchant cash advances, development-bank financing, rural support, receivables and equipment. It is not a ranking of approval likelihood or a claim that one provider offers the best terms to every applicant.
The order puts a direct working-capital option first, then separates routes whose suitability depends on a development mandate, geography, invoices or an asset. Use the criteria above to change the order for your business.
A rural equipment purchase, for example, deserves a different shortlist from an urban retailer's inventory requirement. The business purpose decides which entry moves to the top.
How to compare the offers you receive
Before choosing from alternative business lenders in Canada in 2026, put each written offer through the same review:
- Purpose: State the expense the funding will cover and why the business needs it.
- Repayment source: Identify the revenue or receivables expected to support the obligation.
- Total obligation: Read the complete amount owed, payment mechanics and any conditional charges together.
- Contract review: Check security, guarantees, default provisions and early-payment conditions before signing.
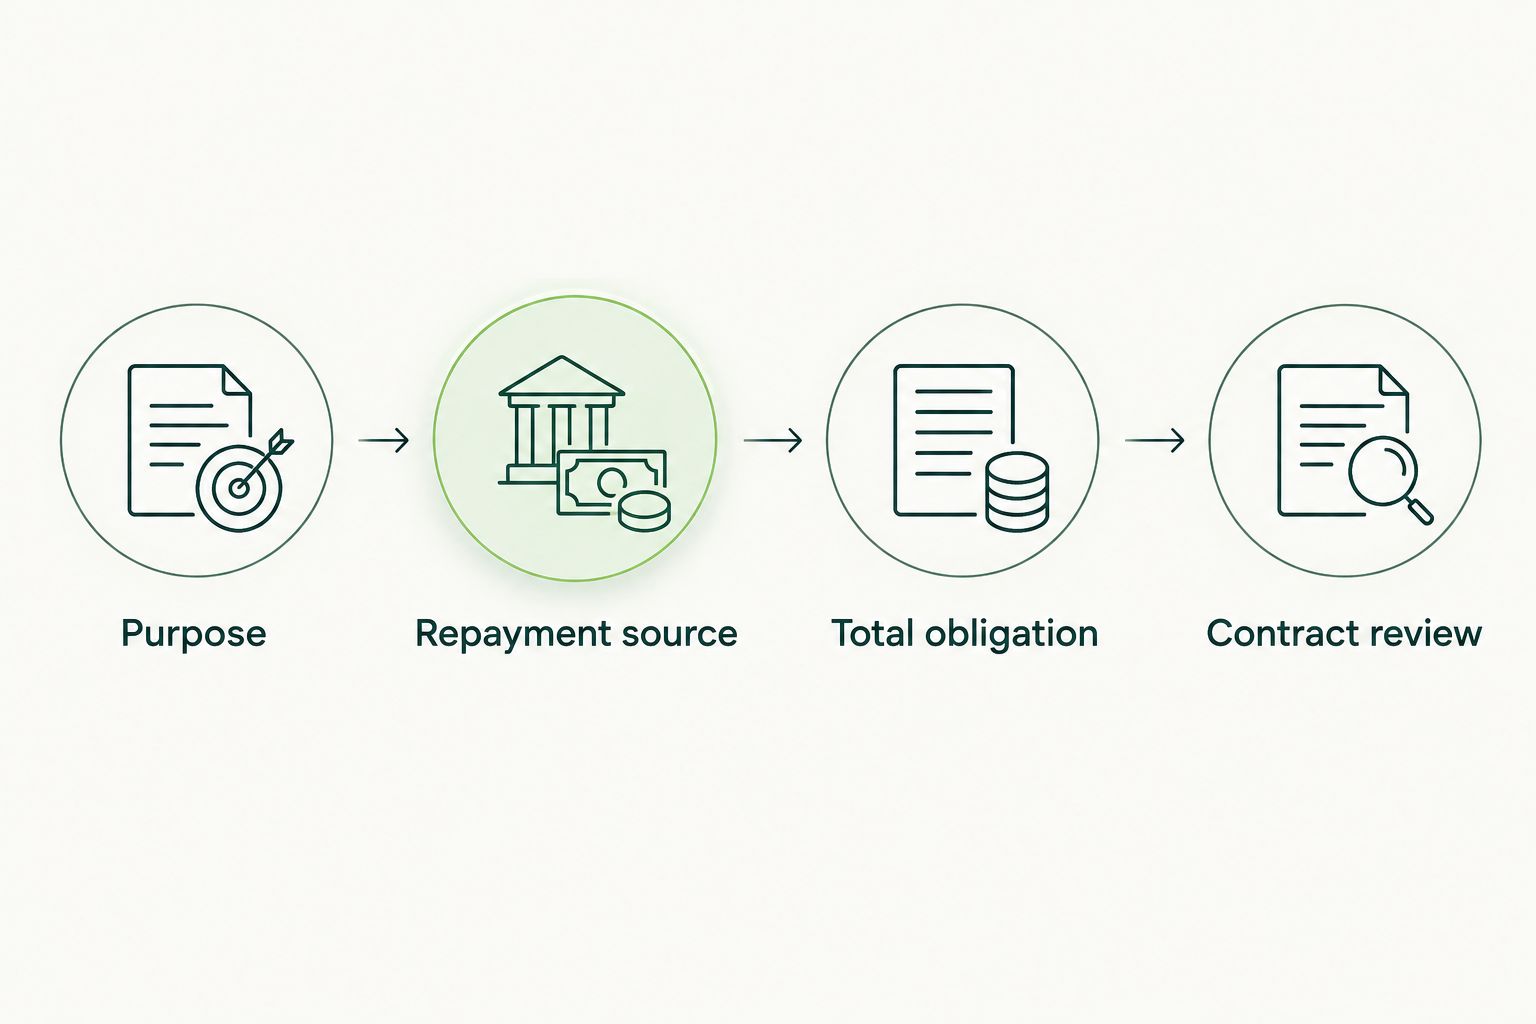
Compare the agreement against your business need, not just the approval decision.
Use a cash-flow forecast that reflects your actual trading pattern. Include existing commitments and customer payment timing, rather than treating every expected sale as money already collected.
Ask each provider to explain anything you cannot reproduce in your own forecast. A clear explanation should connect the contract to the way your business receives and spends money.
Which alternative business funding option should you choose?
2M7 is best suited to operating Canadian businesses seeking a direct merchant cash advance. If that describes your need, assess the stated eligibility baseline and request the written terms before deciding.
Choose a different starting point when the funding purpose is more specific: BDC for development-bank financing, Community Futures for rural programme fit, factoring for eligible invoices, or equipment financing for an asset purchase.
For your 2026 decision, the default is simple: shortlist by purpose, then compare contracts. Do not apply everywhere before establishing what kind of obligation your business can support.
Discuss your funding options
Speak with a funding specialist about your business purpose and eligibility.
Discuss funding options
FAQ
What's the best alternative business lender in Canada?
The best fit depends on your funding purpose, eligibility and repayment capacity. Compare direct merchant cash advances, development-bank financing, local programmes, factoring and equipment financing as different structures, not interchangeable offers.
Is a merchant cash advance the same as a business loan?
No. A merchant cash advance is not a conventional business loan. Review the advance agreement's payment structure and obligations rather than assuming that loan terminology applies.
Can I apply for business funding with less-than-perfect credit?
Some funders consider businesses with less-than-perfect credit. That does not establish approval; operating history, revenue and the provider's assessment still matter.
Is BDC the same as a private alternative lender?
No. BDC is Canada's business development bank. Assess its specific financing products separately from private funding arrangements.
Can Community Futures fund any Canadian business?
Community Futures financing depends on the relevant local organisation's service area and programme requirements. Start by confirming that your location and business fit the programme.
Is invoice factoring better than equipment financing?
Neither is universally better because they address different needs. Invoice factoring concerns eligible receivables, while equipment financing supports acquiring an asset.
What should I check before accepting business funding in 2026?
Check the full obligation, payment mechanics, security requirements, guarantees and default provisions. Compare those terms with your cash-flow forecast before signing.
One last thing
The reason cash is missing matters more than the label on the funding. Slow customer payments, an equipment purchase and an ongoing operating loss are different problems. Write down which one you are addressing before you request an offer.
That sentence becomes a practical filter. If the provider cannot connect the proposed structure to your stated need, return to the shortlist instead of forcing a fit.
Related guides


