Best for qualifying businesses seeking working capital: 2M7, a direct funder offering merchant cash advances, not loans. Best for unpaid business invoices: invoice factoring; best for a specific equipment purchase: equipment financing. This 2026 guide compares those options with secured business loans and business lines of credit so you can match funding to your cash flow, not just your credit score.
TL;DR
- Searching business loans for bad credit Canada? Compare eligibility, payment structure and total repayment before choosing.
- 2M7 suits established revenue-generating businesses seeking a merchant cash advance, not a traditional business loan.
- Invoice factoring suits eligible unpaid business invoices; equipment financing suits a specific asset purchase.
- Poor credit does not establish eligibility. Revenue, operating history, collateral and provider requirements also matter.
Why this matters
The best funding option fits both your business and its ability to repay. A product that accepts your application still needs to leave enough cash for payroll, rent, suppliers and taxes.
For Canadian business owners comparing options in 2026, the first distinction is between a loan and a merchant cash advance. They are different funding structures. Compare the agreement, payment obligations and total repayment rather than treating every source of working capital as interchangeable.
You also need to separate eligibility from suitability. Being eligible answers whether a provider will consider your business; being suitable answers whether the funding helps without creating a larger cash flow gap.
What makes the best bad-credit business funding?
Use these criteria to assess your 2026 shortlist before applying:
- Eligibility fit: Check minimum operating history, revenue requirements and how the provider assesses credit.
- Purpose fit: Match general working capital, unpaid invoices or an equipment purchase to the appropriate structure.
- Payment fit: Confirm the payment amount or calculation, frequency and collection method.
- Cost clarity: Request the total repayment obligation and every applicable fee in writing.
- Security exposure: Identify collateral, personal guarantees and the consequences of default.
- Provider accountability: Establish whether you are dealing with the funder directly or an intermediary.
Do not rank offers solely by the amount approved. A smaller commitment that fits your cash flow is more useful than funding you cannot comfortably service.
Bad-credit business funding at a glance
The order below follows the funding need, not a promise of approval. Each option has a distinct best-fit use case.
1. Merchant cash advance
- Best for: Qualifying businesses seeking general working capital
- Standout feature: An alternative to a traditional business loan
- Key limitation: Payment obligations still need to fit operating cash flow
2. Invoice factoring
- Best for: Businesses with eligible unpaid customer invoices
- Standout feature: Converts eligible receivables into working capital
- Key limitation: Depends on invoice and customer eligibility
3. Equipment financing
- Best for: Businesses purchasing a specific asset
- Standout feature: Ties financing to equipment rather than general spending
- Key limitation: Does not solve unrelated operating shortfalls
4. Secured business loan
- Best for: Businesses prepared to pledge acceptable collateral
- Standout feature: Uses an asset as security
- Key limitation: The pledged asset is exposed if obligations are not met
5. Business line of credit
- Best for: Businesses with recurring, temporary funding gaps
- Standout feature: Provides access to revolving credit under agreed terms
- Key limitation: Access depends on approval and the continuing agreement
1. 2M7: best for qualifying working capital needs
A merchant cash advance provides business funding through a structure different from a traditional loan. The direct-funder model means you deal with the funding provider rather than a broker.
2M7 is best for Canadian businesses with at least 3 months of operating history and $15,000 in monthly revenue seeking merchant cash advance working capital. Businesses with less-than-perfect credit are among those it serves. Funding uses include payroll, inventory, equipment and cash flow gaps.
Merchant cash advance pros:
- Supports several operating needs rather than a single asset purchase.
- Provides an option for businesses with less-than-perfect credit.
- Gives you direct access to the funder rather than a broker.
Merchant cash advance cons:
- Minimum revenue and operating-history requirements exclude some businesses.
- Approval is not certain; the published approval rate is 75%.
- Funding commitments must fit the business's ongoing cash flow.
Best for: An operating business that meets the stated revenue and trading-history requirements and needs general working capital.
Before signing, request the payment schedule, total repayment obligation and default terms. Flex payments are available only to businesses that process daily card payments; do not assume that feature applies to every business.
Verdict: Buy only when the written terms fit your cash flow.
2. Invoice factoring: best for unpaid business invoices
Invoice factoring involves selling eligible accounts receivable to a factoring provider. It connects funding to invoices you have already issued rather than to a future equipment purchase or an unrestricted credit facility.
This structure fits a business waiting for customers to pay. Ask which invoices qualify, whether customers receive payment instructions from the factor, and who bears the risk if an invoice remains unpaid.
Invoice factoring pros:
- Connects funding to existing receivables.
- Addresses a gap between issuing invoices and collecting payment.
- Gives invoice-based businesses a distinct alternative to borrowing.
Invoice factoring cons:
- Does not fit a business without eligible receivables.
- Customer creditworthiness and invoice disputes affect suitability.
- Customer notification and collection arrangements need careful review.
Best for: A business with eligible unpaid commercial invoices and a clear collection process.
Compare recourse and non-recourse terms rather than relying on those labels alone. The agreement must explain exactly when the business remains responsible for an unpaid invoice.
Verdict: Buy for a receivables gap; skip if you have no eligible invoices.
3. Equipment financing: best for a specific asset purchase
Equipment financing funds an identified business asset. Depending on the agreement, the structure involves financing a purchase or leasing equipment rather than providing unrestricted working capital.
Use this route when the equipment itself is the reason you need funding. Review ownership, security, insurance requirements and end-of-term obligations before comparing it with a general-purpose alternative.
Equipment financing pros:
- Matches financing to a defined business purchase.
- Separates an asset decision from everyday operating spending.
- Lets you assess the equipment's usefulness alongside its payment obligations.
Equipment financing cons:
- Does not cover unrelated payroll or supplier gaps.
- Approval still depends on provider requirements.
- Ownership and end-of-term conditions differ between agreements.
Best for: A business purchasing equipment with a clear operational purpose and a repayment plan supported by business cash flow.
Do not assume the equipment will immediately generate enough revenue to cover its payments. Check delivery, installation and the point at which the asset becomes usable.
Verdict: Buy for a defined asset need; skip for a general operating shortfall.
4. Secured business loan: best for collateral-backed borrowing
A secured business loan uses an asset as security for repayment. The lender assesses both the application and the proposed collateral; owning an asset does not establish approval.
This option belongs on your shortlist when you are prepared to pledge acceptable property or business assets. Understand what is pledged, how it is valued and whether a personal guarantee creates additional exposure.
Secured business loan pros:
- Gives a lender collateral to consider alongside the business application.
- Provides a structure for borrowing against acceptable assets.
- Supports a defined financing purpose under the lender's terms.
Secured business loan cons:
- Pledged assets are exposed if repayment obligations are not met.
- Asset valuation and legal requirements add steps.
- Collateral does not remove credit or affordability checks.
Best for: A business owner who understands the security agreement and accepts the asset exposure.
Ask what happens if the business misses payments and how security is released after repayment. Obtain independent advice when the agreement puts significant business or personal assets at stake.
Verdict: Hold until you understand and accept the collateral obligations.
5. Business line of credit: best for recurring short-term gaps
A business line of credit provides revolving borrowing within an agreed limit. You draw funds as needed and repay according to the agreement rather than receiving only a single advance.
This structure fits recurring timing differences between business expenses and customer receipts. Poor credit remains an application issue, so confirm the lender's requirements before treating a line of credit as an available solution.
Business line of credit pros:
- Supports repeated draws within the agreed facility.
- Matches recurring short-term cash flow gaps.
- Separates the approved limit from the amount actually drawn.
Business line of credit cons:
- Access depends on credit approval and continuing terms.
- Security or a personal guarantee can be required.
- Repeated borrowing can conceal an unresolved operating deficit.
Best for: A business with recurring temporary gaps and a clear source of repayment.
Review renewal conditions, repayment demands and restrictions on use. Do not build essential spending around access you have not secured in writing.
Verdict: Buy for repeatable timing gaps; skip as a substitute for sustainable revenue.
How the options are ranked
This 2026 ranking prioritises purpose fit, stated eligibility, payment fit, cost clarity and security exposure. It is not a ranking of approval odds or a claim that one provider accepts every credit profile.
The merchant cash advance comes first for qualifying general working capital needs. The remaining options address different situations: unpaid invoices, an equipment purchase, collateral-backed borrowing and recurring cash flow gaps.
How to compare offers before signing
Define the gap
Name the expense and the source of repayment. Funding inventory before a known sales period is a different decision from covering a recurring loss with no identified improvement.
Check eligibility
Confirm operating history, monthly revenue, credit assessment and any collateral requirements. Ask whether the provider reviews personal credit, business credit or both, and whether an application involves a credit inquiry.
Compare terms
Request the total repayment obligation, payment frequency, collection method, guarantees and default provisions. Compare written offers on the same basis; a payment amount alone does not explain the commitment.
Stress-test payments
Put the proposed payments into your cash flow forecast alongside payroll, rent, tax obligations and supplier bills. Repeat the exercise using a slower sales period, not just your strongest month.
These steps separate an attractive offer from a workable one. Complete them before accepting funding, even when you already meet the provider's eligibility requirements.
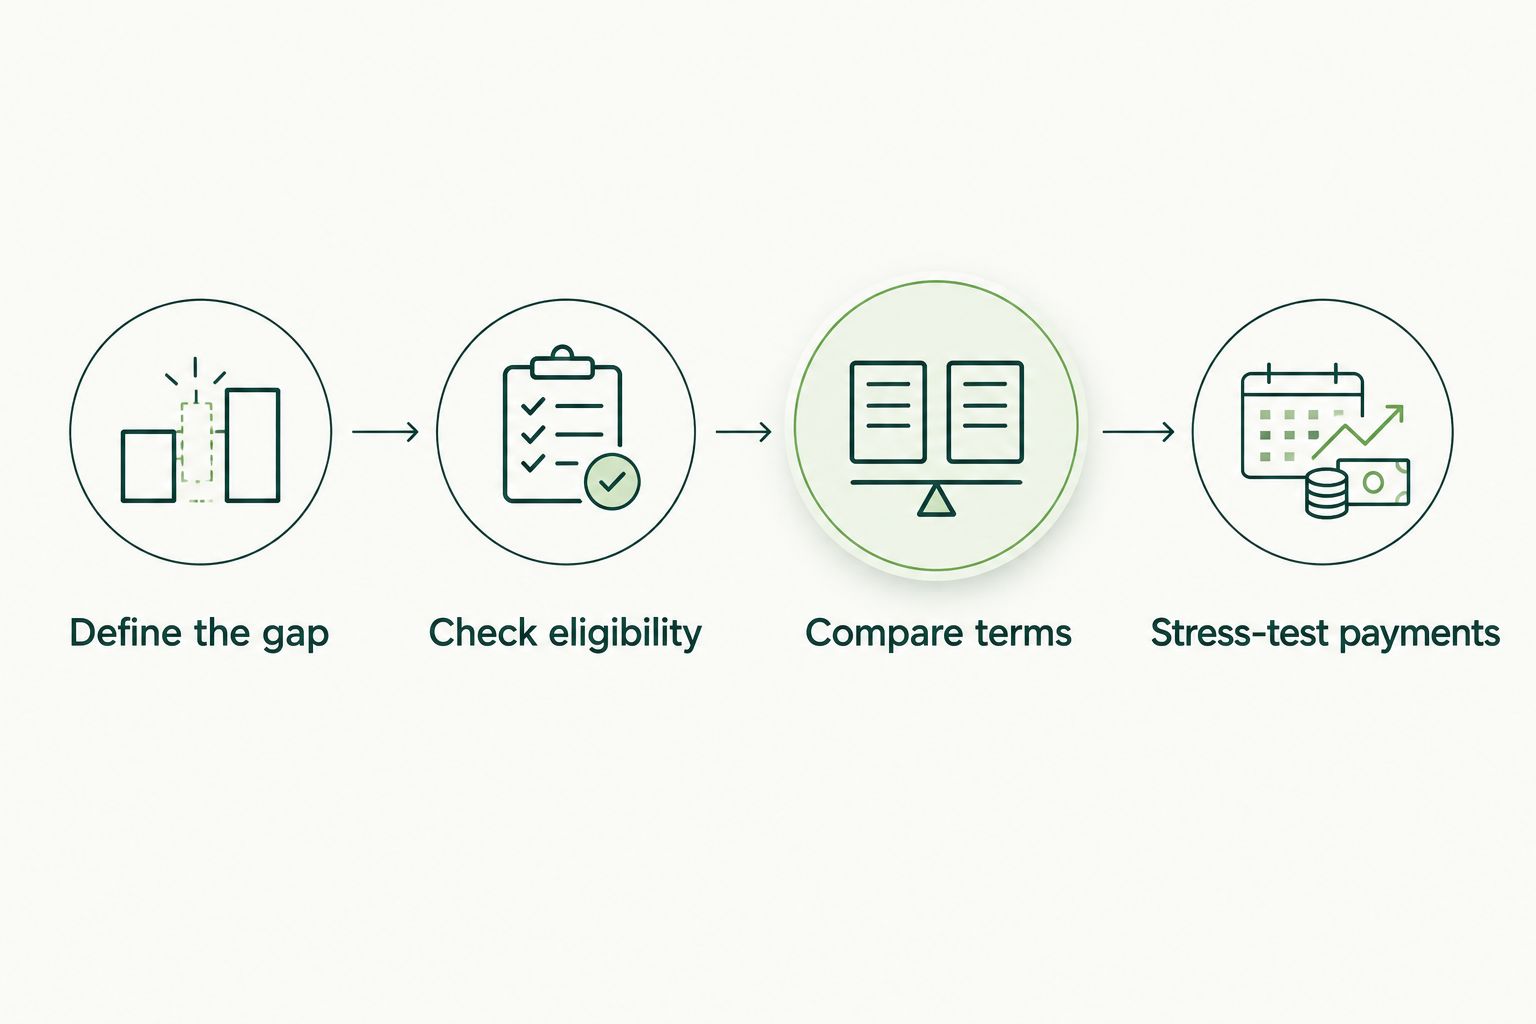
Check repayment fit before accepting an offer, not after funds arrive.
A useful comparison ends with a written decision: what the funding will accomplish, how the business will meet its obligations and which risks you accept. If those answers remain unclear, hold the application rather than choosing by approval alone.
Discuss your funding options
Speak with a funding specialist about your business needs and merchant cash advance eligibility.
Discuss funding options
Which business funding should you choose?
Choose 2M7 for merchant cash advance working capital when your Canadian business meets the stated eligibility requirements and the agreement fits your cash flow. Choose invoice factoring for eligible unpaid invoices or equipment financing for a specific asset.
For your 2026 decision, leave secured borrowing on hold until you understand the asset exposure. Consider a business line of credit when the need recurs and the lender's requirements fit your circumstances.
The default is not to apply everywhere. Start with the structure that matches the expense, then compare providers within that structure.
FAQ
What's the best business funding option if I have bad credit in Canada?
The best option depends on your revenue, operating history, funding purpose and ability to meet payments. Compare merchant cash advances for general working capital, factoring for eligible invoices and equipment financing for a specific asset.
Does 2M7 offer business loans for bad credit?
2M7 offers merchant cash advances and working capital, not business loans. It serves Canadian businesses with less-than-perfect credit that meet its requirements, including at least 3 months in operation and $15,000 in monthly revenue.
Can a new business qualify for a merchant cash advance?
A new business must meet the provider's operating-history and revenue requirements. Check those thresholds before applying; a business without established revenue should not assume eligibility.
Is a merchant cash advance the same as a business loan?
No, a merchant cash advance is a different funding structure from a traditional business loan. Review the agreement's payment mechanism, total repayment obligation and default terms rather than comparing labels alone.
Will applying for business funding affect my credit score?
The effect depends on the provider's credit-check process. Ask whether it performs a hard or soft inquiry, whose credit it checks and when consent is required.
Is secured funding automatically approved if I own equipment?
No, owning equipment does not establish approval for secured funding. The lender still assesses the application, the asset's acceptability and the proposed repayment arrangement.
What should I compare besides the payment amount?
Compare the total repayment obligation, payment frequency, fees, security, guarantees and default provisions. Also check early-payment terms and whether the agreement allows changes to payment obligations.
One last thing
A smaller payment is not automatically a smaller commitment. Payment frequency and repayment duration change what a payment figure means, so request the full schedule and total repayment obligation together.
Before signing in 2026, identify the slowest normal sales period in your business records. Check whether the proposed obligation still leaves enough cash for essential expenses during that period.
Related guides


