ClickCease

What Is a Merchant Cash Advance?

What Is a Merchant Cash Advance?

What Is A Merchant Cash Advance
11
May 2026
13
May 2026

A Smarter Way for Canadian Small Businesses to Manage Cash Flow

‍

Running a small business in Canada is one of the most rewarding things a person can do. It is also one of the most financially demanding. You have likely experienced the particular tension of knowing your business is performing well on paper while watching your bank account tell a different story. A major client is 60 days past due. A seasonal lull has arrived ahead of schedule. A supplier is offering a bulk discount that expires before your next revenue cycle closes.

This is the cash gap, and it has nothing to do with how well you run your business. It is simply the reality of operating in an economy built on delayed payments, unpredictable demand, and tight margins. For restaurant owners managing weekend rushes and mid-week lulls, for contractors waiting on draws from general contractors, for retailers carrying seasonal inventory before sales materialize, this gap is not a sign of failure. It is a structural challenge that every business owner eventually confronts.

The question is not whether the gap will appear. The question is what tool you reach for when it does.

‍

Proactive Capital vs. Reactive Borrowing

There is a meaningful difference between borrowing out of desperation and borrowing as a deliberate business strategy. Most business owners have experienced the former: scrambling to cover payroll, negotiating with suppliers, or dipping into personal savings to keep operations moving. That kind of reactive borrowing is stressful, often expensive, and tends to happen at the worst possible time.

Proactive capital is different. It means having access to funds before the emergency arrives, using financing to take advantage of opportunities rather than to avoid collapse. It might look like purchasing inventory at a bulk discount, hiring a key employee ahead of a growth period, or bridging a gap between two large contracts so your team stays intact and your momentum stays strong.

This is where fast working capital becomes a genuine asset. When a business owner understands their financing options before they need them, they can move quickly and with confidence. They become the kind of operator who says yes to opportunity rather than the kind who watches it pass.

‍

How a Merchant Cash Advance Actually Works

Most introductions to merchant cash advances cover the basics: a lender provides a lump sum of capital, and repayment comes through a percentage of your daily credit and debit card sales. That structure is accurate, but it undersells one of the most important features of this product.

An MCA functions as a fluctuating safety net. Because repayments are tied directly to your daily sales volume, your payment obligations contract automatically when business slows down. During a quiet January, a restaurant remits less. During a slow construction season, a contractor's burden eases. When volume picks back up, repayments adjust accordingly. There is no fixed monthly payment sitting on your books demanding the same amount whether you had a record week or a difficult one.

This is fundamentally different from a term loan, where a fixed payment comes out regardless of how business is going. For industries with natural revenue cycles, that rigidity can be genuinely dangerous. The flexible structure of merchant cash advances removes that rigidity, replacing it with a repayment rhythm that breathes alongside your business.

The approval process is also designed with the realities of small business in mind. Where a traditional bank will scrutinize years of financial statements, credit scores, and collateral, an MCA provider focuses on your actual sales history. Your revenue tells the story that matters.

‍

Strategic Use Cases: When an MCA Makes the Most Sense

There are specific situations where a merchant cash advance is clearly the better tool compared to a conventional bank loan. Here are the scenarios where business owners consistently find it valuable:

  • Seasonal inventory purchasing, where a retailer needs capital in October to stock for December but won't see revenue for six to eight weeks.
  • Emergency equipment repair, when a piece of critical machinery fails and a multi-week bank approval process would mean lost contracts and idle staff.
  • Bridging large contract gaps, particularly in construction and trades, where work is completed in one period but payment arrives weeks or months later.
  • Capitalizing on a time-sensitive supplier discount that requires immediate payment and delivers significant long-term savings.
  • Hiring and onboarding ahead of a known busy season, so the business is staffed and ready rather than scrambling mid-rush.

In each of these cases, speed and flexibility matter more than the cost comparison to a conventional loan. The opportunity cost of waiting is higher than the cost of the capital itself.

How Industry-Specific Businesses Use This Tool

In construction, the cash flow problem is almost universal. Materials need to be purchased, subcontractors need to be paid, and equipment needs to be maintained long before a draw schedule releases the next tranche of project funding. A merchant cash advance bridges that gap without requiring the collateral or credit profile that banks demand. Especially for construction companies, this kind of flexible capital is often the difference between taking on the next contract and turning it down.

In retail and food service, the challenges are different but equally real. Inventory decisions get made months in advance. Staffing ramps up before revenue does. A single slow season can destabilize months of careful planning. Having a capital partner who understands these cycles, and whose product is structured to accommodate them, changes how a business owner approaches their planning.

A Partnership Built for Resilience

2M7 is not simply a transaction. The goal is to function as a genuine partner in the financial health of your business, providing tools that help you maintain stability when the market becomes unpredictable and capture growth when the window opens.

Canadian small businesses deserve access to capital that was actually designed for the way they operate, not the way a spreadsheet imagines they operate. A merchant cash advance, used strategically and with clear intent, can be that tool.

Ready to Close Your Cash Gap?

If you are navigating a cash flow challenge or preparing for a growth opportunity and want to understand what funding might look like for your specific situation, the 2M7 team is ready to have that conversation. Reach out directly and speak with someone who understands the pressures you are managing.

‍

‍

Related articles

May 11, 2026
May 13, 2026

What Is a Merchant Cash Advance?

A Smarter Way for Canadian Small Businesses to Manage Cash Flow

‍

Running a small business in Canada is one of the most rewarding things a person can do. It is also one of the most financially demanding. You have likely experienced the particular tension of knowing your business is performing well on paper while watching your bank account tell a different story. A major client is 60 days past due. A seasonal lull has arrived ahead of schedule. A supplier is offering a bulk discount that expires before your next revenue cycle closes.

This is the cash gap, and it has nothing to do with how well you run your business. It is simply the reality of operating in an economy built on delayed payments, unpredictable demand, and tight margins. For restaurant owners managing weekend rushes and mid-week lulls, for contractors waiting on draws from general contractors, for retailers carrying seasonal inventory before sales materialize, this gap is not a sign of failure. It is a structural challenge that every business owner eventually confronts.

The question is not whether the gap will appear. The question is what tool you reach for when it does.

‍

Proactive Capital vs. Reactive Borrowing

There is a meaningful difference between borrowing out of desperation and borrowing as a deliberate business strategy. Most business owners have experienced the former: scrambling to cover payroll, negotiating with suppliers, or dipping into personal savings to keep operations moving. That kind of reactive borrowing is stressful, often expensive, and tends to happen at the worst possible time.

Proactive capital is different. It means having access to funds before the emergency arrives, using financing to take advantage of opportunities rather than to avoid collapse. It might look like purchasing inventory at a bulk discount, hiring a key employee ahead of a growth period, or bridging a gap between two large contracts so your team stays intact and your momentum stays strong.

This is where fast working capital becomes a genuine asset. When a business owner understands their financing options before they need them, they can move quickly and with confidence. They become the kind of operator who says yes to opportunity rather than the kind who watches it pass.

‍

How a Merchant Cash Advance Actually Works

Most introductions to merchant cash advances cover the basics: a lender provides a lump sum of capital, and repayment comes through a percentage of your daily credit and debit card sales. That structure is accurate, but it undersells one of the most important features of this product.

An MCA functions as a fluctuating safety net. Because repayments are tied directly to your daily sales volume, your payment obligations contract automatically when business slows down. During a quiet January, a restaurant remits less. During a slow construction season, a contractor's burden eases. When volume picks back up, repayments adjust accordingly. There is no fixed monthly payment sitting on your books demanding the same amount whether you had a record week or a difficult one.

This is fundamentally different from a term loan, where a fixed payment comes out regardless of how business is going. For industries with natural revenue cycles, that rigidity can be genuinely dangerous. The flexible structure of merchant cash advances removes that rigidity, replacing it with a repayment rhythm that breathes alongside your business.

The approval process is also designed with the realities of small business in mind. Where a traditional bank will scrutinize years of financial statements, credit scores, and collateral, an MCA provider focuses on your actual sales history. Your revenue tells the story that matters.

‍

Strategic Use Cases: When an MCA Makes the Most Sense

There are specific situations where a merchant cash advance is clearly the better tool compared to a conventional bank loan. Here are the scenarios where business owners consistently find it valuable:

  • Seasonal inventory purchasing, where a retailer needs capital in October to stock for December but won't see revenue for six to eight weeks.
  • Emergency equipment repair, when a piece of critical machinery fails and a multi-week bank approval process would mean lost contracts and idle staff.
  • Bridging large contract gaps, particularly in construction and trades, where work is completed in one period but payment arrives weeks or months later.
  • Capitalizing on a time-sensitive supplier discount that requires immediate payment and delivers significant long-term savings.
  • Hiring and onboarding ahead of a known busy season, so the business is staffed and ready rather than scrambling mid-rush.

In each of these cases, speed and flexibility matter more than the cost comparison to a conventional loan. The opportunity cost of waiting is higher than the cost of the capital itself.

How Industry-Specific Businesses Use This Tool

In construction, the cash flow problem is almost universal. Materials need to be purchased, subcontractors need to be paid, and equipment needs to be maintained long before a draw schedule releases the next tranche of project funding. A merchant cash advance bridges that gap without requiring the collateral or credit profile that banks demand. Especially for construction companies, this kind of flexible capital is often the difference between taking on the next contract and turning it down.

In retail and food service, the challenges are different but equally real. Inventory decisions get made months in advance. Staffing ramps up before revenue does. A single slow season can destabilize months of careful planning. Having a capital partner who understands these cycles, and whose product is structured to accommodate them, changes how a business owner approaches their planning.

A Partnership Built for Resilience

2M7 is not simply a transaction. The goal is to function as a genuine partner in the financial health of your business, providing tools that help you maintain stability when the market becomes unpredictable and capture growth when the window opens.

Canadian small businesses deserve access to capital that was actually designed for the way they operate, not the way a spreadsheet imagines they operate. A merchant cash advance, used strategically and with clear intent, can be that tool.

Ready to Close Your Cash Gap?

If you are navigating a cash flow challenge or preparing for a growth opportunity and want to understand what funding might look like for your specific situation, the 2M7 team is ready to have that conversation. Reach out directly and speak with someone who understands the pressures you are managing.

‍

‍

Read more
October 15, 2026
October 15, 2026

Best alternative business financing options in Canada 2026

Best overall for eligible businesses seeking sales-based working capital: 2M7 merchant cash advances. Best for recurring borrowing: a business line of credit; best for unpaid invoices: invoice factoring. This 2026 guide compares six alternative business financing options in Canada by funding purpose, eligibility and repayment fit.

TL;DR

  • 2M7 merchant cash advances suit eligible Canadian businesses seeking alternative business financing for working capital.
  • Business lines of credit suit recurring borrowing; invoice factoring suits businesses waiting on customer invoices.
  • Equipment financing matches funding to assets; purchase order financing supports eligible supplier payments.
  • Equity financing suits growth plans where owners accept shared ownership instead of scheduled repayments.

Why this matters

The best financing option matches the expense, the cash coming back and the repayment obligation. An equipment purchase, an unpaid invoice and a payroll gap are different problems. Treating them as the same borrowing need makes comparison harder.

For your 2026 funding decision, start with the transaction rather than the provider. Identify what you need to pay, when that spending produces cash and which repayment structure your business can support. Then compare written offers within the right category.

What makes the best alternative business financing?

Use these criteria to shortlist funding before you submit applications:

  • Funding purpose: Match unrestricted working capital, invoice funding or asset financing to the actual expense.
  • Eligibility fit: Check operating history, revenue, customer quality and security requirements before applying.
  • Repayment fit: Compare payment frequency and obligations with the timing of your receipts.
  • Total obligation: Read the complete repayment amount, charges, guarantees and contractual conditions together.
  • Ownership impact: Separate financing that creates payment obligations from investment that shares ownership.
  • Exit terms: Understand early settlement, cancellation, renewal and security-release provisions before signing.

These criteria matter more than a headline approval claim. A funding offer belongs on your shortlist only when you understand both how it helps and what your business commits to.

Alternative business financing at a glance

This 2026 ranking gives each option a distinct job. The order is a decision guide, not a claim that one funding structure beats every other structure.

2M7 merchant cash advance

  • Best for: Eligible businesses seeking sales-based working capital
  • Standout feature: Direct funding with one fixed cost of capital disclosed before signing
  • Key limitation: Minimum operating history and revenue requirements apply

Business line of credit

  • Best for: Recurring short-term borrowing
  • Standout feature: Draw, repay and reuse credit within the agreement
  • Key limitation: Access depends on approval and account terms

Invoice factoring

  • Best for: Businesses waiting on customer invoices
  • Standout feature: Funding tied to eligible receivables
  • Key limitation: Customer-facing collection arrangements need review

Equipment financing

  • Best for: Purchasing business equipment
  • Standout feature: Financing connected to a specific asset
  • Key limitation: Not a general solution for unrelated operating expenses

Purchase order financing

  • Best for: Supplier payments for confirmed customer orders
  • Standout feature: Funding connected to order fulfilment
  • Key limitation: Order, supplier and transaction eligibility restrict its use

Equity financing

  • Best for: Growth without scheduled financing repayments
  • Standout feature: Capital exchanged for an ownership interest
  • Key limitation: Owners give up a share of ownership and potentially control

1. 2M7 merchant cash advances: best for sales-based working capital

A merchant cash advance provides business funding against future sales. 2M7 is a Canadian direct funder, not a broker, providing merchant cash advances and working capital for expenses such as payroll, inventory, equipment and cash flow gaps.

2M7 merchant cash advances are best for eligible Canadian businesses seeking sales-based working capital rather than a conventional loan. Businesses must have operated for at least 3 months and generate $15,000 or more in monthly revenue. Businesses with less-than-perfect credit are among those served.

2M7 merchant cash advance pros:

  • You deal with a direct funder rather than a broker.
  • Funding supports several operating purposes, including payroll and inventory.
  • One fixed cost of capital is shown before signing and does not change with repayment duration.

2M7 merchant cash advance cons:

  • Businesses below the operating-history or revenue thresholds do not meet the stated criteria.
  • Flexible payments are only for businesses that process daily card payments.
  • A fixed cost does not remove the need to check whether payments fit your cash flow.

Best for: An operating business with established revenue and a defined working-capital need.

Verdict: Hold until the written payment structure fits your cash flow. Meeting eligibility requirements is the starting point, not the final decision.

2. Business lines of credit: best for recurring borrowing

A business line of credit lets you draw funds up to an approved limit and reuse repaid amounts under the agreement. Banks, credit unions and non-bank providers offer credit facilities, so compare the actual contract rather than treating the provider category as the deciding factor.

A business line of credit fits repeated gaps between outgoing payments and incoming receipts. It is less useful when an ongoing operating loss, rather than timing, drives the need for funds.

Business line of credit pros:

  • You can draw funds as needs arise within the approved limit.
  • Repaid amounts become available again under revolving terms.
  • One facility can support different short-term operating expenses.

Business line of credit cons:

  • Approval, security and guarantee requirements vary by provider.
  • Review provisions and account conditions affect continued access.
  • Repeated borrowing can conceal a persistent cash shortfall.

Best for: Businesses with recurring, identifiable cash timing gaps and a clear repayment source.

Verdict: Hold until you have reviewed draw conditions and renewal terms. Choose a business line of credit for repeat use, not simply because the available limit looks attractive.

3. Invoice factoring: best for unpaid customer invoices

Invoice factoring converts eligible receivables into funding by selling invoices to a factor. The arrangement centres on customer invoices, so customer credit quality and invoice eligibility matter alongside your own business profile.

Invoice factoring is a focused option for businesses that have completed work but are waiting for payment. It does not solve a lack of sales, disputed billing or an expense unsupported by eligible receivables.

Invoice factoring pros:

  • Funding connects to work already invoiced.
  • Customer payment quality forms part of the assessment.
  • Collections support can form part of the arrangement.

Invoice factoring cons:

  • Disputed or otherwise ineligible invoices limit what you can fund.
  • Customer notification and collection practices need careful review.
  • Recourse terms determine your responsibility if a customer does not pay.

Best for: Business-to-business suppliers and service providers with eligible, unpaid invoices.

Verdict: Hold until you understand recourse and customer contact. Ask who collects payment, what customers receive and what happens when an invoice remains unpaid.

4. Equipment financing: best for a specific asset purchase

Equipment financing connects funding to machinery, vehicles or other business equipment. Depending on the agreement, the structure involves financing a purchase or leasing the asset, with different ownership and end-of-term obligations.

Choose equipment financing when the asset itself is the reason you need funding. Keep operating cash needs separate so you can assess whether the asset's business value supports the commitment.

Equipment financing pros:

  • The funding purpose is tied to an identifiable asset.
  • You can compare the agreement against the equipment's expected business use.
  • Purchase and lease structures offer different ownership arrangements.

Equipment financing cons:

  • Asset-linked funding does not necessarily cover payroll or other operating expenses.
  • Maintenance, insurance and end-of-term obligations require review.
  • Equipment can lose usefulness while contractual payments continue.

Best for: Businesses acquiring equipment with a clear operating purpose.

Verdict: Hold until ownership and end-of-term terms are clear. Compare equipment financing agreements using the full commitment, not just the payment shown on a proposal.

5. Purchase order financing: best for supplier payments

Purchase order financing supports eligible supplier payments associated with confirmed customer orders. The funder assesses the transaction, including the order, customer, supplier and fulfilment arrangements.

Purchase order financing fits an order-specific gap: you have a customer commitment but need funding to obtain the goods. It is not interchangeable with general working capital for unrelated expenses.

Purchase order financing pros:

  • Funding connects to an identifiable customer order.
  • Supplier payments are central to the structure.
  • You can assess the funding commitment against a specific transaction.

Purchase order financing cons:

  • Not every order, supplier or transaction qualifies.
  • Delivery, acceptance and customer payment conditions complicate the arrangement.
  • Financing obligations must fit the order's remaining margin.

Best for: Businesses fulfilling eligible confirmed orders that require supplier payments before customer receipts.

Verdict: Hold until the complete order economics work. Account for supplier, shipping, fulfilment and financing obligations before accepting funding.

6. Equity financing: best for growth with shared ownership

Equity financing brings capital into a business in exchange for an ownership interest. Unlike funding with scheduled repayments, the central trade-off is ownership, investor rights and the expectations attached to the investment.

Equity financing suits growth plans where an owner accepts an investment partner. A temporary cash timing problem alone is not a strong reason to give up ownership.

Equity financing pros:

  • Equity capital does not carry the same scheduled repayment structure as borrowing.
  • An investment agreement can support a longer-term growth plan.
  • Investors can contribute expertise or connections alongside capital.

Equity financing cons:

  • Existing owners give up part of their ownership.
  • Investor rights can affect decisions, reporting and future fundraising.
  • Negotiating ownership and governance takes preparation.

Best for: Businesses pursuing growth where shared ownership fits the owner's objectives.

Verdict: Hold until ownership and governance terms are understood. Assess the investor relationship as carefully as the capital offered.

How we ranked these financing options

The 2026 ranking follows funding purpose, eligibility fit, repayment fit, total obligation, ownership impact and exit terms. Each option earns a different use-case slot; the comparison does not claim that all businesses qualify or that all providers offer identical terms.

Merchant cash advances lead for eligible sales-based working capital. Business lines of credit address recurring borrowing, invoice factoring addresses receivables, equipment financing addresses assets, purchase order financing addresses orders, and equity financing addresses ownership-based investment.

Which financing option should you choose?

For an undecided owner, choose the category before the provider. Follow this sequence for your 2026 shortlist:

  1. Funding purpose: Name the expense and explain how it supports your business.
  2. Cash timing: Map customer receipts against the proposed payment obligations.
  3. Contract terms: Compare the full commitment, guarantees, security and exit provisions.
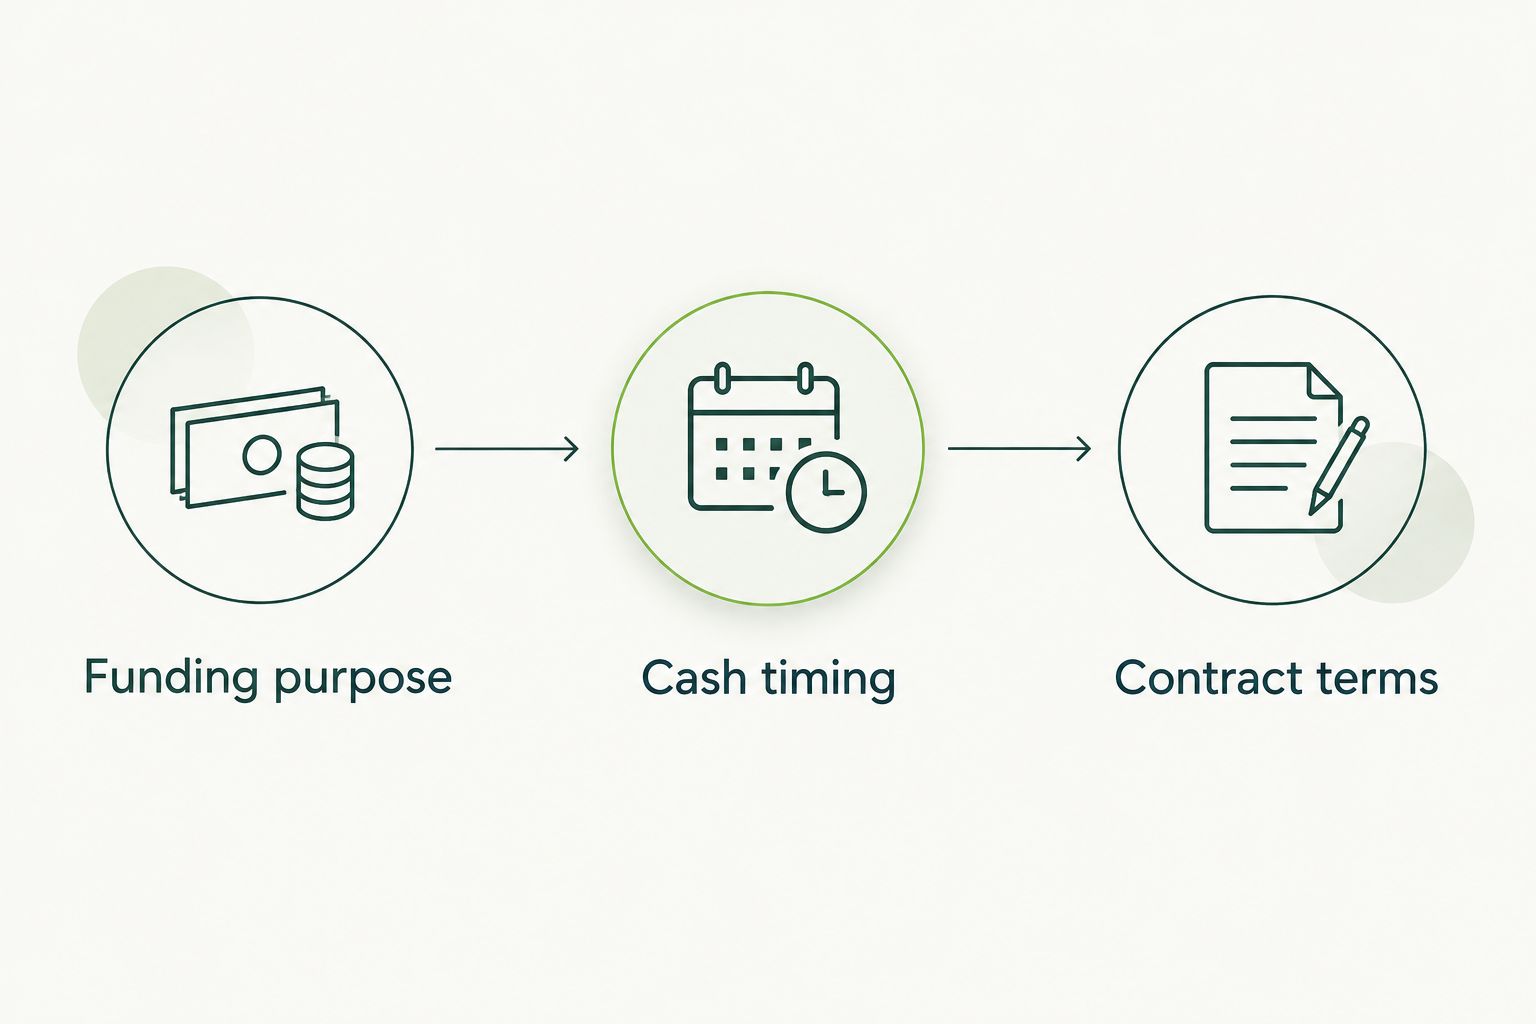
Three decision steps: funding purpose, cash timing and contract terms

Choose the funding category before comparing provider offers.

If you need general working capital and meet the stated operating and revenue thresholds, start by discussing a merchant cash advance. If the need comes from an invoice, an asset or a customer order, start with the category designed around that transaction.

Before signing, prepare a cash flow forecast showing the proposed obligation alongside payroll, supplier payments and existing commitments. Approval answers whether a funder will proceed. Your forecast answers whether the arrangement works for your business.

FAQ

What's the best alternative business financing option in Canada?

The best alternative business financing option depends on the funding purpose and repayment fit. Merchant cash advances address eligible working-capital needs, while invoice factoring, equipment financing and purchase order financing address specific transactions.

Is a merchant cash advance a business loan?

A merchant cash advance is funding against future sales, not a conventional business loan. Review the agreement's payment structure, total obligation and conditions before signing.

What does a business need to qualify for 2M7 funding?

The stated minimums are at least 3 months in business and $15,000 or more in monthly revenue. Meeting those thresholds does not establish approval or determine the final funding terms.

Is invoice factoring better than a business line of credit?

Invoice factoring fits eligible unpaid invoices, while a business line of credit fits recurring borrowing needs. Compare invoice eligibility, collection arrangements and recourse against the credit facility's draw and repayment conditions.

Can a business with less-than-perfect credit seek funding?

Businesses with less-than-perfect credit can seek funding from providers whose criteria include them. Approval still depends on the provider's assessment and the business meeting applicable requirements.

Do merchant cash advances always have flexible payments?

Do not assume every merchant cash advance has flexible payments. Confirm the written terms; the flexible-payment feature described in this guide is only for businesses that process daily card payments.

What should I compare besides the payment amount?

Compare the total obligation, payment frequency, guarantees, security and exit terms. For equity financing, also compare ownership dilution, investor rights and governance requirements.

One last thing

Approval is not a cash flow plan. Before accepting alternative business financing in 2026, place the proposed obligations into a quieter-sales scenario using your own records. If the plan depends on every customer paying promptly, revisit the amount or structure before signing.

Related guides

Read more
May 4, 2026
October 2, 2026

Which Industries Benefit the Most from Merchant Cash Advance?

According to the Canadian Federation of Independent Business (CFIB), 2025 was a divided year for Canadian small business: while 37% of owners reported a good year in terms of revenues and profits, 35% reported a poor one. The smallest firms felt it most. Among businesses with fewer than five employees, only 35% described 2025 as a good year, compared to 42% of larger firms. Tariff pressures, high operating costs, and slowing business dynamism have left many owners caught in a difficult position.

For those who have turned to the bank for help, the options are often limited. The federal government's Canada Small Business Financing Program (CSBFP) issued just 6,409 loans totalling nearly $1.9 billion in 2024-25, a record in program history. But with approximately 1.2 million small businesses in Canada, the reach of traditional financing programs remains narrow. The average CSBFP loan size was $294,067, which is far more than what most small business owners need to solve a specific, immediate cash flow problem.

A Merchant Cash Advance (MCA) is one alternative worth understanding. It is not a bank loan. It is an advance on your future revenue, repaid as a percentage of daily sales, with a single fixed cost of capital disclosed upfront. There are no interest charges, no hidden fees, and no collateral requirements.

Some industries tend to benefit from this kind of flexible, short-term working capital more than others. Below are five industries which benefit from a merchant cash advance:

1. Restaurants and Food Service

Canada's foodservice sector added nearly 24,000 jobs between January and November 2025 according to Restaurants Canada, a sign that demand is holding up. Growth, however, requires capital, and restaurant revenue is inherently unpredictable. Equipment needs replacing without warning. A slow season can erode a cash position that looked healthy a few months earlier. Traditional lenders typically want two or more years of financial history and strong collateral before approving financing, which many independent restaurant owners cannot provide.

A merchant cash advance can provide working capital in the range of $5,000 to $300,000, with approval typically within one business day and funds deposited within 24 hours. Because repayments are tied to a percentage of daily sales, owners pay more when business is strong and less when it slows. This structure suits the seasonal and variable nature of restaurant revenue better than a fixed monthly payment.

One restaurant owner who used 2M7 funding for a kitchen equipment upgrade described the experience this way: "Highly recommend 2M7 if you are planning any big purchases. They helped us get funding for the new kitchen equipment and we continue to upgrade our facility."

2. Construction and Trades

Construction businesses routinely face a timing problem: materials, equipment, and labour costs arrive before client payments do. Payment terms of 30, 60, or even 90 days are common, which means contractors are often funding project costs out of their own cash flow while waiting for invoices to clear. Banks are generally reluctant to lend against this kind of irregular, project-based revenue, which leaves many contractors with limited options when they need capital quickly.

A merchant cash advance can help bridge the gap between project start and payment receipt, allowing contractors to cover immediate costs without waiting on a lengthy approval process or pledging personal assets.

Sean Morales, who needed funding for a demolition project, noted: "We need funds for a demolition project for our office. These guys got it done in less than 24 hrs."

More information on how working capital applies to the construction sector is available on 2M7's construction and trades funding page.

3. Retail and E-Commerce

Canadian e-commerce orders rose 20% in 2025 according to Omnisend, reflecting continued growth in both online and in-store retail. Sustaining that growth requires inventory investment well ahead of actual sales. Retailers need to order stock months before peak seasons, and suppliers often require payment before goods are delivered. A bank approval process that takes weeks is rarely compatible with those timelines.

Merchant cash advances allow retailers to access the capital they need for inventory, seasonal staffing, or store improvements without lengthy documentation requirements or the need to pledge collateral.

Morgan Lowe, a boutique retailer who used an MCA to expand her store, said: "I am a small business owner that just recently expanded and was struggling to find funding. 2M7 came through and has been wonderful to deal with."

For businesses where inventory is the core challenge, the impact can be ongoing. Visionary Hydroponics noted: "We are a small business and maintaining inventory can be a challenge. These types of [advances] help keep product on the shelf."

Details on how 2M7 works with retailers are available on the retail inventory and growth funding page.

4. Trucking and Transportation

BMO's Fall 2025 Canada Truck Transportation update describes the Canadian trucking industry as still in a fragile state, with trade barriers and tariff uncertainty continuing to weigh on domestic and cross-border freight volumes, rates, and fleet fundamentals. For owner-operators and small fleets, this means running lean while still needing to cover fuel, maintenance, and payroll between loads.

Traditional financing in this sector often requires an established credit history and years of documented revenue, which can be difficult to demonstrate during a period of industry-wide softness. A merchant cash advance offers a more accessible path to short-term working capital, with repayments that adjust alongside revenue rather than remaining fixed regardless of conditions.

More detail on how this applies to transportation businesses is available on 2M7's trucking funding page.

5. Landscaping and Seasonal Businesses

Seasonal businesses face a structural cash flow challenge that most financing products are not designed for. Revenue arrives in concentrated bursts, while costs related to insurance, equipment upkeep, and preparing for the next season continue year-round. A lender evaluating a landscaping company's winter financials will often see a picture that looks worse than the underlying business actually is.

The CFIB's December 2025 survey found that smaller firms are the most vulnerable to sudden cost pressures and disruptions. For seasonal operators, that kind of pressure is predictable and recurring rather than exceptional.

A merchant cash advance with flexible repayment can work with this pattern rather than against it. When revenue is strong in peak season, repayments reflect that. When it drops in the off-season, repayments decrease proportionally. Owners are not locked into a fixed payment schedule that ignores the realities of how their business operates.

Who Qualifies

Businesses interested in a merchant cash advance through 2M7 need to meet a straightforward set of criteria:

  • The business is located in Canada
  • The business has been operating for at least 3 months
  • Monthly revenue is at least $15,000
  • There are no open bankruptcies

No collateral is required. Approval decisions take into account overall revenue and business activity, not credit score alone.

How Repayment Works

2M7 offers two repayment structures. Fixed payments mean the same amount is debited on a regular schedule, with the option to request a reduction if revenue drops significantly. Flex payments are tied directly to a percentage of daily sales, so repayment amounts naturally rise and fall with business activity. The flex option is available to businesses that process daily credit and debit transactions.

Before signing, the total cost of capital is presented clearly. There are no origination fees, application fees, interest charges, brokerage fees, annual maintenance fees, or early repayment penalties. The cost disclosed upfront is the only cost.

Once a business is an existing client, requesting additional funding is straightforward. Clients can contact their dedicated representative directly by phone or text, and if approved, funds can be deposited within 30 minutes.

What Business Owners Have Said

"2M7 greatly guided us through the entire process of funding for our small business. We're extremely pleased with their clear explanations of what to expect and their steady commitment to helping us." -- Kotryna Zis

"Had the pleasure of dealing with 2M7 and Yakov, who helped our business get approved with funds in my account the next day. Greatly appreciate their help. Everything that we talked about was provided." -- Brady Douglas

"2M7 has been so wonderful to work with. Every employee I speak with is incredibly helpful and kind. I would never have been able to get back on my feet after COVID-19 if not for them." -- Jenny Watson

Is a Merchant Cash Advance Right for Your Business?

A merchant cash advance is not the right fit for every situation. It works best for businesses that have consistent revenue, need capital quickly, and want repayment terms that reflect how their business actually performs rather than a fixed schedule set by a lender.

Canada's government financing programs reached fewer than 6,500 businesses last year in a country with over a million small businesses. For many owners who fall outside the criteria those programs require, alternative working capital solutions are worth exploring.

If your business is based in Canada, has been operating for at least three months, and brings in at least $15,000 per month in revenue, you can check your eligibility with 2M7 without a lengthy application process.

Related reading: What is a Merchant Cash Advance? 2M7 vs. Other Merchant Cash Advance Options The Truth About Small Business Loans 5 Low-Cost Ways to Market Your Small Business in Canada

Sources: CFIB: A Divided Year, Small Business Performance in 2025 ISED: Canada Small Business Financing Program, Overview and Highlights 2024-25 Retail Insider / Restaurants Canada: Foodservice sector added nearly 24,000 jobs in 2025 BMO: Industry Update, Canada Truck Transportation, Fall 2025 Retail Insider / Omnisend: Canadian E-Commerce Orders Rose 20% in 2025

‍

Read more